


MSA Safety (MSA) Could Be 14% Undervalued As Replacement Cycle Comes Into View
MSA Safety (MSA) drew fresh attention after its recent trading session left the stock at $180.71, with investors weighing that price against the company’s current value score of 2 and broader return profile.
Recent trading has been choppy for MSA Safety, with a 1-day share price return of 1.47% sitting against a 7-day share price return that slipped 1.32% and a 30-day share price return that eased 0.81%. A 90-day share price return of 7.67% and year-to-date share price return of 11.38% pair with a 1-year total shareholder return of 8.04%, indicating momentum that has cooled slightly in the near term. However, this still aligns with a sturdier multi year total shareholder return profile of 21.28% over three years and 26.40% over five years. Investors are weighing this performance against the company’s value score of 2 at the current US$180.71 share price.
Compare MSA Safety’s recent run with a curated set of resilient peers by scanning the 31 resilient stocks with low risk scores that aim to pair relatively steadier risk profiles with the possibility of more consistent returns.
MSA Safety has just logged a fresh move at US$180.71 while analyst targets and intrinsic estimates sit well above that mark. How wide is the gap between recent price action and fair value estimates?
Most Popular Narrative: 14% Undervalued
Against MSA Safety’s last close at $180.71, the most followed narrative points to a fair value of $209.14, implying a clear valuation gap built on specific growth and margin assumptions.
The upcoming replacement cycle for the large G1 SCBA cohorts sold between 2015 and 2019, with management expecting unit volumes from 2027 to 2029 to be at least 50% above the past three years at higher price points, can provide a multi year revenue tailwind and support earnings.
See why 4 investors see MSA Safety as 14% undervalued.
Result: Fair Value of $209.14 (UNDERVALUED)
Still, the thesis on MSA Safety can be knocked off course if Middle East related detection weakness persists, or if higher transport and material costs squeeze margins longer than expected.
Find out about the key risks to this MSA Safety narrative.
Another View: What MSA Safety’s P/E Is Telling You
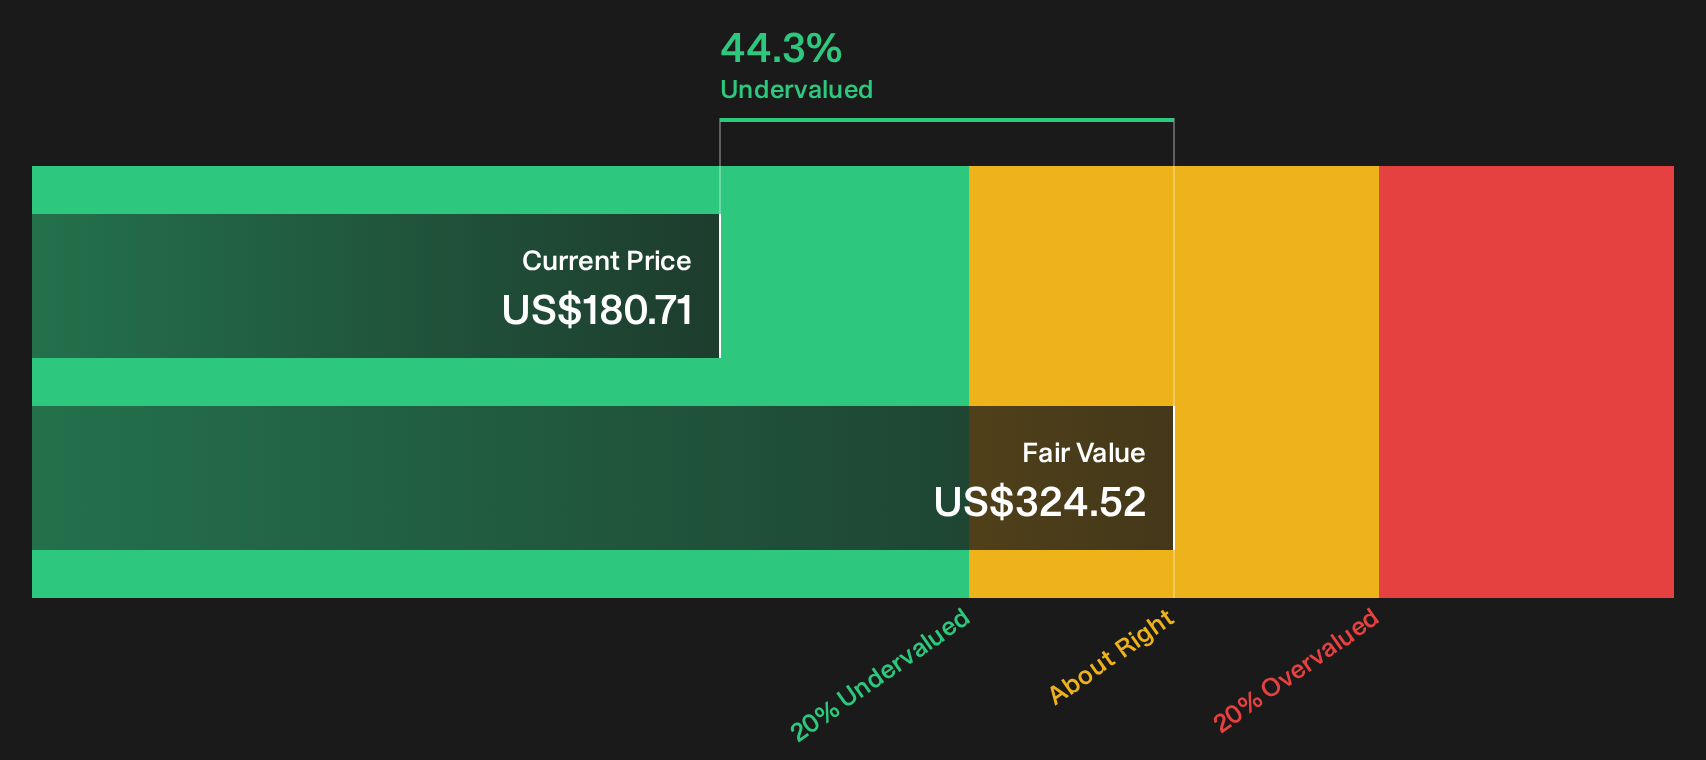
The SWS DCF model points to MSA Safety trading at a discount to an estimated future cash flow value of $324.52, which is well above the current $180.71 share price. That suggests a very different story from the analyst fair value of $209.14 and raises a simple question: Which set of assumptions do you trust more for your own framework?
Before leaning too heavily on any single approach, it is worth seeing how the SWS DCF model pieces together cash flows, margins, and required returns into that $324.52 figure Look into how the SWS DCF model arrives at its fair value.
Next Steps
Plenty of signals around MSA Safety point in different directions, so move quickly, pull up the full dataset, and weigh the trade off between the stock’s risks and rewards for yourself with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond MSA Safety?
If you stop with MSA Safety, you only see one angle. Broaden your watchlist with fresh opportunities built from the same data driven approach on Simply Wall Street.
- Target potential mispricings by scanning the 29 high quality undervalued stocks that line up quality fundamentals with prices that may not fully reflect them.
- Strengthen your income stream by reviewing the 8 dividend fortresses that combine higher yields with a focus on sustainability.
- Build a sturdier portfolio core by filtering for the list of solid balance sheet and fundamentals (25 results) that can help support returns when conditions get tougher.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com