


Does AI Operations Launch Change The Bull Case For Elastic (ESTC)?
- Elastic announced the private preview of nightshift AI SRE within Elastic Observability and introduced AlertZero in Elastic Security, both agentic AI systems that handle continuous detection, investigation and recommended remediation across operations and cyber workloads.
- Together, these AI agents push Elastic deeper into automated observability and security workflows. This could influence data consumption patterns, deployment choices and how large customers embed the platform into day to day operations.
- We will now look at how Elastic's investment narrative could be shaped by the launch of the nightshift AI SRE capability.
Elastic Investment Narrative Recap
To stay invested in Elastic, you need to believe the company can turn strong interest in AI driven search, observability and security into steady usage growth from large customers, even as competition from hyperscalers tightens. The key short term catalyst is whether new AI agents actually deepen consumption of Elastic Cloud and serverless tiers.
The largest near term risk is that elevated expectations around AI products meet slower real world adoption, which could weigh on revenue momentum and profitability that analysts already expect to soften. Nightshift AI SRE and AlertZero look directionally important, but their financial impact is uncertain until customers move beyond free and technical previews.
AlertZero feels especially tied to the existing catalyst around AI led security. It runs across Elastic Security data, works with different model choices and is designed to compress a large alert queue into a smaller set of actions. For investors, the operational question is whether this agentic layer convinces security teams to consolidate more spend on Elastic.
If AlertZero helps security customers handle false positives and forensic work inside one environment, that could support Elastic winning a larger share of security budgets that are already in motion. The flip side is execution risk. If competitors match similar SOC automation or customers hesitate to trust AI driven workflows, the expected uplift in usage and cross sell could come through more slowly than hoped.
Elastic's current analyst narrative points to revenues of US$2.7b and earnings of US$48.3m by 2029, based on an assumed 14.6% yearly revenue growth rate and a shift from US$375.6m of earnings today to that lower profit figure, which represents a decline of roughly US$327m over the period.
Uncover how Elastic's fair value indicates a 13% potential upside to its current price that could narrow more quickly than many investors expect.
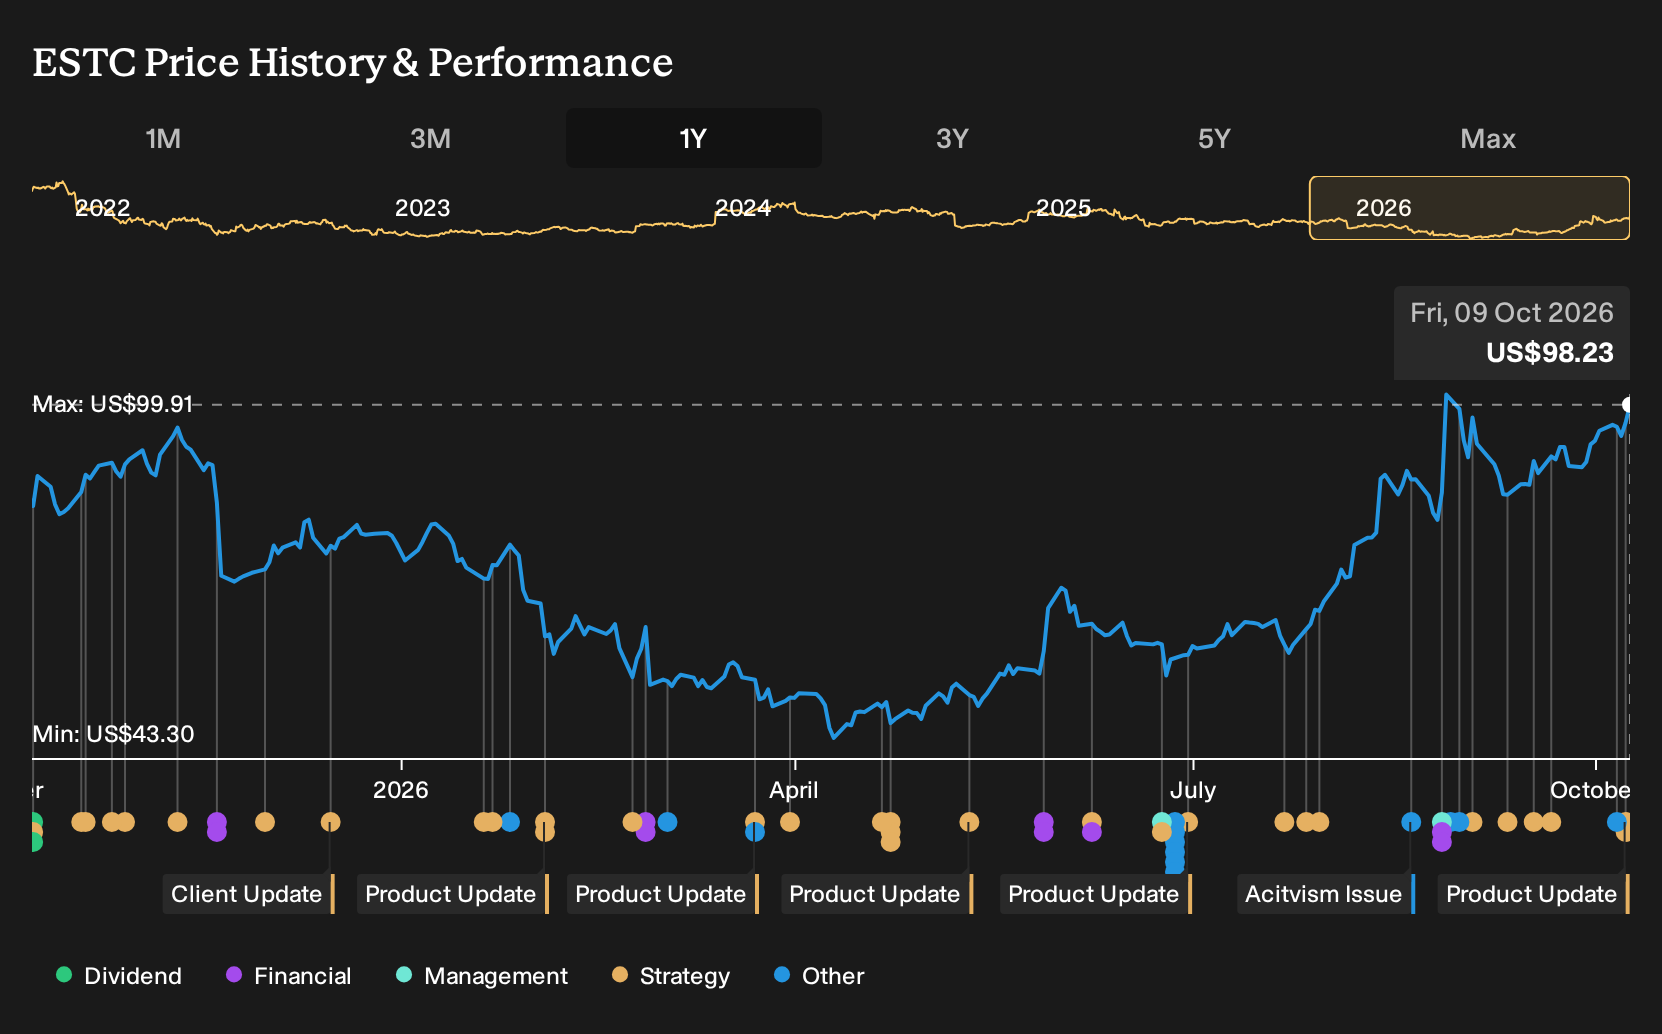
Exploring Other Perspectives
One alternate view puts far more weight on Elastic’s AI agents as a catalyst. The most optimistic analysts were already modeling revenue of about US$2.9b and earnings of US$178.5m by 2029 before this news. You can see how opinions differ widely; therefore, it is worth exploring how these fresh launches might reshape those expectations.
Explore 4 other Elastic fair value estimates, including one that suggests as much as 55% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Elastic research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Elastic. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which can make it easier to evaluate Elastic's overall financial health at a glance.
Looking For More Investment Ideas Beyond Elastic?
Once you have a view on Elastic, it can help to broaden your watchlist with other stocks that fit clear, data backed criteria using the Simply Wall St Screener.
- For investors who care most about quality combined with attractive pricing, scan a curated 29 high quality undervalued stocks that have both solid fundamentals and appealing valuations.
- If capital preservation and steadier return profiles matter more to you than shooting for the highest upside, filter for 31 resilient stocks with low risk scores that score well on financial health and risk metrics.
- When you want to get ahead of the crowd and research less followed opportunities, sort through a 20 high quality undiscovered gems that already show strong underlying business performance.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com