


Does Premium Brand Expansion Change The Bull Case For Heineken Holding (ENXTAM:HEIO)?
- Heineken Holding is in focus as premium labels like Heineken and Amstel gain traction in urban and emerging markets such as APAC and Africa, with investors reassessing how this brand mix and regional exposure affect the brewer's long term earnings power.
- The sharper emphasis on premiumisation, digital tools and new product formats, including 0.0 beer, highlights how Heineken Holding is trying to lift price per hectoliter while managing regulatory and currency pressures in higher risk markets.
- We will now see how Heineken Holding's investment narrative could be affected by optimism around premium brand growth in emerging markets.
Scan how Heineken Holding's premium push compares with other brewers that rely on pricing power and strong balance sheets by reviewing our hand picked 179 high quality undervalued stocks.
Heineken Holding Investment Narrative Recap
To remain invested in Heineken Holding, investors need to believe the push into premium beers and 0.0 formats can keep lifting price per hectoliter, especially in APAC and Africa, without eroding volume or brand appeal. In the short term, a key swing factor is whether that premium mix can meaningfully support earnings while developed markets face softer demand.
The biggest near term risk sits in the same regions driving the story. Currency swings and tighter rules on alcohol in emerging markets could eat into Euro earnings even if local performance looks healthy. The latest news does not radically change this setup, but it does sharpen attention on FX and regulation.
Recent commentary that Heineken Holding could be materially undervalued if premium growth in emerging markets unfolds as expected ties directly into this premiumisation theme. The business is already leaning on Heineken, Amstel and 0.0 products to stretch pricing, supported by digital tools and new formats that aim to deepen relationships with urban consumers.
That valuation angle only matters if the operational catalysts hold up. Execution on premium expansion, disciplined management of higher debt levels and cost pressure in markets like Africa all feed into whether earnings can build from today’s base. With no fresh company announcements on these fronts, the focus stays on day to day delivery against these known risks and opportunities.
Heineken Holding Earnings Assumptions in Context
Analysts frame Heineken Holding's premium story with some clear numbers. Revenue is assumed to grow by 6.0% a year over the next few years as higher priced brands and 0.0 formats take a bigger share of the mix. Profit margins are projected to move from 3.3% today to 10.0% in roughly three years, which would reflect much heavier earnings support from each euro of sales if it plays out as expected.
The earnings bridge is even more striking. Consensus points to profits of €3.4b by 2029, compared with €952.0m today. That is an earnings increase of about €2.4b across the period. For that outcome to line up with current analyst models, Heineken Holding would also need to see its P/E contract from 18.5x today to 10.4x on those 2029 earnings, a level that currently sits below the 18.9x cited for the wider GB beverage peer group.
Heineken Holding's narrative projects €34.2b revenue and €3.4b earnings by 2029. This assumes 6.0% yearly revenue growth and an earnings increase of about €2.4b from €952.0m today.
Those forecasts rely on more than just pricing power. Analysts also build in a gradual reduction in the share count, with outstanding shares expected to edge down by 1.57% per year over the next three years. A lower share base can lift earnings per share even if net profit only tracks the headline forecasts, which helps explain the projected earnings per share figure of €6.73 that sits alongside the €3.4b profit estimate.
Uncover why Heineken Holding's fair value indicates a 71% potential upside to its current price, which could narrow quickly.
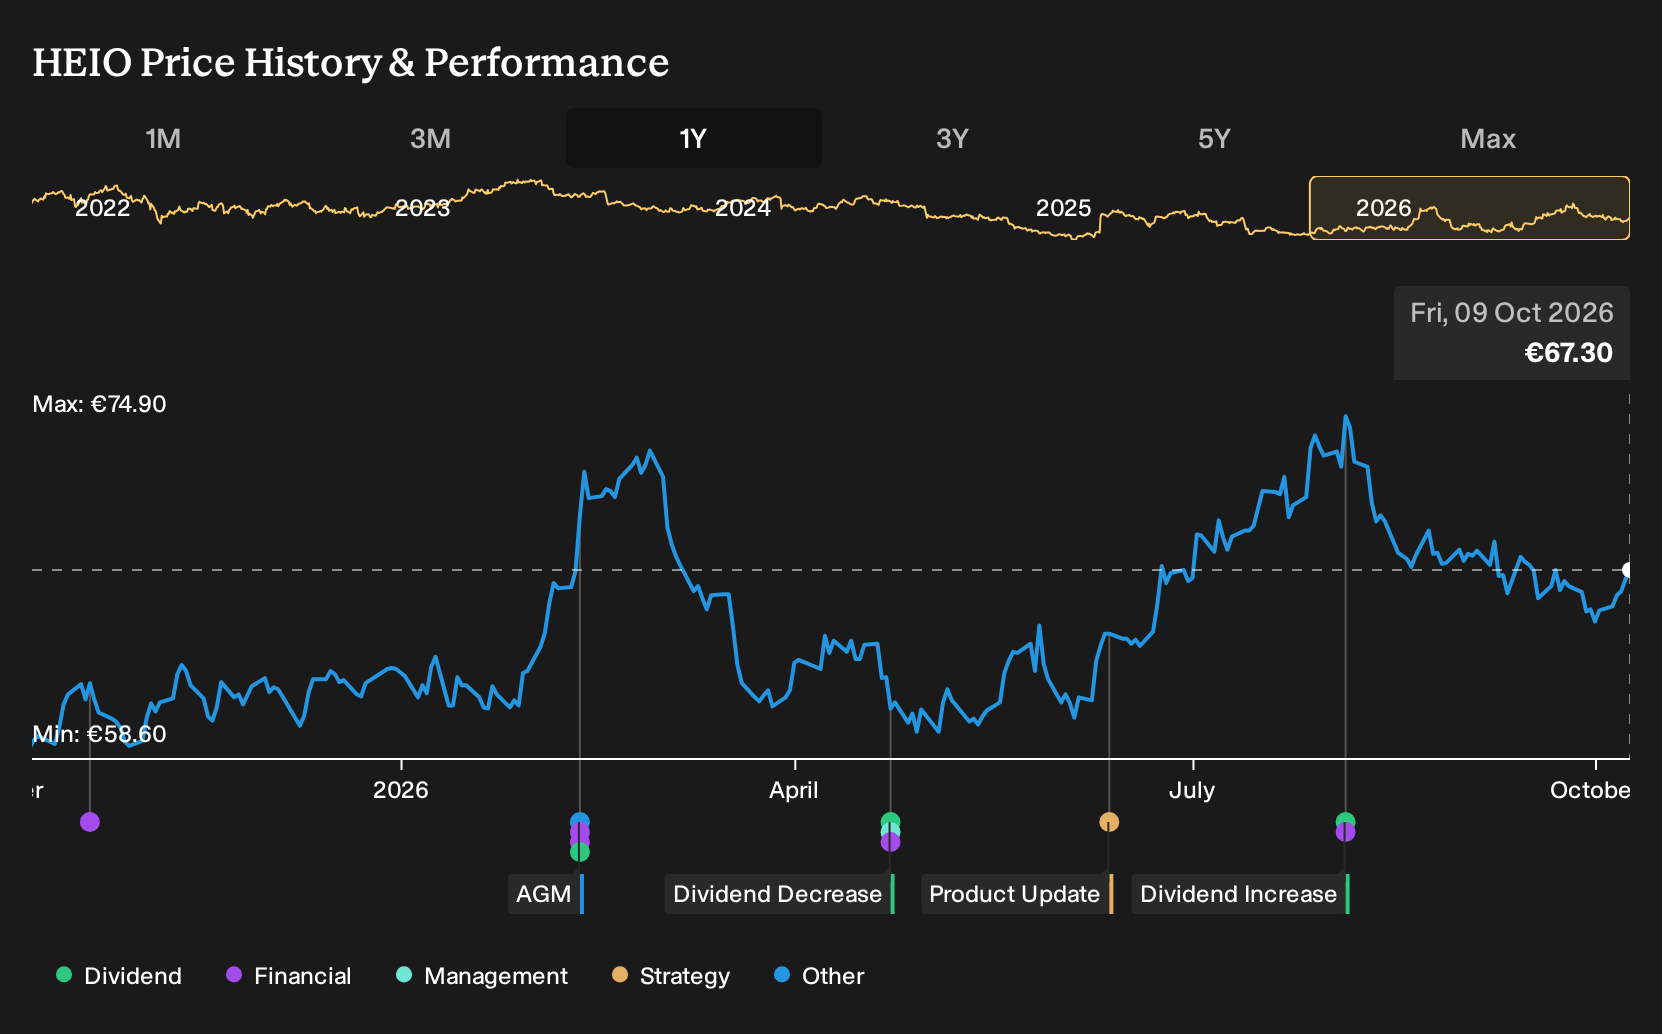
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community span roughly €98 to about €438, so private investors are clearly looking at Heineken Holding through very different lenses. When you set that wide spread against currency and regulatory risks in emerging markets, it becomes a useful reminder to compare several viewpoints before anchoring on any single story.
Explore 2 other Heineken Holding fair value estimates, including one that suggests as much as 551% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own view.
- A great starting point for your Heineken Holding research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Heineken Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Heineken Holding's overall financial health at a glance.
Looking for more investment ideas beyond Heineken Holding?
Once you have formed a view on Heineken Holding, it can help to widen the lens and compare it with other companies that fit different risk, income, and quality profiles using the Simply Wall St Screener.
- For investors who want potential upside but still care about underlying quality, consider scanning a curated set of underpriced opportunities through the 179 high quality undervalued stocks.
- If capital preservation and balance sheet strength matter most to you, start with a list of solid balance sheet and fundamentals (202 results) that already screens for financial resilience.
- Those hunting for ideas that the market may not be paying full attention to yet can review a 618 high quality undiscovered gems that filters for under-followed businesses with solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com