


Affirm Holdings (AFRM) Expands Merchant Reach, Is The Stock Still A Bargain?
Affirm Holdings (AFRM) is back in focus after two fresh merchant partnerships. Antom’s US sellers and Crate & Barrel’s brands are adding Affirm’s pay over time plans at checkout across online and physical stores.
Recent trading suggests momentum is building again. Affirm Holdings has logged a 1-day share price return of 4.60% and a 30-day share price return of 12.96%, while the 3-year total shareholder return is very large and the 5-year total shareholder return remains sharply negative.
Scan for other payment and fintech players riding similar partnership momentum with Affirm Holdings by focusing on the 20 high quality undiscovered gems that screen for strong fundamentals and room to grow.
The recent jump in Affirm Holdings raises a simple tension. Is this just sentiment chasing new partnerships, or does the current share price fairly reflect what this business is already delivering and charging for?
Most Popular Narrative: 19% Undervalued
At a last close of $80.70 versus a narrative fair value of $99.23, the current market tag on Affirm Holdings sits below what the most-followed thesis assumes, which puts real weight on how its merchant reach and product mix evolve from here.
Rapid growth and strong engagement with Affirm Card, an actively invested product moving toward high attach rates and greater offline usage, expands Affirm's addressable market beyond online retail, diversifies revenue streams, and drives higher frequency of transactions, which should accelerate GMV and contribute to margin improvement.
See why 52 investors see Affirm Holdings as 19% undervalued.
Result: Fair Value of $99.23 (UNDERVALUED)
Still, the bullish Affirm Holdings story can break if a key merchant departs, or if rising competition and lower-yielding products squeeze profitability harder than expected.
Find out about the key risks to this Affirm Holdings narrative.
Another View: DCF Puts Affirm Holdings In A Different Light
The narrative fair value for Affirm Holdings at $99.23 points to upside from the recent $80.70 share price. A different lens tells a cooler story. The SWS DCF model estimates future cash flows at $62.16 per share, which would frame AFRM as overvalued instead.
This gap between narrative upside and DCF caution leaves a practical question for you as an investor. Which set of assumptions feels closer to how Affirm Holdings will actually convert its current momentum into long term cash generation, and which one you are implicitly backing with your capital?
Look into how the SWS DCF model arrives at its fair value.
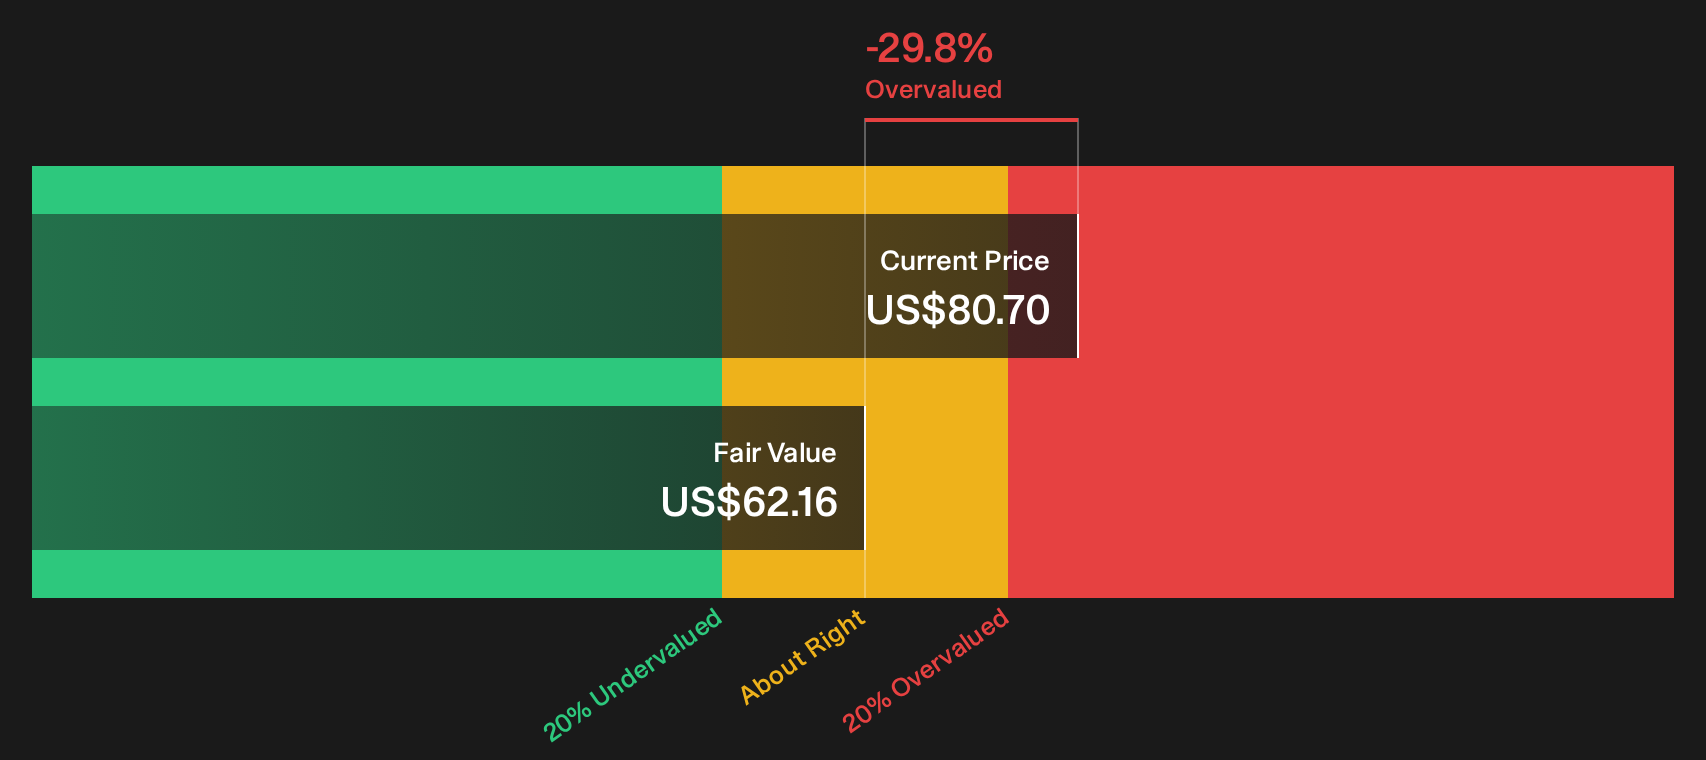
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Affirm Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed feelings on Affirm Holdings after these fresh moves. If you want to act before sentiment shifts again, weigh both sides by starting with the 5 key rewards and 3 important warning signs.
Ready For More Ideas Beyond Affirm Holdings?
If the Affirm Holdings story has sharpened your thinking, do not stop here. Use carefully filtered stock lists to pressure test your next move and avoid guesswork.
- Target stability first by reviewing the 31 resilient stocks with low risk scores to focus on resilience when markets turn choppy.
- Prioritise quality at a fair tag and scan the 29 high quality undervalued stocks for companies combining strong fundamentals with attractive pricing.
- Move early on quality before the crowd by checking the 20 high quality undiscovered gems that highlight financially solid businesses still under the radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com