


Asian Growth Leaders With High Insider Ownership
Amidst a backdrop of global economic uncertainty and market volatility, Asian markets have shown resilience, with technology and energy sectors playing pivotal roles in shaping investor sentiment. In this environment, companies exhibiting strong growth potential coupled with high insider ownership can offer unique insights into confidence levels among those closest to the business.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 74.9% |
| Shanghai Skychem Technology (SHSE:688603) | 31.8% | 67.7% |
| Shanghai Biren Technology (SEHK:6082) | 10.4% | 119.7% |
| Seojin SystemLtd (KOSDAQ:A178320) | 18% | 106.6% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| Great Microwave Technology (SHSE:688270) | 21.1% | 95.2% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 32% |
| Fulin Precision (SZSE:300432) | 10.8% | 66.5% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
Let's dive into some prime choices out of the screener.
Beijing Yunji Technology (SEHK:2670)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Beijing Yunji Technology Co., Ltd. designs, manufactures, and sells commercial service robots in China and internationally, with a market cap of HK$5.12 billion.
Operations: The company's revenue is primarily derived from its AI Digitalization System, generating CN¥90.29 million, and its Robots and Functional Kits segment, contributing CN¥289.39 million.
Insider Ownership: 21.7%
Revenue Growth Forecast: 25.9% p.a.
Beijing Yunji Technology is experiencing robust revenue growth, forecasted at 25.9% annually, outpacing the Hong Kong market. Recent strategic alliances, such as with Mint Incorporation for developing service robots, highlight its innovative edge in AI and robotics. However, despite narrowing net losses to CNY 111 million for H1 2026 and a positive revenue trajectory, profitability remains a future goal. The recent share subdivision aims to enhance liquidity and attract investors amidst high insider ownership dynamics.
- Click here and access our complete growth analysis report to understand the dynamics of Beijing Yunji Technology.
- According our valuation report, there's an indication that Beijing Yunji Technology's share price might be on the expensive side.

COL GroupLtd (SZSE:300364)
Simply Wall St Growth Rating: ★★★★★★
Overview: COL Group Co., Ltd. operates in the digital reading products, publishing, and content value-added services sectors both in China and internationally, with a market capitalization of CN¥17.83 billion.
Operations: The company generates revenue through its digital reading products, publishing operations, and content value-added services both domestically and internationally.
Insider Ownership: 12.2%
Revenue Growth Forecast: 22% p.a.
COL Group Ltd. is poised for significant growth, with earnings projected to grow 113.63% annually and revenue expected to increase by 22% per year, surpassing the CN market average. Despite a volatile share price recently, its forecasted high return on equity of 40.1% in three years underscores potential profitability. Recent financial maneuvers include a private placement aiming to raise up to CNY 2.83 billion, reflecting strategic capital management amidst high insider ownership levels.
- Unlock comprehensive insights into our analysis of COL GroupLtd stock in this growth report.
- Our valuation report here indicates COL GroupLtd may be overvalued.

Lasertec (TSE:6920)
Simply Wall St Growth Rating: ★★★★☆☆
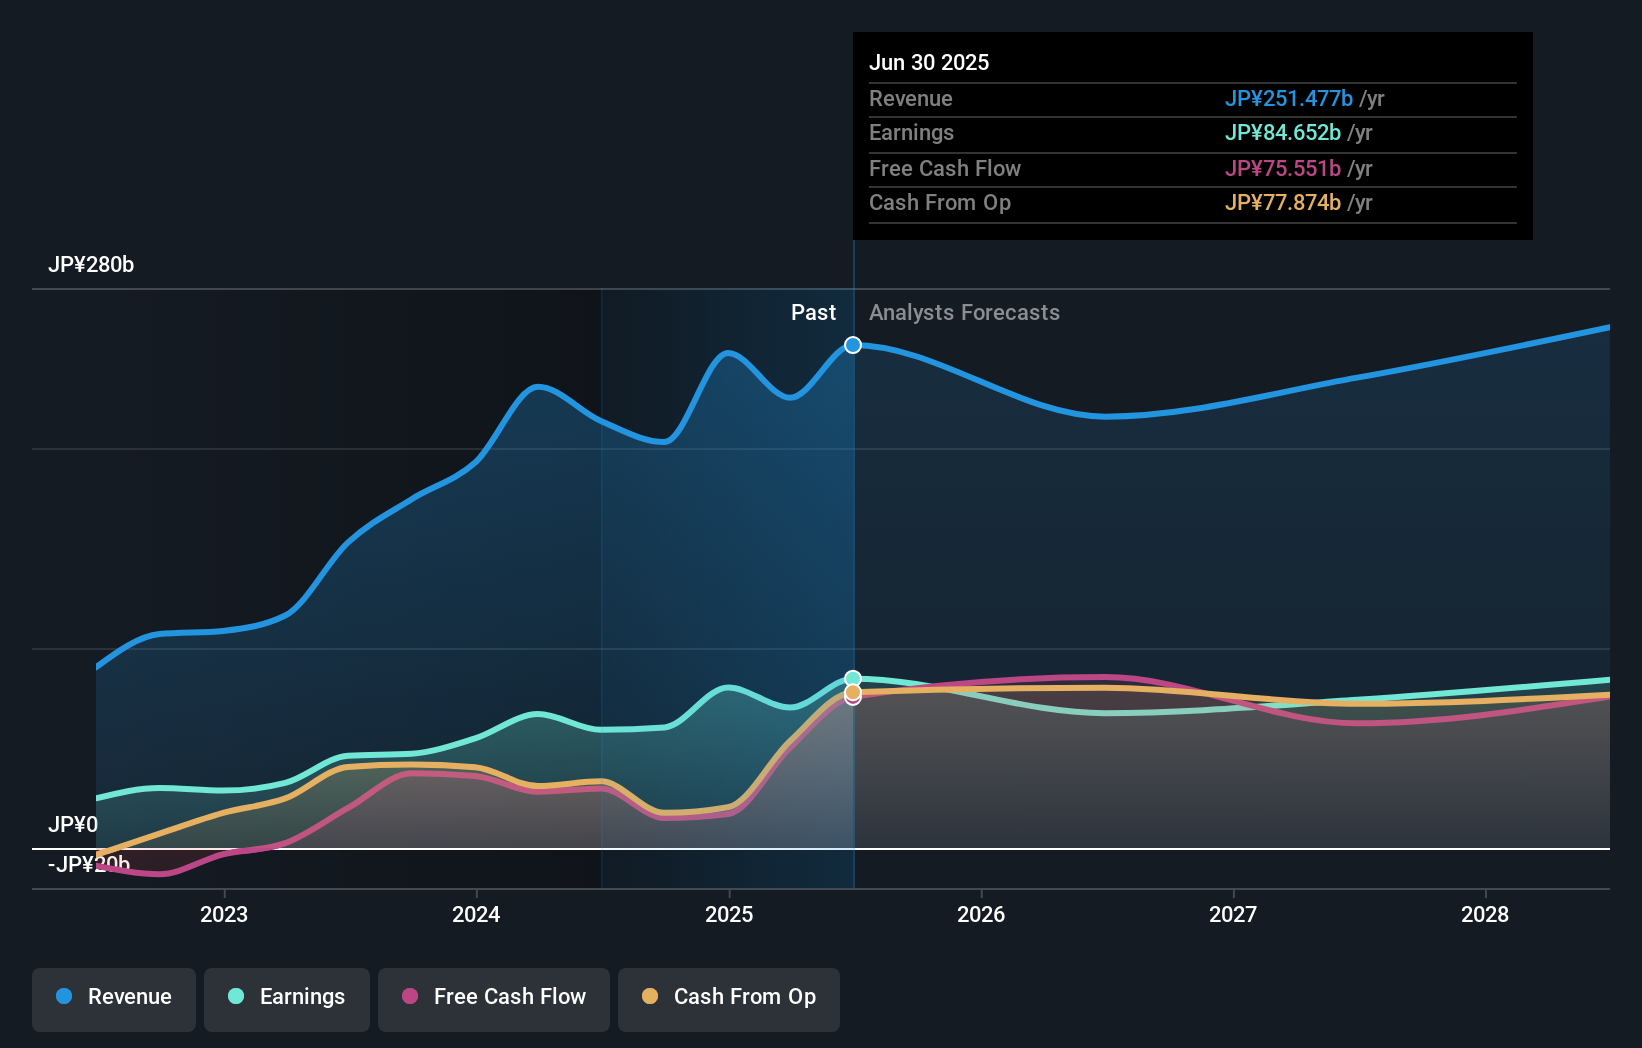
Overview: Lasertec Corporation designs, manufactures, and sells inspection and measurement equipment across various regions including Japan, South Korea, Taiwan, other parts of Asia, the United States, and Europe with a market cap of ¥4.36 trillion.
Operations: The company's revenue from the design, manufacture, and sale of inspection and measurement equipment is ¥230.49 billion.
Insider Ownership: 11.1%
Revenue Growth Forecast: 17.9% p.a.
Lasertec's earnings are projected to grow at 19.1% annually, outpacing the JP market's average, while revenue is expected to rise by 17.9% per year. Despite recent share price volatility and a slight decrease in annual net income and dividends, Lasertec maintains a strong return on equity forecast of 33.9%. The company has set ambitious financial targets for the upcoming fiscal year, with expected net sales of ¥290 billion and operating income of ¥125 billion.
- Delve into the full analysis future growth report here for a deeper understanding of Lasertec.
- Insights from our recent valuation report point to the potential overvaluation of Lasertec shares in the market.
Taking Advantage
- Get an in-depth perspective on all 498 Fast Growing Asian Companies With High Insider Ownership by using our screener here.
- Want To Explore Some Alternatives? Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com