


Should Fiber Supply Deal Require Action From Corning (GLW) Investors?
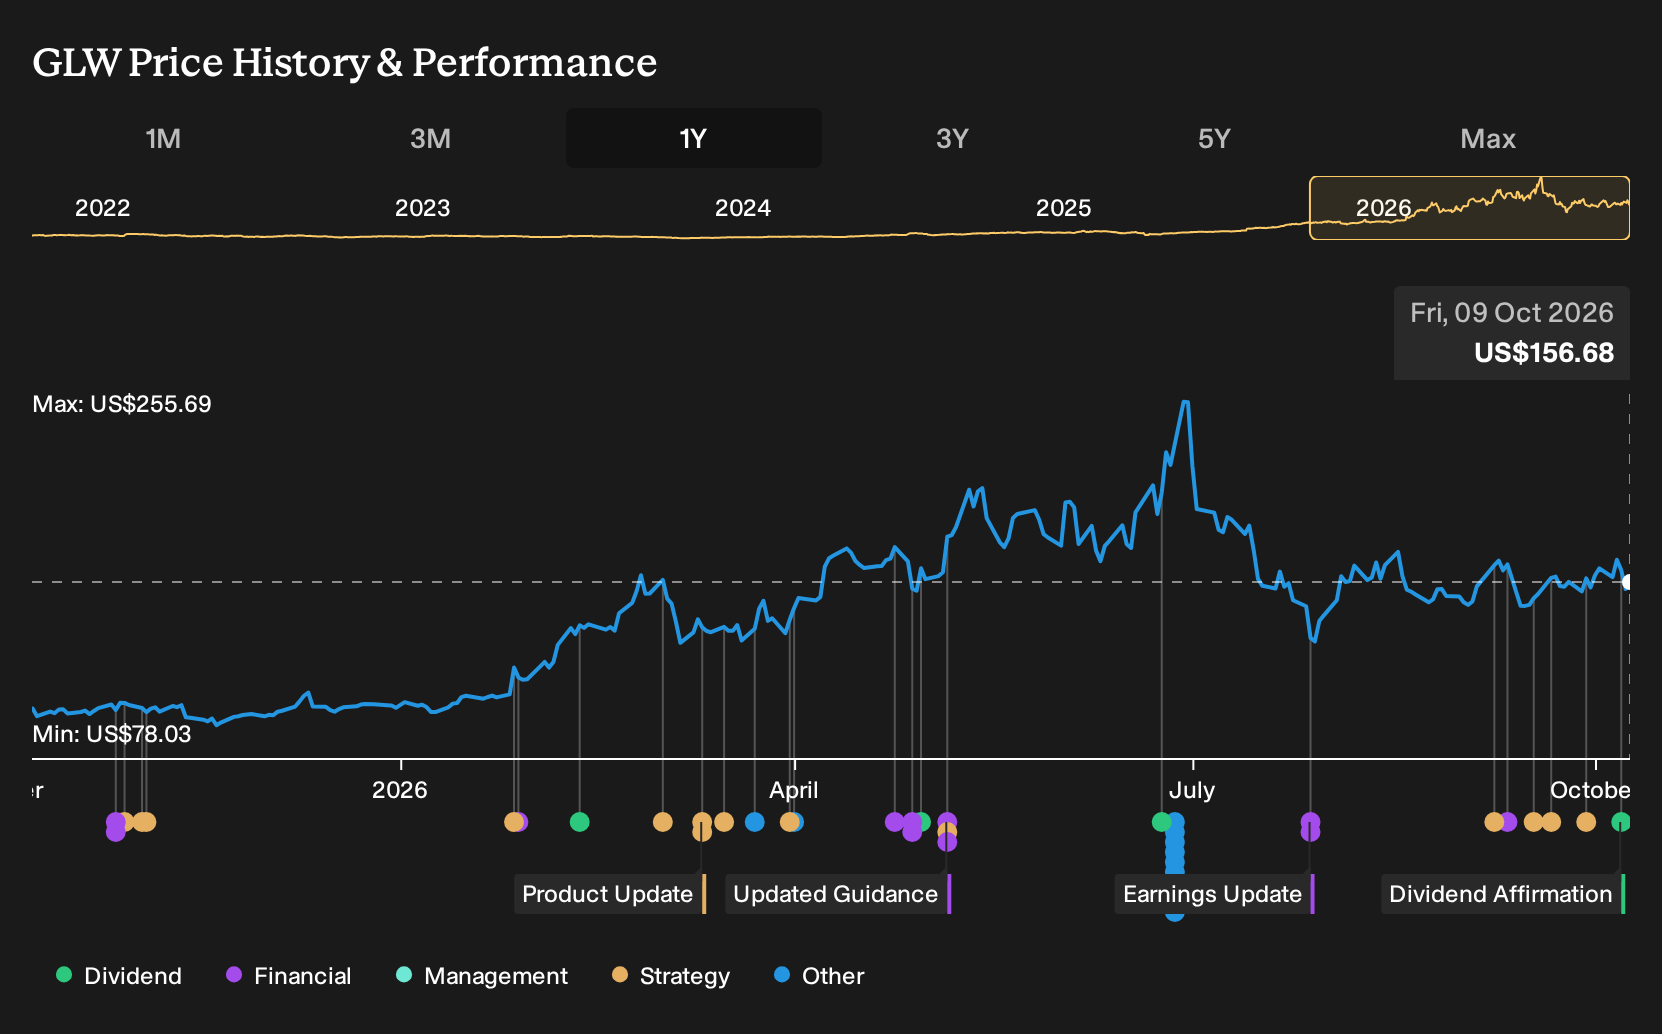
- Corning’s board declared a quarterly dividend of $0.28 per share on October 6, 2026, payable on December 11 to investors of record on November 13. AT&T also announced a multi year fiber and cable supply deal valued at more than $3 billion with Corning to support its U.S. network expansion.
- The AT&T agreement gives Corning clearer multi year demand for U.S. made optical fiber, which can support planning for factory utilization, cost management, and execution of its broader connectivity ambitions.
- We will examine how Corning’s investment narrative is influenced by the multi year, $3 billion plus AT&T fiber supply agreement.
Corning Investment Narrative Recap
Owning Corning means believing its Springboard plan can turn long duration fiber, AI infrastructure and solar demand into a larger, higher margin business over time. The AT&T contract supports visibility in optical communications and may help operational planning. The recent dividend affirmation signals management’s intention to keep returning cash, but does not change the core operating story.
The key near term swing factor is still execution on big growth projects while holding margins and returns, especially with a high debt load and active equity funding in the background. The biggest risk remains operational missteps in newer areas like solar that could drag on group profitability and challenge Springboard goals.
The multi year, 3b plus AT&T fiber agreement looks most relevant for Corning right now. It ties directly into AI driven data demand, where higher optical content per GPU is an important tailwind. Locked in volume from a large carrier can support factory utilization, cost absorption and the practical side of hitting the Springboard revenue milestones.
That said, a large contract does not remove execution risk. Corning still has to deliver on time, maintain product quality and manage capital spending, all while funding other projects and handling a high P/E multiple. For you as an investor, the AT&T deal is best viewed as incremental support for the existing catalyst stack rather than a reset of the risk profile.
Corning assumptions behind the AI and fiber story
Corning's narrative projects revenues of $29.4 billion and earnings of $5.7 billion by 2029. Analysts are baking in 20.1% yearly revenue growth and an earnings increase of about 3x from $1.9 billion today to reach that profit level.
Uncover how Corning's fair value indicates a 21% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the lowest Corning analysts focus on dilution risk from the US$2b at the market program. They saw 2029 earnings closer to US$4.9b on US$29.4b of revenue, which is well below the consensus profit view. Those forecasts pre date the AT&T deal and dividend decision, so opinions may shift.
Explore 7 other Corning fair value estimates, including one that suggests as much as 15% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Corning research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Corning. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Corning's overall financial health at a glance.
Looking for more investment ideas beyond Corning?
If the Corning story has sharpened your thinking about themes like fiber, AI infrastructure and cash returns, it can help to line that up against other opportunities using a structured stock search. The Simply Wall St Screener lets you quickly sort companies by quality, valuation and balance sheet strength so you can compare Corning with peers or build a watchlist tailored to your own approach.
- If you put stability and downside protection first, start with a group of 31 resilient stocks with low risk scores that score well on resilience and financial risk metrics.
- If valuation discipline is non negotiable for you, scan through a curated set of 29 high quality undervalued stocks that combine quality fundamentals with pricing that may look appealing on the numbers.
- If you prefer backing strong business models before the crowd pays attention, focus on a hand picked 20 high quality undiscovered gems that already show solid underlying performance.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com