


Will Client Win Change ACI Worldwide Stock Narrative
- ACI Worldwide reported that the Federal Home Loan Bank of Cincinnati selected its ACI Connetic platform, delivered as a managed service, to run payment processing behind member funding services with Fedwire Funds connectivity.
- The separate BASE24-eps performance test on AWS, run by Cognizant on an ACI operated account, highlighted that ACI’s core payments software can sustain high simulated transaction loads without recorded failures in a cloud setting.
- We will now look at how ACI Worldwide's investment narrative could be influenced by FHLB Cincinnati adopting the Connetic platform.
ACI Worldwide Investment Narrative Recap
To own ACI Worldwide, you need to believe the shift to cloud based, high volume payment infrastructure will keep drawing banks, merchants and billers onto its platforms. The FHLB Cincinnati Connetic win supports that belief operationally, but it does not radically change the near term picture on its own. Execution on the broader Connetic and Speedpay One pipeline still matters most.
The biggest near term swing factor is whether ACI Worldwide converts strong pipelines into recurring software and services revenue, while keeping Biller margins from getting knocked around by one off items. Debt levels and reliance on higher risk funding remain key watchpoints, especially if competition in core payments and newer digital rails pressures pricing.
The BASE24 EPS performance test on AWS is the announcement that most directly frames this Connetic news. It shows ACI software running card transactions at more than double a target load in a managed cloud setup, with no failed transactions in the simulated run and real time observability for operations teams.
In terms of catalysts, that kind of cloud performance story matters if you think banks and payment processors will keep consolidating traffic onto third party platforms rather than building everything in house. It reinforces ACI Worldwide's pitch around high throughput, cloud managed payments, but still leaves the familiar execution risks on go to market, production readiness, certification and competition from both incumbents and fintechs.
ACI Worldwide's current analyst script points to revenues of US$2.3b and earnings of US$373.2m by 2029, built on an assumed 8.1% yearly top line growth rate and an earnings increase of about US$147.5m from US$225.7m today.
Discover how ACI Worldwide's fair value signals a 32% potential upside relative to its current price before the market closes that gap.
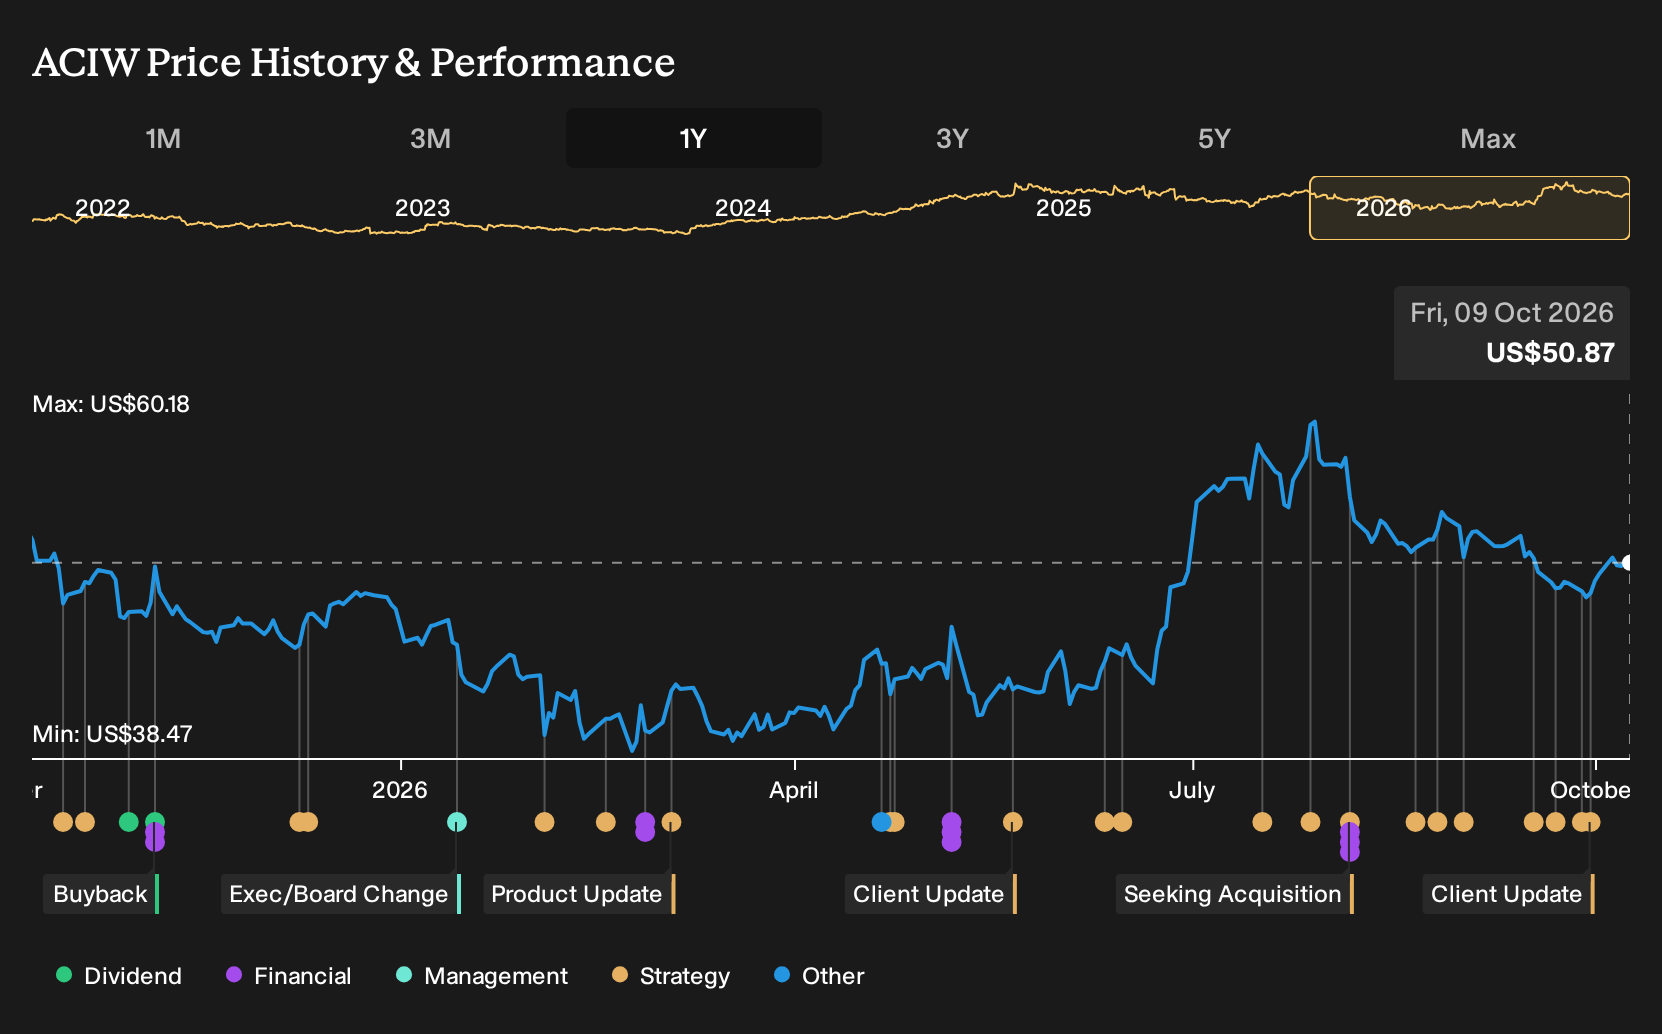
Exploring Other Perspectives
You might see this ACI Worldwide news very differently if you worry about real time payments momentum stalling. The most cautious analysts were already penciling in 8.4% annual revenue growth and about US$370.1m in earnings by 2029, only slightly below consensus. That more restrained story could shift if Connetic’s new visibility changes expectations.
Explore 4 other ACI Worldwide fair value estimates, including one that indicates as much as 12% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ACI Worldwide research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ACI Worldwide. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ACI Worldwide's overall financial health at a glance.
Looking For More Investment Ideas Beyond ACI Worldwide?
If this ACI Worldwide story has you thinking about where else real time payments, resilient infrastructure and cleaner balance sheets might matter, the Simply Wall St Screener can help you line up fresh candidates in a few clicks.
- For investors hunting for quality at a discount, start with a curated set of 29 high quality undervalued stocks that pair financial strength with pricing that may look attractive on the numbers.
- If capital preservation sits high on your list, narrow the field to 31 resilient stocks with low risk scores where balance sheets and risk scores aim to keep unwelcome surprises in check.
- When you want resilience and fundamentals in one place, focus on a list of solid balance sheet and fundamentals (25 results) that filters for robust finances before you even open a single company report.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com