


Is United Therapeutics (UTHR) Below Fair Value After Its Patent Win?
United Therapeutics has delivered a powerful run over the last few years, and recent legal success has kept the story in focus. With the share price now reflecting that track record, the open question is whether the current valuation is adequately grounded in the company’s earnings.
- Over the past 5 years the stock has returned 193.6%, which puts real pressure on today’s price to be supported by the underlying profit stream.
- United Therapeutics’ recent patent win against Liquidia can help defend its inhaled treprostinil franchise, which may support expectations for earnings durability tied to pulmonary hypertension treatments.
- The analysts covering United Therapeutics have run their own numbers. See what analysts think United Therapeutics's shares could be worth.
The issue now is whether United Therapeutics’ current share price is justified by the earnings that investors are effectively paying for today.
If this kind of earnings driven story around United Therapeutics interests you, a focused stock screen built on similar fundamentals is a useful next step. You can start with 29 high quality undervalued stocks.
Is United Therapeutics Still Cheap on Earnings?
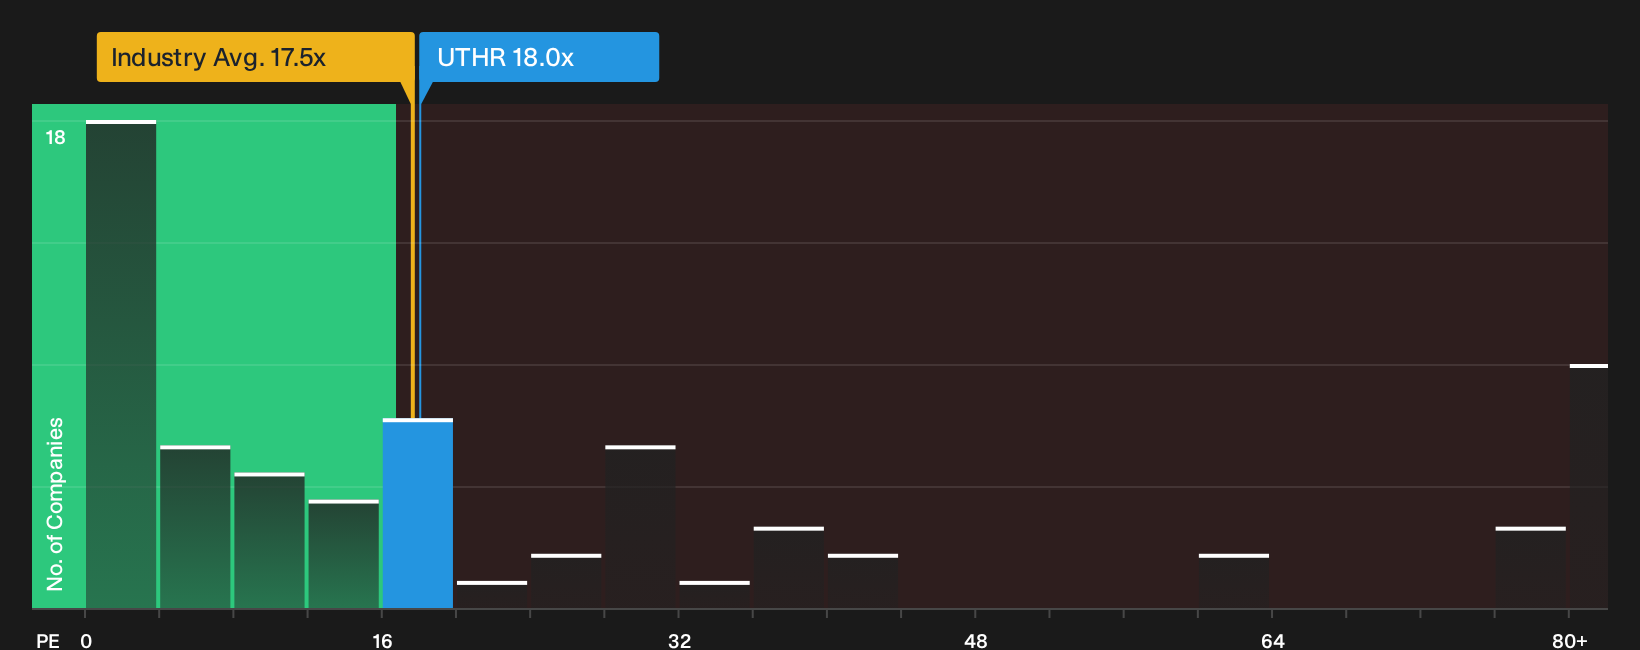
P/E fits United Therapeutics because profit is a key focus for investors in established biopharma businesses rather than early stage pipelines. On this yardstick, the stock trades on a P/E of 18.0x, compared with about 17.5x for the wider Biotechs group and roughly 23.0x for direct peers. That puts United Therapeutics at a premium to the broader industry but at a discount to companies investors tend to cluster it with.
Based on a tailored fair P/E that reflects United Therapeutics’ own mix of growth, margins, size and risk, the current 18.0x points to the shares being undervalued on this model. Because the company recently prevailed in patent litigation around inhaled treprostinil, the multiple suggests the market is not fully pricing in the earnings power implied by that IP protection. For readers comparing options in the sector, the gap between today’s P/E and the modelled fair level is the key figure to weigh next. Explore the numbers behind United Therapeutics's P/E valuation.
The United Therapeutics Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the United Therapeutics valuation puzzle leaves off by spelling out which paths for growth, profitability and earnings would need to play out for the stock to look meaningfully cheaper or more expensive than it does today on the Community page. Each scenario ties its number to a clear view on how United Therapeutics' growth, margins and risk profile might shift over time, giving you a reference point you can revisit as new information arrives.
Community views on United Therapeutics split between those who see protected pulmonary and organ platforms as underappreciated and those who think execution risks still weigh too heavily.
Bull case: 14% undervalued
"The company's innovation wave pipeline, including studies in progressive fibrosis, next-generation delivery platforms, and organ manufacturing, positions United Therapeutics to benefit from the expanding focus on personalized and regenerative medicine…"
Discover why this Narrative puts United Therapeutics at 14% undervalued.
Bear case: 27% overvalued
"Despite a sequenced delivery platform strategy for treprostinil and ralinepag that aims to support revenue into the 2040s, the recent pattern of quarterly and multi year declines in revenue and EPS indicates that newer formulations may at best offset competitive and pricing headwinds rather than expand earnings…"
Explore why this Narrative puts United Therapeutics at 27% overvalued.
For United Therapeutics, the share price is only one piece of the decision
Before making a call on United Therapeutics, it is worth asking who is steering the business, how their rewards line up with your goals, and what that means for discipline on future decisions. See who runs United Therapeutics and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com