


Sakata Seed (TSE:1377), Why Is Its Latest Update Drawing Attention?
Sakata Seed (TSE:1377) has just opened its new financial year with first quarter earnings that combined higher sales with weaker profitability, a mix that gives investors fresh numbers to reassess the stock’s recent share performance.
Recent trading tells a mixed story. The share price has slipped over the past month and quarter, yet the 1 year total shareholder return of 11.9% and 5 year total shareholder return of 30.11% suggest longer term holders in Sakata Seed have still seen momentum build, despite today’s ¥4,210 share price sitting below earlier highs.
Review how Sakata Seed stacks up against other quality growers by scanning the hand picked 74 high quality undiscovered gems that share strong fundamentals and under the radar momentum profiles.
With Sakata Seed’s share price easing while the latest quarter pairs higher sales with thinner earnings, the real tension is simple. Is this a reasonable entry now, or does patience for a cheaper valuation make more sense?
Preferred Price-to-Earnings of 16.4x: Is it justified?
On current numbers, Sakata Seed trades on a P/E of 16.4x, which leaves the ¥4,210 share price looking a little full when set against peers, even if it still screens as decent value versus an estimated fair P/E of 17.3x.
The P/E ratio compares what investors are paying today for each ¥ of earnings. For a seed and horticulture specialist like Sakata Seed, this typically reflects how confident the market is in the durability of profit streams from its seed genetics, global customer base, and related services.
Recent data points pull in different directions. The stock is flagged as expensive versus both peer averages of 14.8x and the JP Food industry at 16.3x, which hints that buyers are already paying a premium for expected earnings. At the same time, the SWS fair ratio work suggests a 17.3x level could be a more grounded anchor, a figure the market may gravitate toward if earnings forecasts of 5.73% per year hold and high quality earnings continue.
That premium needs context against softer fundamentals in some areas. Earnings declined 11.9% over the past year and current net profit margins of 10.2% are below last year’s 12.9%. Forecasts point to revenue growth of 4.3% per year and earnings growth that is slower than both the wider JP market and the JP Food sector. Taken together, the present multiple looks slightly stretched compared to peers, yet not extreme when lined up with the fair ratio estimate of 17.3x that the market could move toward if execution remains consistent.
Explore the SWS fair ratio for Sakata Seed.
Result: Price-to-Earnings of 16.4x (OVERVALUED)
Still, softer profit momentum and earnings growth that trails both the wider JP market and the JP Food sector could quickly challenge the current valuation story.
Find out about the key risks to this Sakata Seed narrative.
Another view on Sakata Seed’s value
The P/E work paints Sakata Seed as a little rich, yet the SWS DCF model sends a different signal. On that framework, the shares at ¥4,210 trade below an estimated future cash flow value of ¥5,706.68, which frames the stock as undervalued. So which lens deserves more weight in your process?
Look into how the SWS DCF model arrives at its fair value.
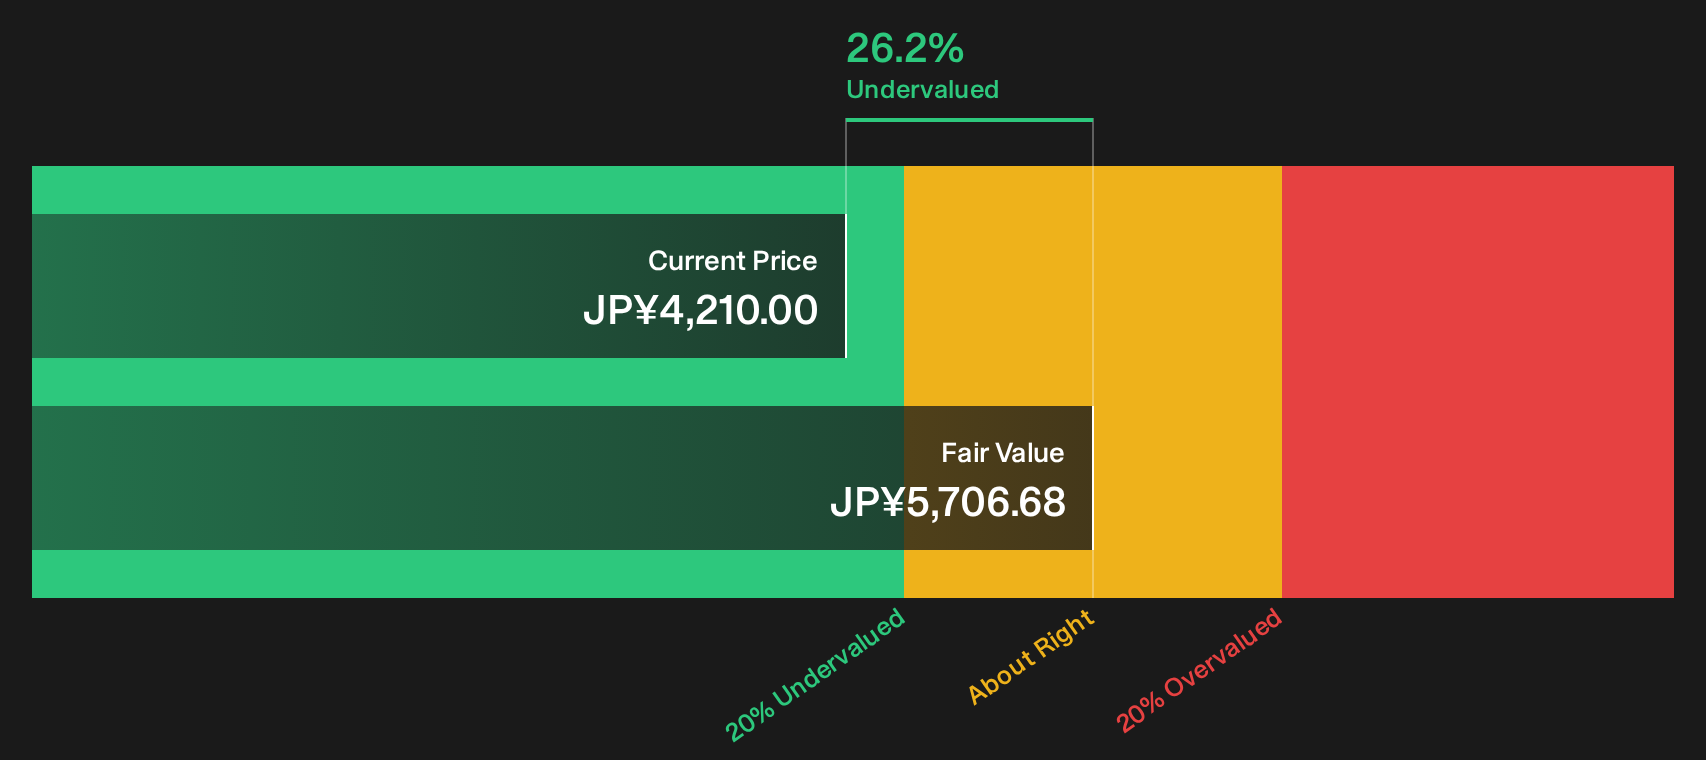
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sakata Seed for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of stronger sales, thinner margins and a split valuation picture leaves you undecided, treat it as a prompt to dig into the data yourself and move quickly while sentiment is still forming around Sakata Seed. Then weigh up the 2 key rewards and 1 important warning sign
Looking for more ideas beyond Sakata Seed?
Do not stop with a single ticker. Put these tools to work and line up a fuller watchlist while the market is still offering mispriced opportunities.
- Target stronger upside potential by scanning a focused pool of quality value candidates through the 13 high quality undervalued stocks.
- Prioritise resilience by filtering companies with robust finances using the list of solid balance sheet and fundamentals (22 results).
- Lock in cash return ideas by tracking reliable income opportunities screened through the 28 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com