


How Investors May Respond To OSI Systems (OSIS) New Contract Wins
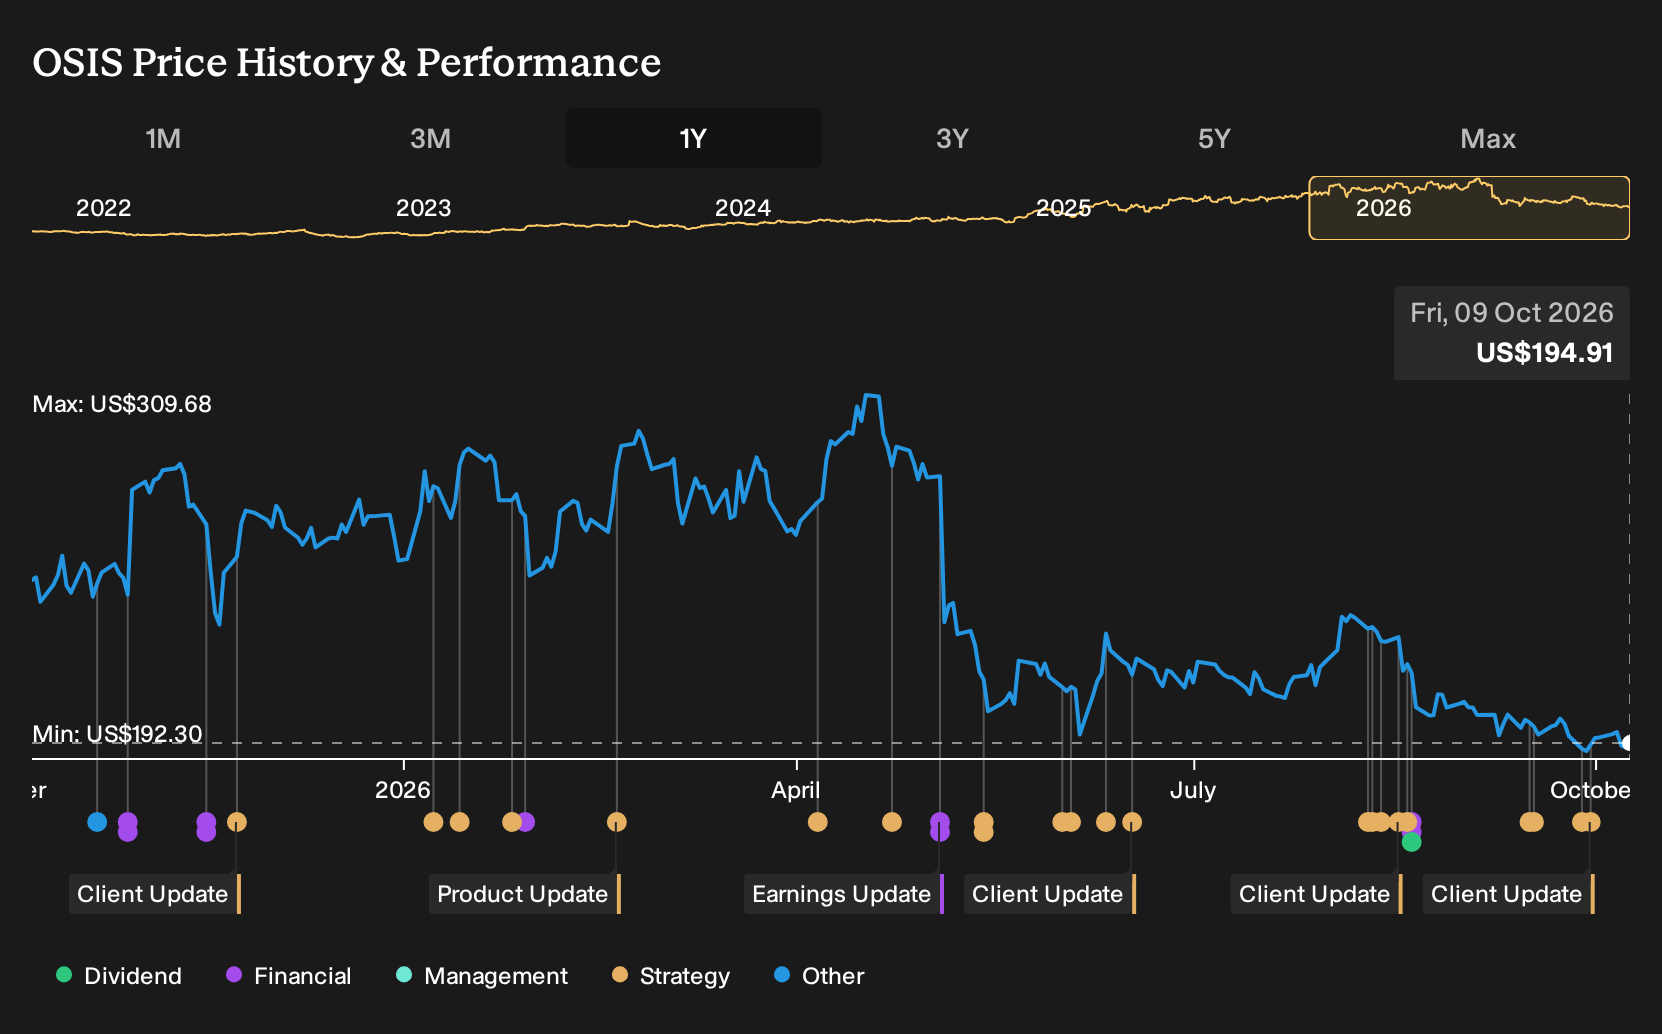
- OSI Systems reported new orders of about US$23 million for Security division cargo inspection support work and roughly US$7 million for Optoelectronics industrial control sub assemblies, signaling fresh demand across two of its key operating segments.
- The simultaneous flow of Security and Optoelectronics contracts underscores how OSI Systems is tying equipment sales to follow on service and component work that can support utilization of its existing manufacturing and service infrastructure.
- We now examine how OSI Systems' new US$23 million in Security service orders may influence its broader investment narrative for investors.
OSI Systems Investment Narrative Recap
To own OSI Systems, you need to believe the backlog and recurring service work can offset pockets of pressure in Security and any future contract gaps. The key near term swing factor is how quickly delayed Security revenue tied to regions like Mexico and the Middle East converts into delivered projects and service income that support margins.
The biggest risk remains softer Security activity or further shipment delays that pull group revenue and earnings below guidance. The fresh Security and Optoelectronics orders add incremental visibility, but they do not fundamentally change the near term risk that a guidance reset or slower backlog conversion could weigh on sentiment.
The US$23 million Security division order for civil works, service, and cargo inspection support appears particularly relevant for OSI Systems at this stage. It reinforces the view that higher margin services on installed equipment can matter almost as much as new system wins, especially when headline Security revenue has already moved lower year over year.
This contract also sits alongside expectations for strong service revenue growth from a US$441 million service base in fiscal 2026, so execution on this type of work becomes a practical test of that goal. Any operational slip, whether cost overrun, delivery delay, or customer pushback, would feed directly into the main catalyst and the main risk investors are watching.
OSI Systems' current analyst narrative points to revenues of US$2.2b and earnings of US$229.2 million by 2029, based on 6.9% yearly revenue growth and an increase in profit from US$154.7 million today, which implies an earnings increase of roughly US$74.5 million over that period.
Uncover why OSI Systems' fair value indicates a 43% potential upside to its current price, before that discount to OSI Systems' forecasted value narrows.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$79 to US$278 per share, so opinion on OSI Systems is wide. Some community members focus on the stock trading below sector P/E averages; others flag risks like softer Security revenue or Middle East delivery delays. Treat these as starting points and compare several viewpoints before updating your own stance.
Explore 2 other OSI Systems fair value estimates, including one that suggests as much as 43% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own perspective.
- A great starting point for your OSI Systems research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for OSI Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate OSI Systems' overall financial health at a glance.
Looking For More Ideas Beyond OSI Systems?
If you want to stress test your thesis on OSI Systems and broaden your watchlist, the Simply Wall St screener can surface other businesses with the kind of financial traits you value most.
- Prefer companies with resilient balance sheets and fundamentals that can handle bumps in the cycle? Scan our list of solid balance sheet and fundamentals (25 results) and compare them side by side with OSI Systems.
- Interested in opportunities where price and quality might not fully line up yet? Review our 20 high quality undiscovered gems to spot businesses that the wider market may not be focused on.
- More cautious on risk and looking to smooth out portfolio swings? Filter for companies in the 31 resilient stocks with low risk scores and see how they stack up on stability metrics you care about.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com