


MDA Space (TSX:MDA) Climbed, But Why Is Attention Shifting Now?
Execution risks put MDA Space under closer scrutiny
Investor attention on MDA Space (TSX:MDA) has sharpened after sentiment weakened around execution risks on complex space infrastructure and satellite projects, with geopolitical and market uncertainty feeding into active, sometimes volatile, trading.
Recent trading tells a mixed story. The 1-day share price return of 3.53% and year-to-date share price return of 45.42% point to strong upward momentum. However, the 90-day share price return declined 10.07% as investors reacted to execution risk headlines and reassessed MDA Space against its longer term total shareholder returns of 11.43% over 1 year and more than tripling over 3 years.
Scan beyond MDA Space and size up other contractors wrestling with complex programs by reviewing the hand picked 7 resilient stocks with low risk scores, which balance resilience with disciplined execution risk.
The question now is simple. After a 45.42% year to date jump in MDA Space, do the current valuation markers still signal meaningful upside, or has most of the easy gain already played out?
Most Popular Narrative: 40% Undervalued
MDA Space closed at CA$40.18, while the most followed valuation storyline anchors fair value at CA$67.27. This creates a wide gap that investors are now weighing against execution and contract risks.
The ramp-up of large LEO constellation contracts, including the landmark $1.8 billion EchoStar direct-to-device satellite order with options to expand, and multiple pipeline opportunities in broadband, defense, and IoT, is expected to drive robust multi-year revenue growth as global demand for satellite connectivity accelerates.
Expansion of MDA's Montreal facility will enable high-volume digital satellite production (targeting up to 2 satellites a day by late 2025 and scalable further). This is positioning the company to capitalize on rising market demand and to increase operating leverage, supporting higher EBITDA margins over time.
See why 80 investors see MDA Space as 40% undervalued.
Result: Fair Value of CA$67.27 (UNDERVALUED)
Still, the bullish MDA Space narrative can be knocked off course if big-ticket contracts face delays or cost overruns, or if heavy capital spending squeezes near term profitability.
Find out about the key risks to this MDA Space narrative.
Another View: What MDA Space’s P/E Is Telling You
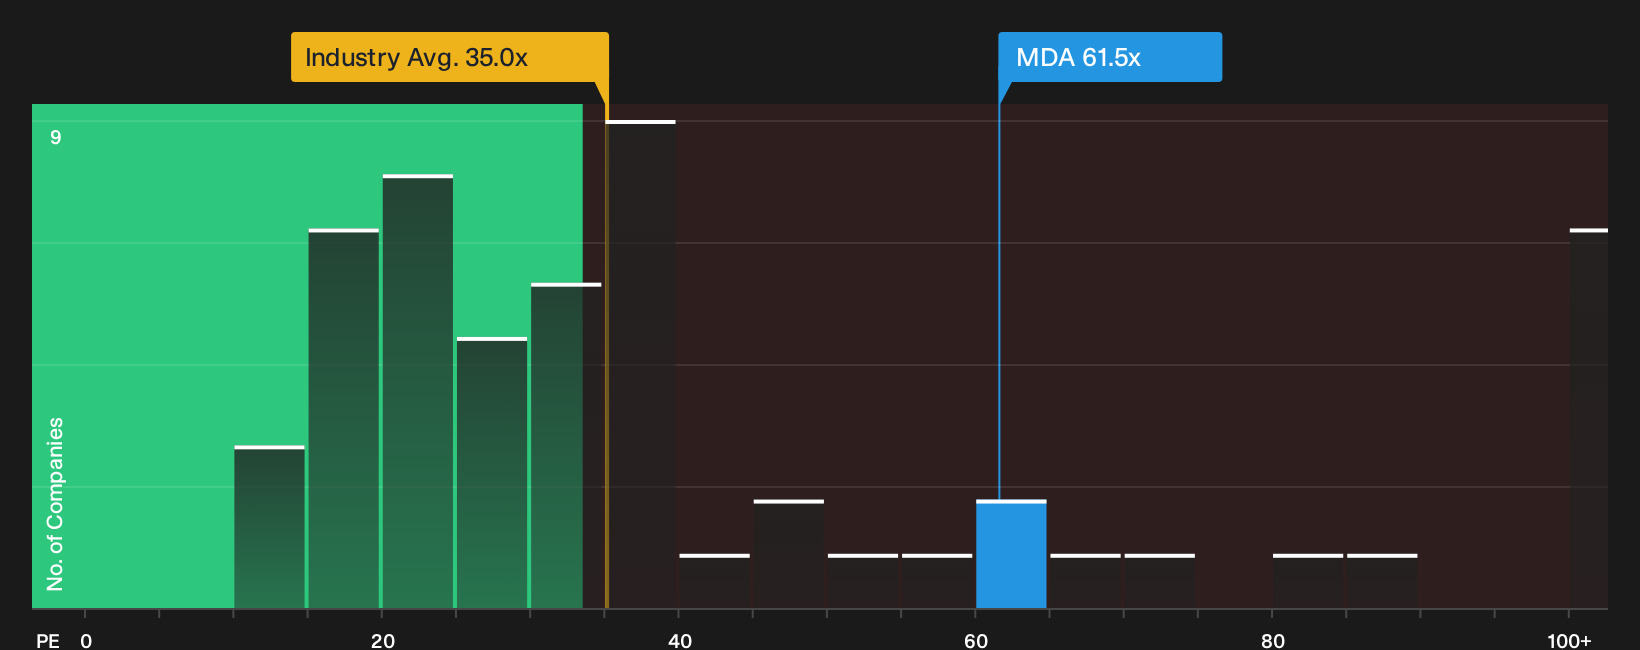
The first story around MDA Space leans on a fair value of CA$67.27 and a 40.3% discount. A second lens tells something different. At a P/E of 61.5x versus a fair ratio of 56.7x, the stock looks expensive, not cheap.
This ratio also sits well above the North American Aerospace & Defense average of 35x and the 28.4x peer mean. In plain terms, the current tag already bakes in a lot of optimism, so unexpected contract hiccups or margin pressure could hurt more than they help. Which version of “value” do you trust when expectations are this high?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the split between optimism and caution around MDA Space feels sharp, move quickly to review the underlying metrics and weigh both sides of the story with the full breakdown of 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond MDA Space?
Do not park all your attention on a single ticker. Use the Simply Wall Street Screener to surface fresh ideas that fit your risk and return preferences.
- Hunt for mispriced quality by reviewing the 8 high quality undervalued stocks that combine solid fundamentals with room for a potential rerating.
- Strengthen portfolio resilience by scanning the list of solid balance sheet and fundamentals (7 results) and focus on businesses with cleaner debt profiles and sturdier financial footing.
- Get ahead of the crowd by checking the 9 high quality undiscovered gems that investors are not widely talking about yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com