


Manulife Financial (TSX:MFC) Could Be 7% Undervalued As ChatGPT Insurance Push Draws Focus
Manulife Financial (TSX:MFC) has been in focus after introducing its CoverMe plugin in ChatGPT, giving Canadian travellers an AI-based way to explore and quote travel insurance directly within the platform.
Recent share price action has been firm, with a year to date share price return of 21.59% and a 1 day move of 1.10% to CA$60.55. Total shareholder return of 41.39% over the past year and more than tripling over three years points to momentum that investors are still pricing in, as the CoverMe plugin launch and the appointment of a new Chief Actuary reshape how the market thinks about Manulife Financial’s growth prospects and risk profile.
Scan beyond Manulife Financial and see how other insurers and financials are leaning into AI led customer tools with the hand picked 39 profitable AI stocks that aren't just burning cash.
After a run this strong and with fresh AI headlines in the mix, does the current Manulife Financial share price still offer a favourable trade off between potential upside and the risk you are taking on at CA$60.55?
Most Popular Narrative: 7% Undervalued
Compared with the current Manulife Financial share price of CA$60.55, the most followed narrative puts fair value at CA$65.40, which implies a modest undervaluation based on its long term earnings power and risk profile.
The earnings mix is continuing to shift toward fee based and protection businesses. Global WAM is already reporting a 31.2% core EBITDA margin, and legacy LTC and VA together contribute comfortably less than 10% of earnings. This can support more capital-light earnings and steadier net income.
See why 140 investors see Manulife Financial as 7% undervalued.
Result: Fair Value of CA$65.40 (UNDERVALUED)
Still, the Manulife Financial story can easily wobble if alternative long duration assets continue to underperform assumptions or if pressure in Canada’s group disability segment persists and drags on profitability.
Find out about the key risks to this Manulife Financial narrative.
Another View: Manulife Financial On Earnings Multiples
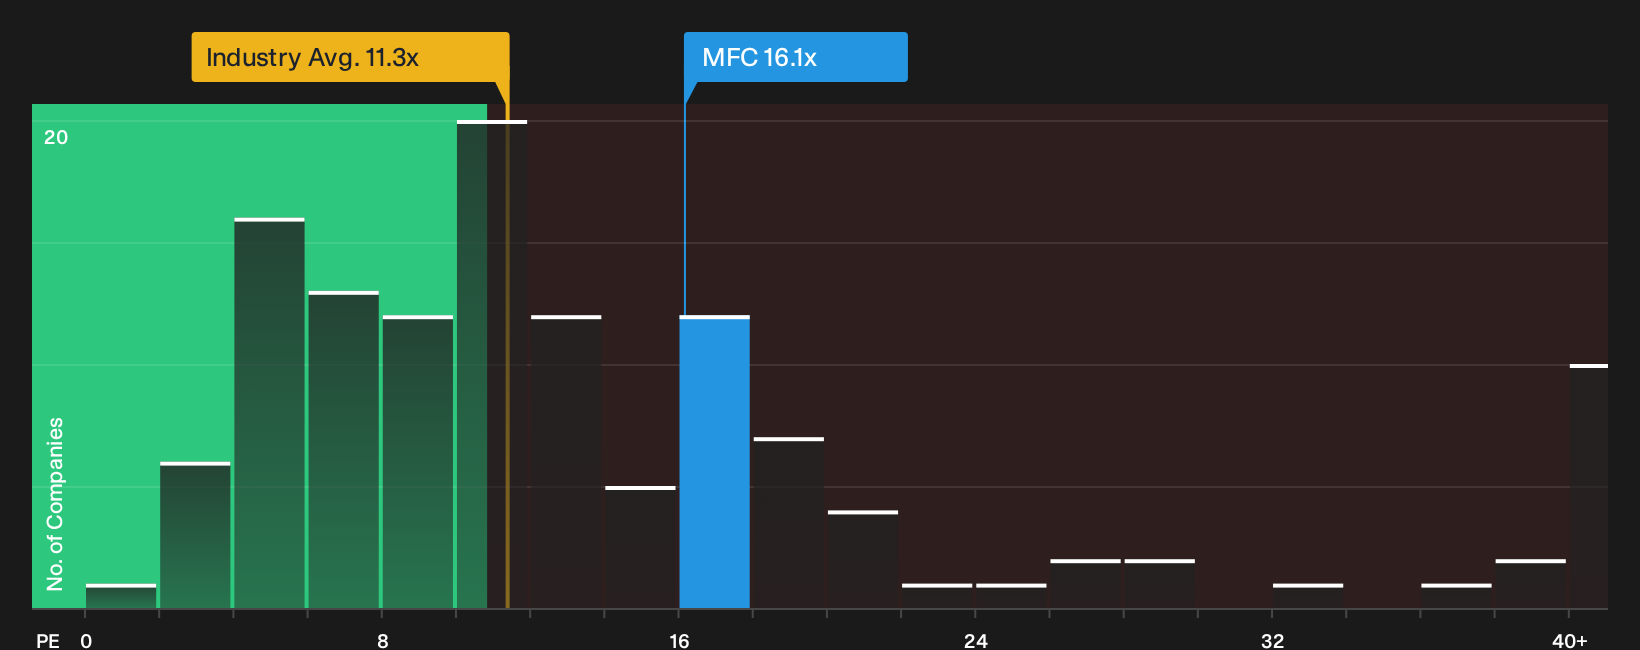
That 7% gap to fair value looks manageable, but the picture shifts when you look at what investors are currently paying for Manulife Financial’s earnings. The stock trades on a P/E of 16.1x, richer than the North American insurance group at 11.3x and above the 15x fair ratio estimated from fundamentals.
Peer companies on average sit nearer 18.6x, so Manulife Financial is not priced at the very top of the pack. However, the premium to the sector and the fair ratio hints at less room for error. If ALDA returns or disability claims surprise you, how comfortable are you paying above that 15x level for this story?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of enthusiasm and caution around Manulife Financial resonates with you, consider acting promptly and pressure test the upside yourself by reviewing the 4 key rewards.
Looking for more investment ideas beyond Manulife Financial?
Do not stop at one solid insurance stock. Use this momentum to broaden your watchlist with stocks that match your risk tolerance and income goals.
- Target resilient upside potential by scanning a curated set of financially strong opportunities through the 9 high quality undiscovered gems.
- Prioritise capital preservation and steadier rides by reviewing a focused group of 7 resilient stocks with low risk scores.
- Build a stronger income base by checking out companies in the 3 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com