


Top Asian Growth Companies With Insider Ownership October 2026
As the Asian markets navigate through a landscape marked by geopolitical tensions and fluctuating energy prices, investors are keenly observing growth opportunities that align with these evolving conditions. In this context, companies exhibiting strong insider ownership can be particularly appealing as they often indicate confidence from those closest to the business in its long-term prospects.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Shanghai Biren Technology (SEHK:6082) | 10.4% | 119.7% |
| Seojin SystemLtd (KOSDAQ:A178320) | 18% | 106.6% |
| SEERS (KOSDAQ:A458870) | 33.8% | 37.8% |
| L&C BIOLTD (KOSDAQ:A290650) | 20.9% | 163% |
| HUMAN MADE (TSE:456A) | 29.1% | 28.7% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 32% |
| Gold Circuit Electronics (TWSE:2368) | 29.8% | 46.1% |
| Fulin Precision (SZSE:300432) | 10.8% | 66.5% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
Here's a peek at a few of the choices from the screener.
Kingdee International Software Group (SEHK:268)
Simply Wall St Growth Rating: ★★★★☆☆
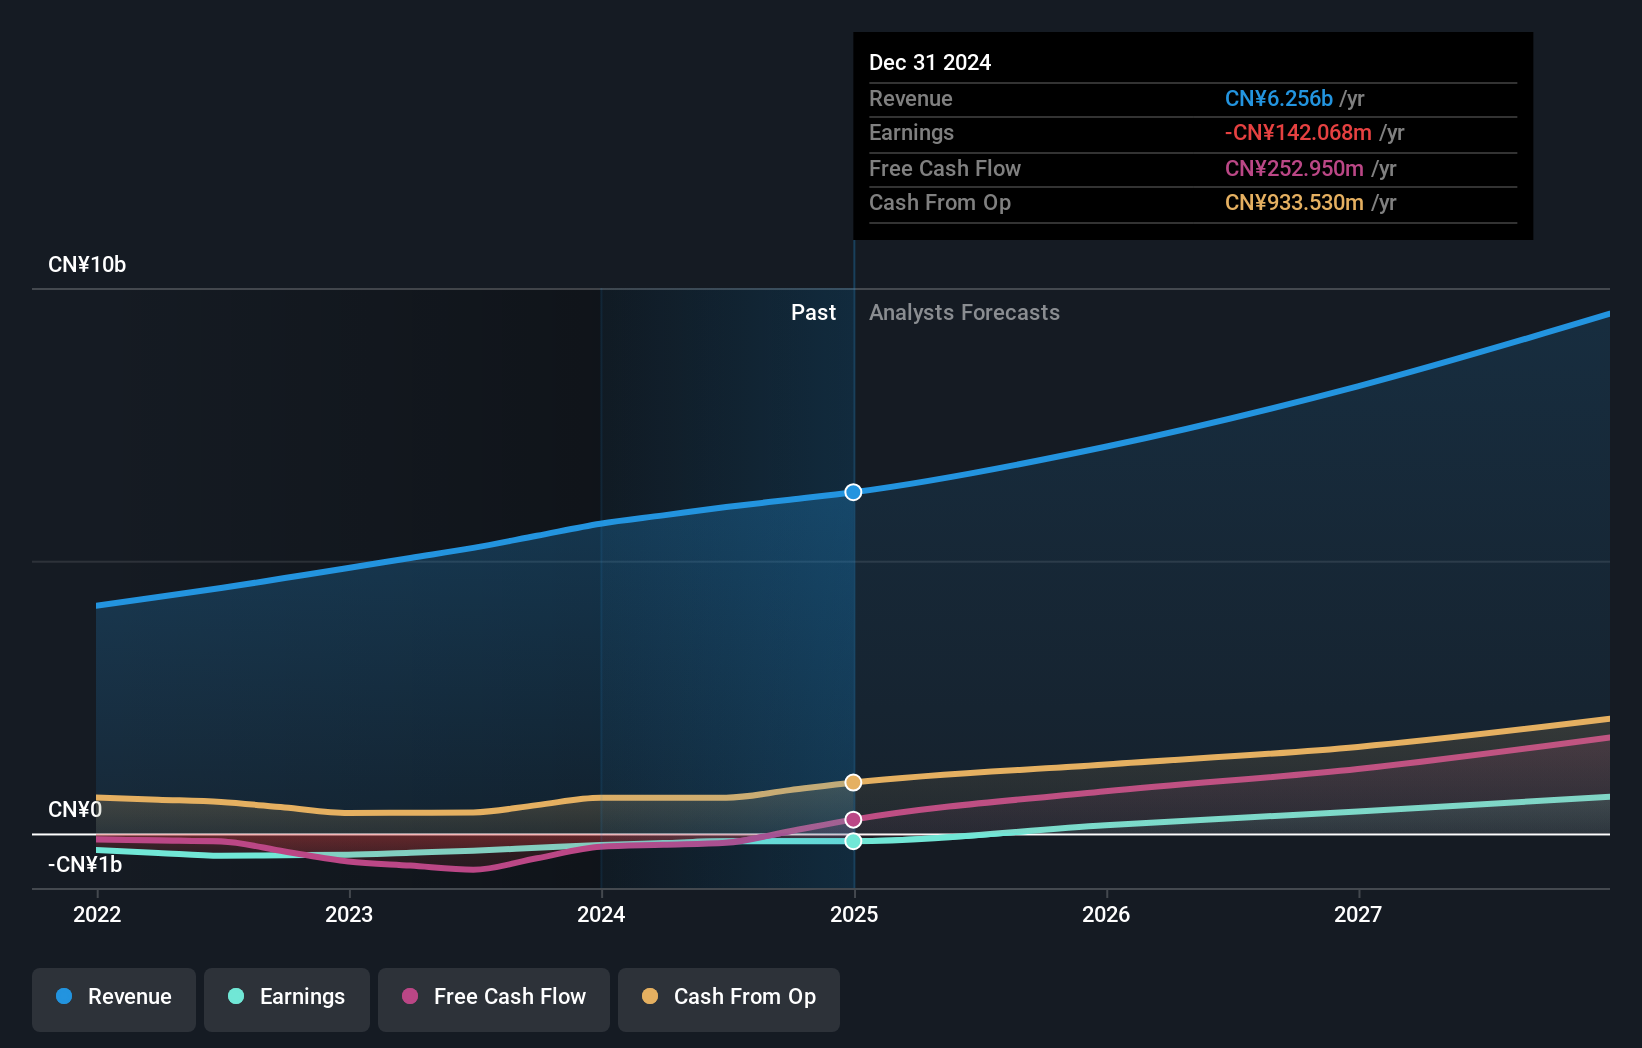
Overview: Kingdee International Software Group Company Limited is an investment holding company that focuses on the subscription and sale of software globally, with a market capitalization of approximately HK$27.53 billion.
Operations: The company generates revenue through two primary segments: Subscription and Software, which accounts for CN¥4.53 billion, and Implementation, Consulting, Maintenance Services and Others, contributing CN¥2.91 billion.
Insider Ownership: 20.1%
Kingdee International Software Group, with substantial insider ownership, has shown a positive turnaround by becoming profitable this year. Its earnings are expected to grow significantly at 36.87% annually over the next three years, outpacing the Hong Kong market's growth rate. Recent financial results highlight a shift from a net loss to a net income of CNY 54.5 million for H1 2026, reflecting improved operational performance despite slower revenue growth forecasts compared to its earnings trajectory.
- Unlock comprehensive insights into our analysis of Kingdee International Software Group stock in this growth report.
- In light of our recent valuation report, it seems possible that Kingdee International Software Group is trading beyond its estimated value.
Yunnan Energy New Material (Group) (SZSE:002812)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Yunnan Energy New Material (Group) Co., Ltd. and its subsidiaries specialize in providing film products both in China and internationally, with a market cap of CN¥46.78 billion.
Operations: Yunnan Energy New Material (Group) Co., Ltd. generates revenue through the production and distribution of film products across domestic and international markets.
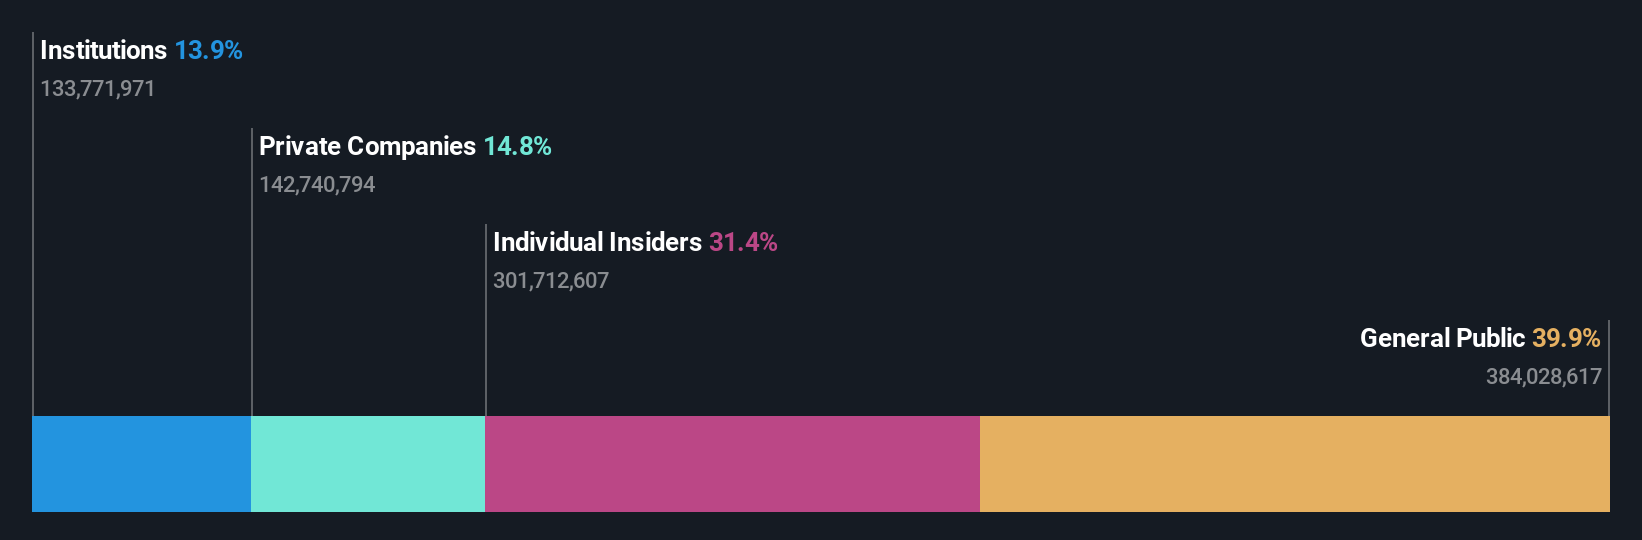
Insider Ownership: 31.5%
Yunnan Energy New Material (Group) has demonstrated strong growth potential with forecasted earnings growth of 48.3% annually, surpassing the Chinese market average. The company became profitable this year, reporting a net income of CNY 820.32 million for H1 2026 against a prior loss. Despite low forecasted return on equity and debt coverage concerns, it trades significantly below its estimated fair value. Recent shareholder-approved initiatives include share repurchases and capital reductions to enhance financial flexibility.
- Get an in-depth perspective on Yunnan Energy New Material (Group)'s performance by reading our analyst estimates report here.
- Insights from our recent valuation report point to the potential undervaluation of Yunnan Energy New Material (Group) shares in the market.
Fujian Wanchen Food Group (SZSE:300972)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Fujian Wanchen Food Group Co., Ltd. operates in the research, development, cultivation, production, and sale of edible fungi both in China and internationally, with a market cap of CN¥31.75 billion.
Operations: Fujian Wanchen Food Group Co., Ltd. generates revenue through its activities in the research, development, cultivation, production, and sale of edible fungi across domestic and international markets.
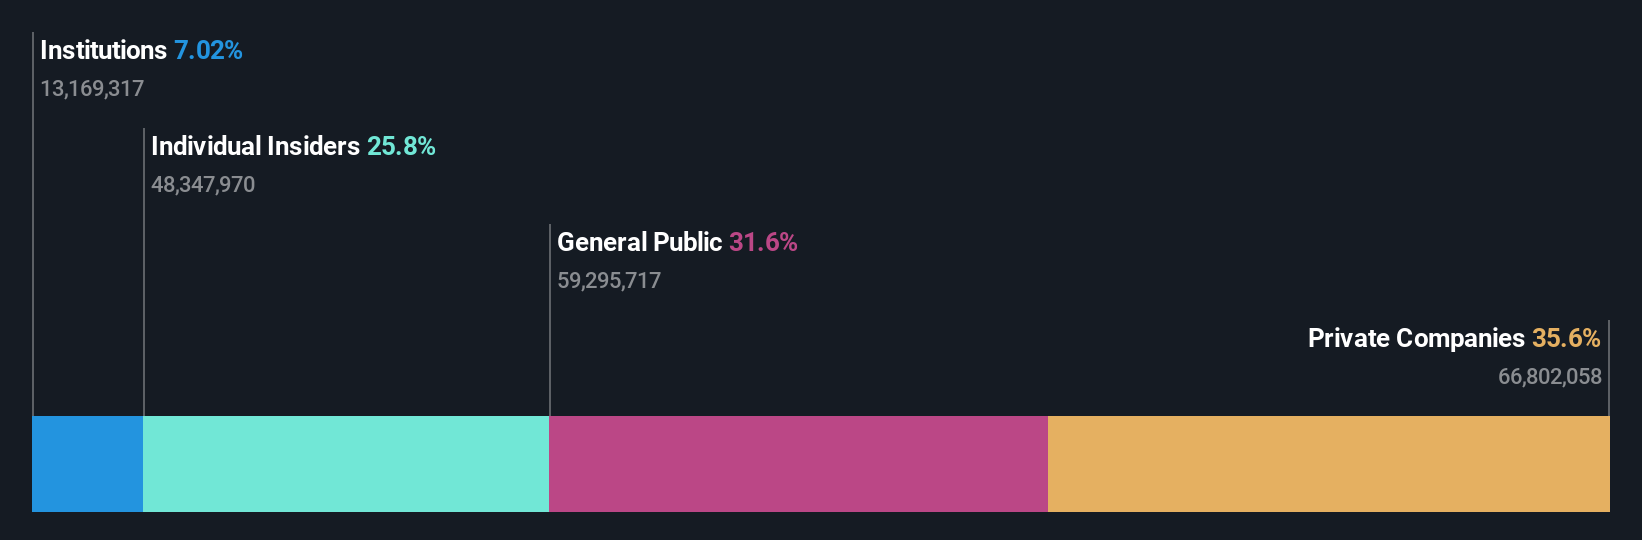
Insider Ownership: 27.5%
Fujian Wanchen Food Group shows robust growth potential with a significant earnings increase of 172.6% over the past year, and a forecasted annual profit growth of 22.8%. Its revenue is expected to grow at 17% annually, slightly outpacing the Chinese market. The company trades at a substantial discount to its estimated fair value, with analysts predicting a potential stock price rise of 72.2%. Recent dividend affirmations reflect strong financial performance amidst high insider ownership.
- Click to explore a detailed breakdown of our findings in Fujian Wanchen Food Group's earnings growth report.
- Our valuation report here indicates Fujian Wanchen Food Group may be undervalued.
Taking Advantage
- Access the full spectrum of 499 Fast Growing Asian Companies With High Insider Ownership by clicking on this link.
- Interested In Other Possibilities? The end of cancer? These 35 emerging AI stocks are developing tech that will allow early idenification of life changing disesaes like cancer and Alzheimer's.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com