


HSBC Holdings (LSE:HSBA) Could Be 9% Undervalued Following Ant International Payment Expansion
Ant International’s expanded collaboration with HSBC Holdings (LSE:HSBA) in the Middle East puts the bank’s Tokenised Deposit Service in focus. Real-time, tokenised transfers now support both intra-UAE dirham flows and cross-border US dollar payments.
For investors tracking HSBC Holdings, recent trading tells a mixed story. The share price is up 17.12% year to date, helped by partnerships like Ant International and capital moves such as the planned 2026 bond redemption. However, the 30 day share price return is down 10.10% and shorter term momentum has cooled. At the same time, total shareholder return of 46.77% over one year and very large gains over five years point to a stock where long run holders have seen material value creation even as near term sentiment resets.
Scan beyond HSBC Holdings and size up other banks leaning into real time payments and tokenisation through our hand picked list of solid balance sheet and fundamentals (9 results)
HSBC Holdings now trades at a clear discount to both analyst targets and some intrinsic value estimates after a sharp short term pullback. Is that gap mispricing caution, or a fair read on risk before you look at valuation detail next?
Most Popular Narrative: 9% Undervalued
Against a last close of £13.96, the most followed narrative pegs HSBC Holdings' fair value at £15.34, using an 8.4% discount rate and detailed long range forecasts to get there.
The bank is intensifying investment in Asian wealth management and private banking, leveraging a strong brand and local presence in fast-growing wealth markets like Hong Kong, mainland China, and Southeast Asia. This positions HSBC to capture rising affluence and middle class expansion, which may support future growth in fee income, more resilient earnings, and higher margins. HSBC's global network and expertise in facilitating cross-border trade may also support participation in the continued expansion of Asian intra-regional and international trade flows and Belt and Road-related capital movement, which in turn may contribute to stronger, sustained growth in transaction banking revenues and non-interest fee income.
See why 160 investors see HSBC Holdings as 9% undervalued.
Result: Fair Value of £15.34 (UNDERVALUED)
Still, the thesis around HSBC Holdings can be knocked off course if Hong Kong commercial real estate credit losses stay elevated or if Asia focused growth slows materially.
Find out about the key risks to this HSBC Holdings narrative.
Another View On HSBC Holdings Valuation
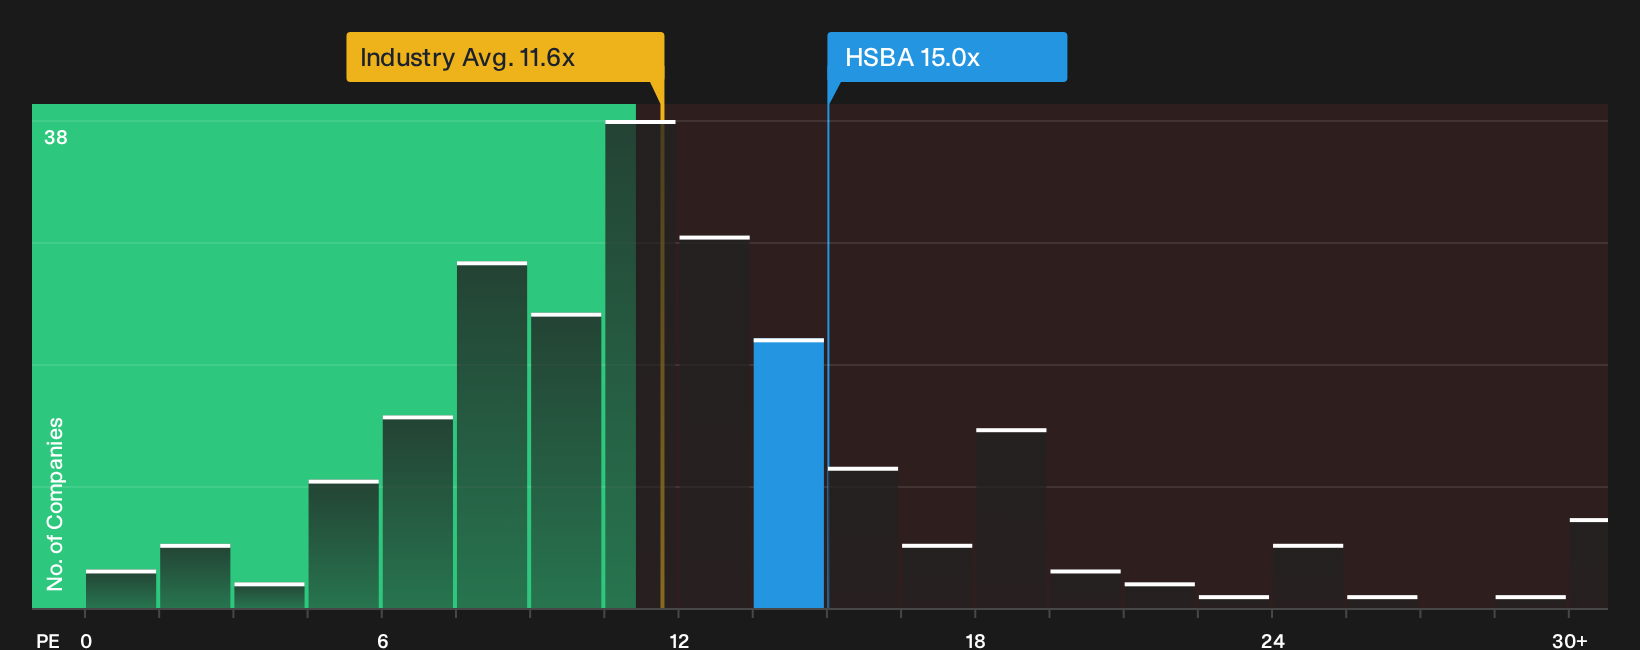
Multiples tell a different story. HSBC Holdings trades on a P/E of 15x, while the European banks group averages 11.6x and peers are closer to 10.4x. The fair ratio is 10.9x. That premium suggests less margin for error if sentiment or earnings expectations slip. Where does that leave your risk tolerance?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around HSBC Holdings is split, with clear rewards on one side and flagged risks on the other. Move quickly, inspect the detail yourself, then weigh up the balance with our breakdown of 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond HSBC Holdings?
Do not stop with one bank. Broaden your watchlist and stress test your thinking by comparing HSBC Holdings with other stocks that match different priorities.
- Target potential mispricing by scanning a curated pool of quality candidates that screens for valuation support through the 7 high quality undervalued stocks.
- Build resilience into your portfolio by focusing on companies with stronger finances, using the list of solid balance sheet and fundamentals (9 results) to pressure test balance sheet strength.
- Turn income goals into a clear watchlist by zeroing in on higher yield opportunities through the 1 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com