


How Investors Are Reacting To Western Digital (WDC) Ahead Of Earnings
- Western Digital is preparing to report its next earnings update after recently recording a period of outperformance, with analyst consensus pointing to higher EPS and revenue than the same quarter last year.
- The business is drawing attention for its positioning in high capacity drives that support cloud data growth, which ties Western Digital directly to long term demand for economical bulk storage in AI and hyperscale data centers.
- This article will examine how Western Digital's investment narrative aligns with expectations for stronger earnings supported by cloud driven storage demand.
Scan beyond Western Digital and see which peers are also tied into the AI data build out with the 92 AI infrastructure stocks.
Western Digital Investment Narrative Recap
To own Western Digital, you need to be comfortable that AI and cloud storage demand keeps pulling through very high capacity HDDs, and that the firm can keep pushing areal density while holding unit costs in check. The upcoming October 22 earnings update matters because it will show how well that cloud heavy story is translating into current orders and product mix.
The near term swing factor is margin guidance, especially after past concern around softer fiscal 1Q27 outlook versus a key rival. The biggest risk is the transition toward 44TB HAMR drives in 2027, where higher production expenses or slower qualifications could squeeze profitability or delay the richer mix investors are looking for.
With no fresh corporate announcements tied directly to this earnings date, the most relevant reference point remains Western Digital’s earlier push into larger ePMR and UltraSMR drives at 32TB and 40TB. That rollout frames investor expectations going into results. Readers will likely be watching how quickly those products are filling cloud racks.
Those higher capacity HDDs intersect directly with today’s catalyst, which is AI driven demand for economical bulk storage. Stronger adoption could support a healthier margin structure and reinforce Western Digital’s role in hyperscale data centers. Slower take up or tougher pricing, especially with a competitor already shipping 44TB HAMR, would point to a more uneven execution path.
Western Digital's narrative projects US$32.0b revenue and US$15.2b earnings by 2029. This implies 35.3% yearly revenue growth and an earnings increase of about US$5.9b from US$9.3b today.
Uncover why Western Digital's fair value indicates a 67% potential upside to its current price, which could close more quickly than many investors expect.
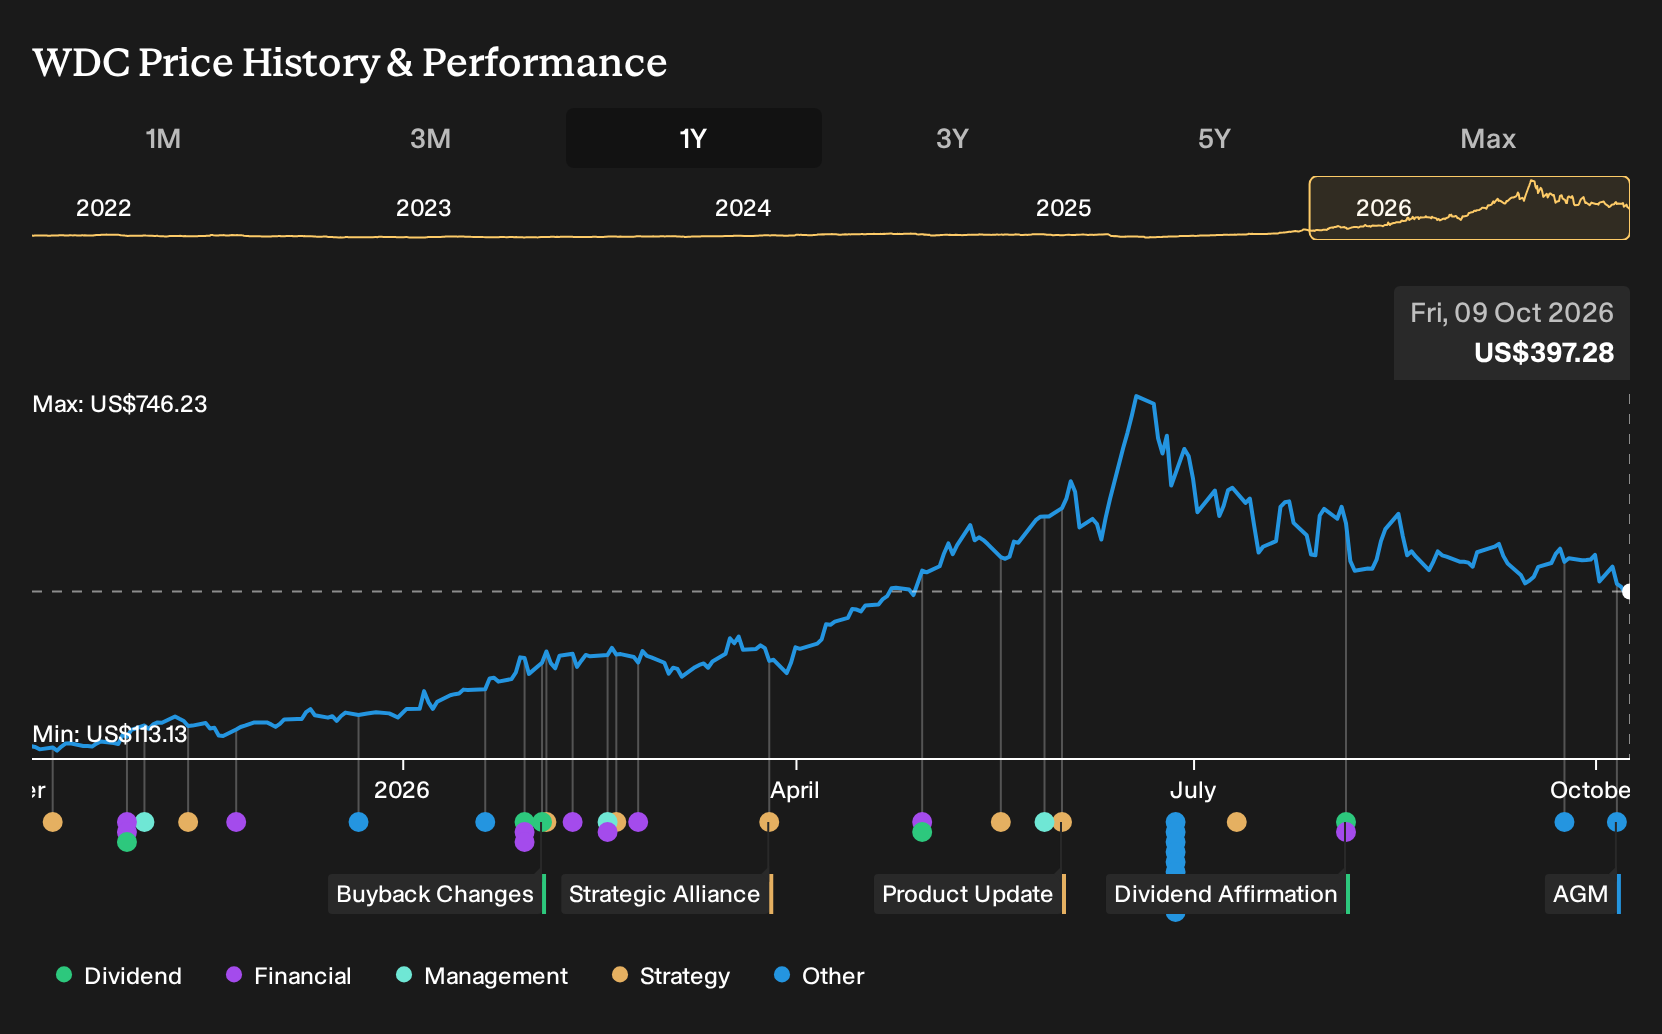
Exploring Other Perspectives
One bullish twist on Western Digital focuses on customer mix. While the baseline view already bakes in strong cloud demand, the most optimistic analysts lean on a scenario where around 90% of revenue skews to hyperscale and long term agreements. They were penciling in US$36.9b of sales and US$16.8b of earnings by 2029, so this upcoming report could easily reshuffle how credible that more aggressive path looks. You do not need to pick a side today, but it helps to know that reasonable people reading the same data can reach very different conclusions.
Explore 6 other Western Digital fair value estimates, including one that suggests as much as 197% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Western Digital research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Western Digital. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Western Digital's overall financial health at a glance.
Looking for More Western Digital Style Ideas?
If Western Digital has sharpened your focus on where capital could work harder, it can help to line it up against other candidates that share some of the qualities you care about. Use the Simply Wall St Screener to quickly surface stocks that fit your risk appetite, income needs, or balance sheet preferences, then compare them side by side with your view on Western Digital.
- For investors hunting for resilient balance sheets and cleaner fundamentals, start with a list of solid balance sheet and fundamentals (25 results) and see which companies clear your quality bar.
- If capital protection ranks high on your list, narrow your radar to businesses that historically screen as steadier, using a 31 resilient stocks with low risk scores to focus your research time.
- Anyone looking for under the radar opportunities can scan a 20 high quality undiscovered gems that highlight companies with strong fundamentals but less crowded attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com