


ZORYVE Data May Change The Case For Arcutis Biotherapeutics (ARQT)
- Arcutis Biotherapeutics recently shared new data across its ZORYVE portfolio at major dermatology conferences, including Phase 2 results in infants with atopic dermatitis and additional analyses in plaque psoriasis and seborrheic dermatitis.
- The focus on younger pediatric atopic dermatitis patients and special site psoriasis reflects management's push to broaden ZORYVE's addressable treated population and real-world relevance.
- We will now look at how Arcutis Biotherapeutics' investment narrative could shift in light of the new pediatric ZORYVE data in atopic dermatitis.
Scan how Arcutis Biotherapeutics compares with other potential breakout healthcare stories by reviewing our curated list of 34 healthcare AI stocks.
Arcutis Biotherapeutics Investment Narrative Recap
For an investor to stay on board with Arcutis Biotherapeutics, the core belief is that the ZORYVE franchise can keep scaling across more age groups and indications without running into major access or safety roadblocks. The key near term swing factor remains commercial execution and payer coverage for existing labels, since the business is highly concentrated in one product family.
The new pediatric data in atopic dermatitis and special site psoriasis supports that broader use case story but does not fundamentally change the biggest operational risk, which is that ZORYVE uptake or reimbursement could undershoot expectations. R&D and commercialization spend also still needs to be contained so profitability does not slip back.
The most relevant update here is the Phase 2 INTEGUMENT INFANT data for ZORYVE cream 0.05% in patients 3 to under 24 months, with an FDA review already in progress and a PDUFA date set for February 23, 2027. That potential label expansion sits squarely on the main growth thesis around larger pediatric atopic dermatitis populations.
If approved, an infant indication could meaningfully widen the addressable treated group for Arcutis Biotherapeutics and deepen its positioning with pediatric dermatologists, although payer behavior and real world use would still need to line up. Until that decision, ZORYVE remains the engine, so concentration risk, high P/E and ongoing spend all stay front of mind for anyone tracking near term execution.
Arcutis Biotherapeutics' current analyst narrative points to US$889.8 million in revenue and US$342.4 million in earnings by 2029, based on a 24.2% yearly revenue growth assumption and an increase of about US$314 million in earnings from US$28.5 million today.
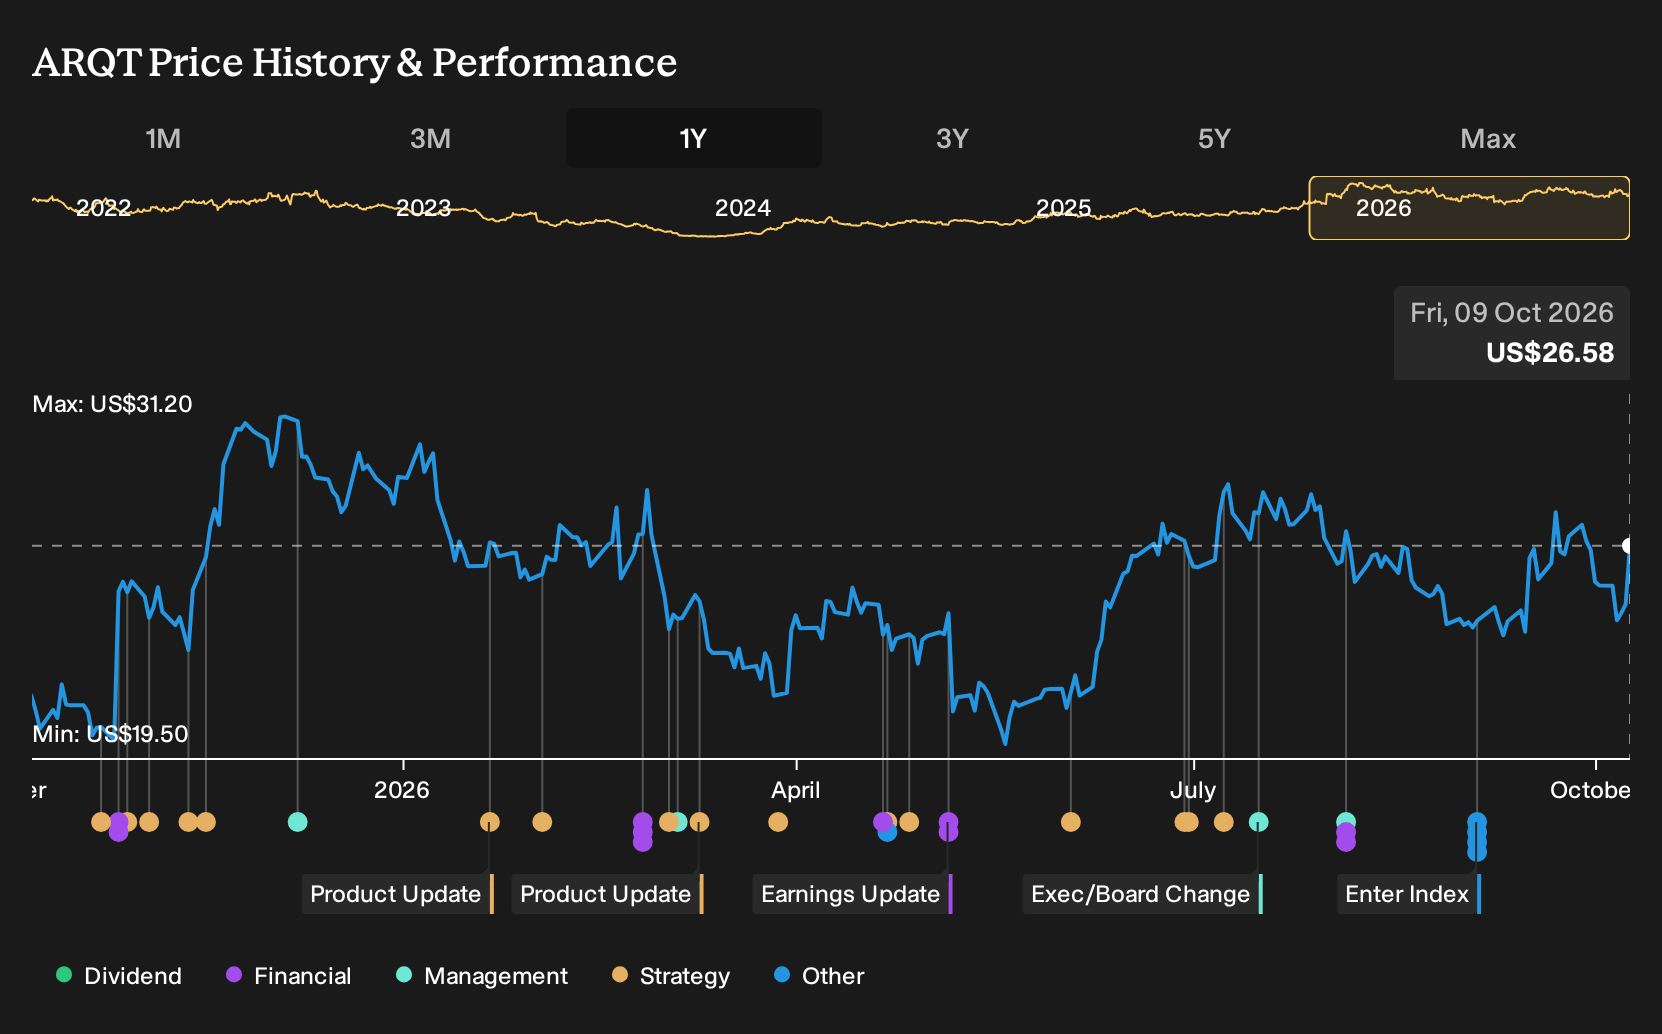
Uncover why Arcutis Biotherapeutics' fair value indicates a 39% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$36.88 to US$85.61 per share, so retail opinions on Arcutis Biotherapeutics already differ sharply. When you factor in the heavy dependence on ZORYVE and evolving payer rules, it is a reminder to weigh multiple viewpoints before relying on any single forecast.
Explore 2 other Arcutis Biotherapeutics fair value estimates, including one that suggests it could be worth just $36.88!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Arcutis Biotherapeutics research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Arcutis Biotherapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Arcutis Biotherapeutics' overall financial health at a glance.
Looking For More Investment Ideas Beyond Arcutis Biotherapeutics?
If Arcutis Biotherapeutics has put dermatology on your radar, it can be useful to widen the lens and compare it with other potential opportunities. The Simply Wall St Screener lets you filter for very different styles of investment so you can see where Arcutis Biotherapeutics fits within your broader watchlist.
- If you prefer early stage potential with higher risk and higher possible payoff swings, then scan through 14 elite penny stocks with strong financials that meet your criteria.
- If value and quality are more your focus, weigh Arcutis Biotherapeutics against a curated pool of 29 high quality undervalued stocks that combine fundamentals with attractive pricing.
- For investors who want sturdy finances at the foundation of any position, compare this dermatology specialist to a list of solid balance sheet and fundamentals (25 results) and see how it measures up.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com