


Did Reaffirmed 2026 Guidance Just Shift Entegris (ENTG) Stock Narrative?
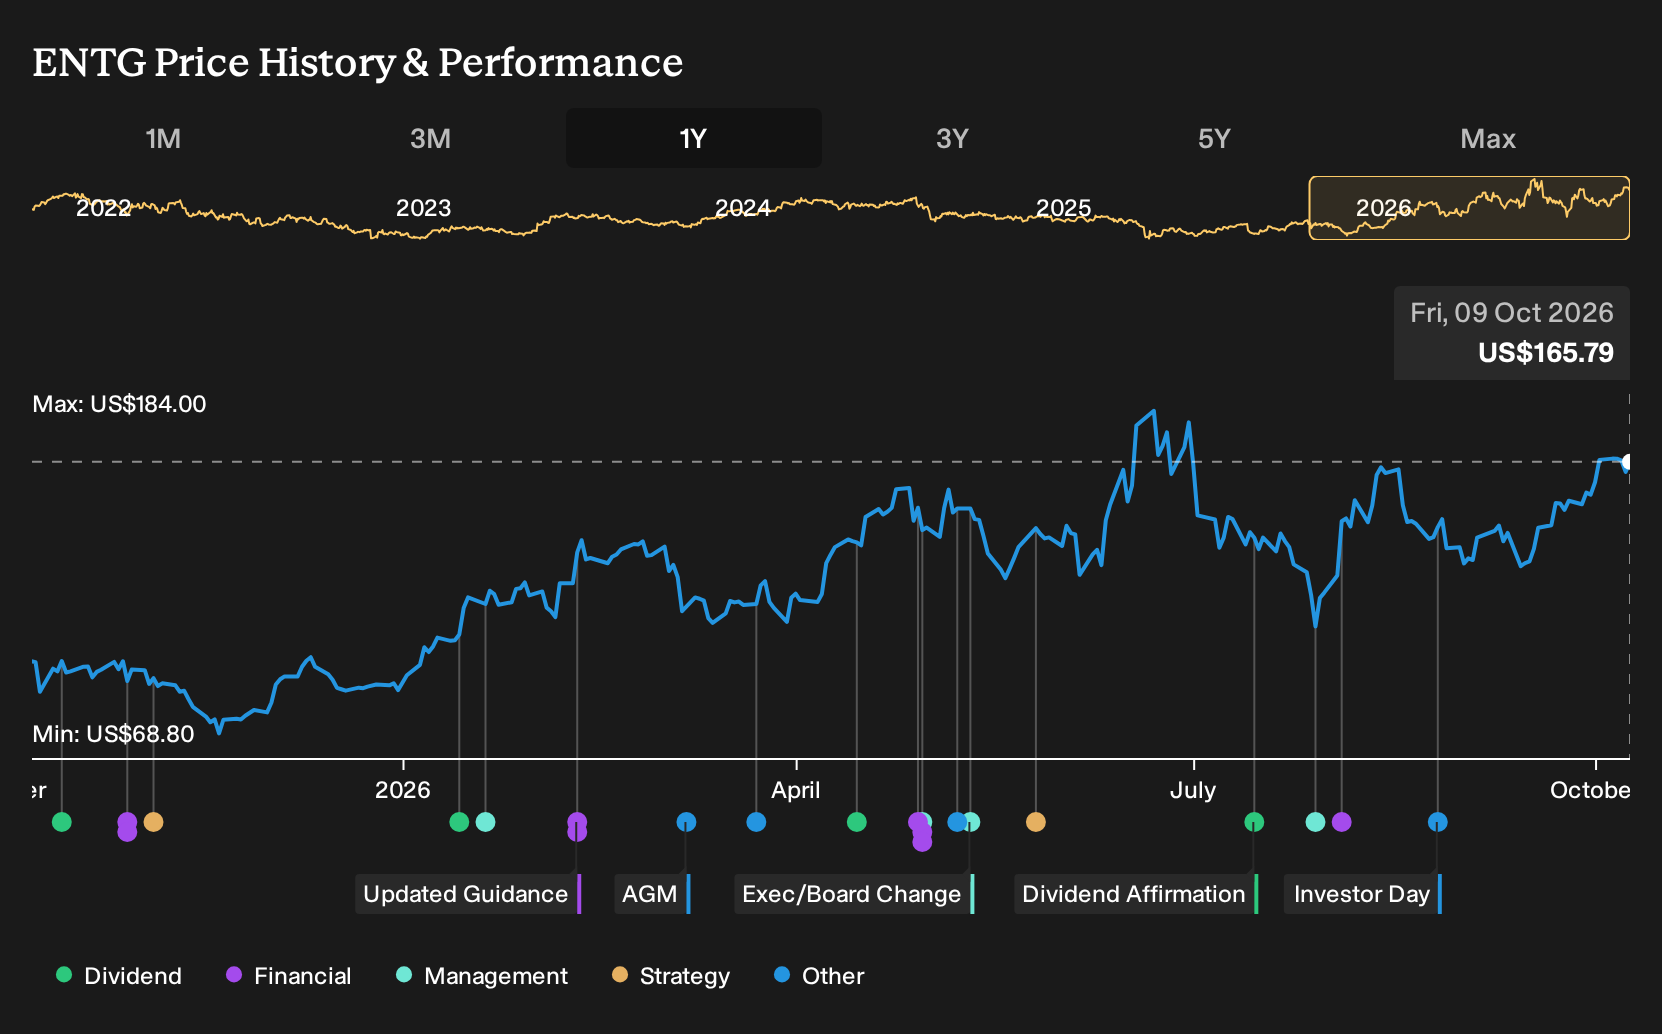
- Entegris reported roughly two years of flat sales, soft demand expected to persist for about 12 months, constrained free cash flow, yet management recently reaffirmed Q3 and Q4 2026 guidance with plans for sequential revenue growth and mid-teens year-over-year gains.
- The tension for Entegris now sits between a high forward P/E multiple and fundamentals that show muted top line momentum and tight cash generation. This puts unusual weight on execution against the reaffirmed 2026 outlook.
- We will now look at how Entegris's reaffirmed late 2026 guidance could reshape the existing investment narrative around growth and valuation.
Compare Entegris' premium P/E and flat sales against a curated set of resilient balance sheet plays by scanning our list of solid balance sheet and fundamentals (25 results) today.
Entegris Investment Narrative Recap
For Entegris, an investor essentially has to believe that AI linked wafer demand and new fabs will eventually translate into stronger materials volumes, better factory utilization and healthier free cash flow. The recent update of roughly two years of flat sales with another year of soft demand keeps that thesis intact but clearly adds more pressure on execution.
The reaffirmed Q3 and Q4 2026 guidance becomes the key near term catalyst. It is now the reference point for whether orders are finally inflecting or just stabilizing. The biggest operational risk is that muted top line and constrained cash generation persist while the stock still carries a high P/E and a meaningful debt load.
The most relevant development is management reaffirming late 2026 guidance that calls for sequential revenue improvement and mid teens year over year growth in the back half of that year. That message matters because it directly addresses concerns created by the recent stretch of flat sales and only moderate free cash flow.
For you as a shareholder, everything now ties back to whether Entegris can turn that guidance into actual orders flowing through Materials Solutions and Advanced Purity Solutions. Progress on margins, the ramp of newer facilities and capex discipline already underway becomes more important, since any shortfall against those late 2026 targets could quickly refocus attention on the elevated valuation and balance sheet risk.
Entegris' narrative projects US$4.5b revenue and US$685.0 million earnings by 2029. That profile rests on analysts' assumption of 10.5% yearly revenue growth and an earnings increase of about US$379.5 million from US$305.5 million today.
Uncover how Entegris' fair value indicates a 5% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on Entegris’ valuation risk rather than the 2026 guidance. The most cautious analysts were working off a Fair Value near US$126.92 with a price target floor at US$120. They were also using revenue projections closer to US$4.3b by 2029. Those forecasts predate this update, so you may see opinions shift.
Explore 4 other Entegris fair value estimates, including one that suggests as much as 42% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view based on thorough research.
- A great starting point for your Entegris research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Entegris. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Entegris' overall financial health at a glance.
Looking for more investment ideas beyond Entegris?
If the Entegris story leaves you wanting a broader watchlist, the Simply Wall St Screener can help you quickly surface other businesses that better fit your risk tolerance, income goals or valuation preferences.
- For investors hunting for mispriced quality, scan a focused set of potential value opportunities through our 29 high quality undervalued stocks.
- If capital preservation sits high on your priority list, narrow in on companies with steadier profiles by reviewing a 31 resilient stocks with low risk scores.
- Income focused investors can zero in on higher yielding opportunities by using the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com