


Is Casella Waste Systems (CWST) Below Fair Value As Hakes Expansion Approval Adds Capacity?
Regulatory approval gives Casella Waste Systems new capacity story
Casella Waste Systems (CWST) just secured New York State approval to expand its Hakes construction and demolition landfill, adding roughly 43.3 acres of disposal area and an estimated 5.8 million cubic yards of extra capacity.
Recent trading tells a mixed story for Casella Waste Systems. The share price is down 6.8% over the past month and 14.6% over three months, with a year to date share price return that has declined 15.1%. However, the 3 year total shareholder return of 8.5% points to more resilient longer term sentiment as investors weigh this new capacity approval against earlier expectations for risk and growth.
Scan beyond Casella Waste Systems and compare this landfill capacity story with hand-picked waste and infrastructure peers screened for resilient balance sheets and fundamentals in our list of solid balance sheet and fundamentals (25 results).
Bulls see fresh Hakes capacity and a near 46% intrinsic discount as a reset moment for Casella Waste Systems. Bears point to recent share price weakness and modest net income against almost US$2.0b of revenue. Which story do the numbers support next?
Most Popular Narrative: 24.5% Undervalued
Casella Waste Systems closed at $83.78 against a most followed fair value narrative of $111, so the market is treating that gap as a live debate rather than a settled fact.
Infrastructure investments in automation and technology, including the deployment of 40 automated trucks expected to deliver more than US$5 million of savings in 2026, AI enabled in cab safety systems and new billing platforms, are intended to reduce operating and G&A costs over the next several years. These initiatives can support EBITDA margin recovery and improved net income.
See why 3 investors see Casella Waste Systems as 25% undervalued.
Result: Fair Value of $111 (UNDERVALUED)
Still, the Casella Waste Systems story depends on acquisitions bedding down cleanly and margin pressure easing; otherwise integration costs and weaker earnings could quickly challenge this underpricing narrative.
Find out about the key risks to this Casella Waste Systems narrative.
Another View: Casella Waste Systems Through Sales Multiples
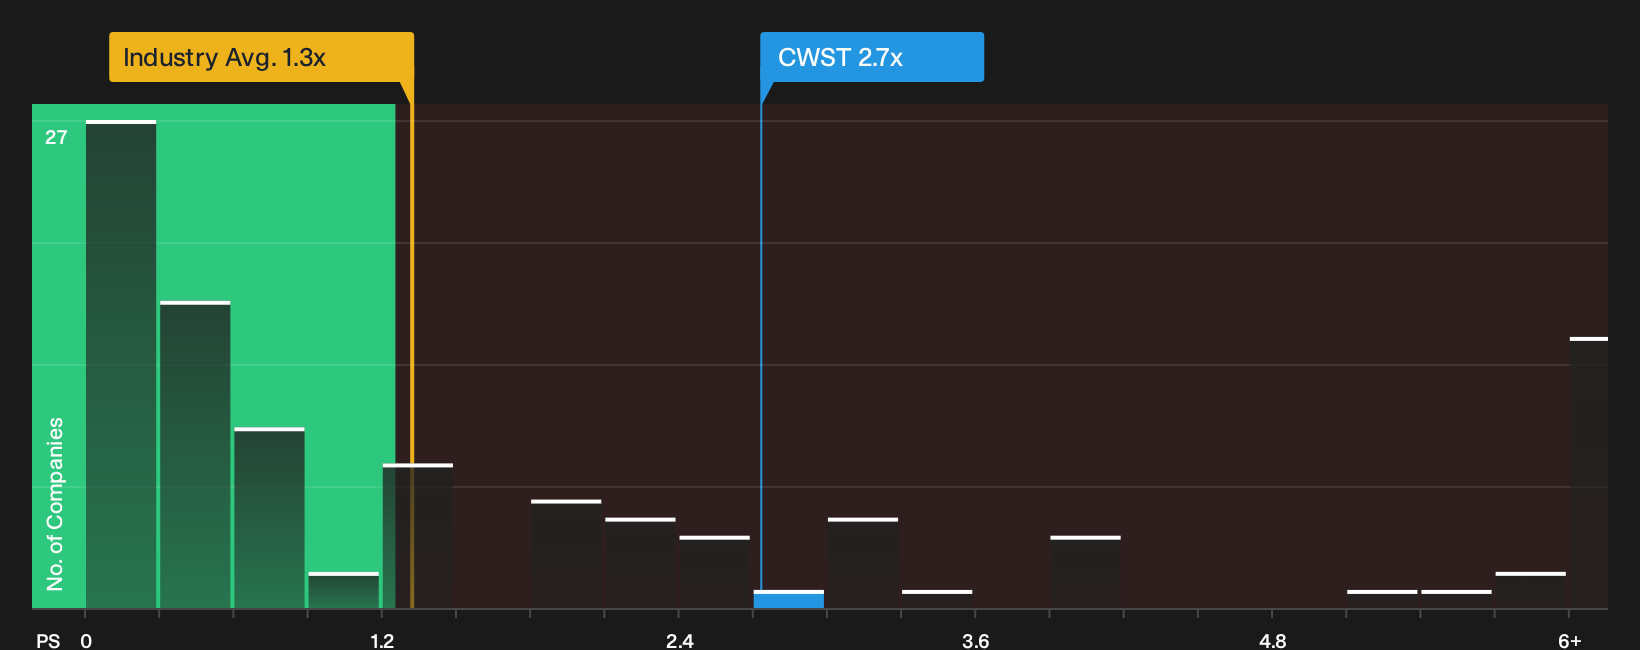
The story looks different when switching from fair value estimates to a simple P/S lens. Casella Waste Systems trades at about 2.7x sales versus a US Commercial Services average of 1.3x and a fair ratio of 1.5x, which points to a rich setup where expectations carry real valuation risk if execution slips.
That gap between current and fair ratio suggests the market already prices in a lot of the margin and profit improvement that analysts model, so the key question is whether future delivery justifies staying above both peers and that 1.5x reference point.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted by the mix of fresh capacity, valuation gaps and execution risk around Casella Waste Systems. Act quickly, review the data yourself and weigh both sides through 3 key rewards and 4 important warning signs.
Looking for more ideas beyond Casella Waste Systems?
If Casella Waste Systems has you thinking harder about valuation, do not stop there. Use the Simply Wall Street screener to spot fresh opportunities built on clear numbers and fundamentals.
- Target resilient balance sheets and steady fundamentals by scanning a curated list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced opportunities where quality and valuation meet through the 29 high quality undervalued stocks.
- Build a shortlist of steady income candidates by filtering for reliable payers in the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com