


Yancoal Australia (ASX:YAL) Is Back In Focus, But What Is Driving It?
Yancoal Australia (ASX:YAL) is back in focus after the New South Wales Independent Planning Commission approved the Hunter Valley Operations Continuation Project, granting state-level support for mining to continue at the complex until 2045.
At A$5.83, Yancoal Australia has delivered a 16.37% year to date share price return. The 1 year total shareholder return of 14.17% and 5 year total shareholder return of 180.57% point to longer term momentum that has cooled slightly in the past month, as the 30 day share price return declined 6.27%, despite the Hunter Valley approval acting as a fresh catalyst for how investors assess its future cash flow visibility and project risk.
Scan beyond Yancoal Australia and consider other coal and resource producers with recent catalysts using our hand picked list of 33 best rare earth metal stocks
Yancoal Australia now has clearer mine life and a strong production base, yet the recent pullback raises a sharper question. Are investors still paying a fair price for that certainty, or already paying up for it?
Price-to-Earnings of 26.2x: Is it justified for Yancoal Australia?
On earnings, Yancoal Australia looks expensive at a P/E of 26.2x compared with both its own fair ratio and the wider Australian Oil and Gas peer group.
The P/E multiple simply compares the current share price to earnings per share. For a coal producer like Yancoal Australia, this ratio reflects how much investors are willing to pay today for each dollar of profit, given factors such as mine life, commodity exposure and perceived risk in future earnings.
With Yancoal Australia trading on 26.2x earnings while the domestic Oil and Gas industry sits at 16.1x and peers average 19.5x, the market is assigning a richer tag to its profit stream. The estimated fair P/E of 20.4x is well below the current level, which indicates a valuation that may move closer to that fair ratio if sentiment or earnings expectations change.
Explore the SWS fair ratio for Yancoal Australia.
Result: Price-to-Earnings of 26.2x (OVERVALUED)
Still, Yancoal Australia faces twin risks if coal demand shifts in key export markets or if regulatory settings change around long dated projects.
Find out about the key risks to this Yancoal Australia narrative.
Another view on Yancoal Australia’s value
The rich P/E suggests investors are already paying up for Yancoal Australia, yet the SWS DCF model points the other way. At A$5.83 against an estimated future cash flow value of A$43.57, the shares screen as deeply undervalued. So which signal carries more weight for you?
Look into how the SWS DCF model arrives at its fair value.
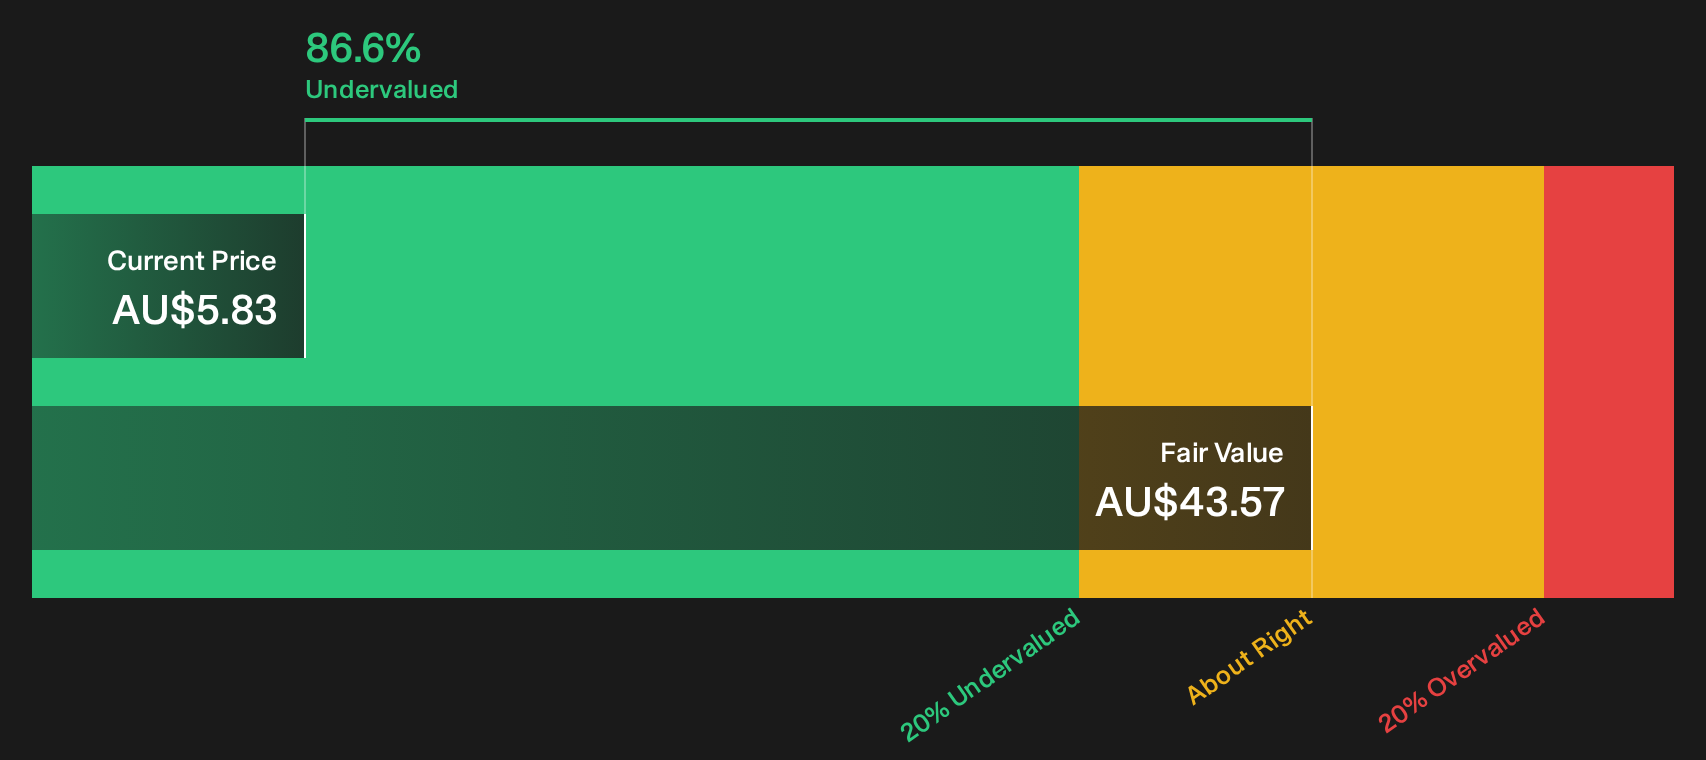
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Yancoal Australia for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 4 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Yancoal Australia can feel unsettling, so move quickly from headline reactions to your own judgement by weighing its 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Yancoal Australia?
If Yancoal Australia has your attention but you want options, use this moment to broaden your watchlist before the next wave of opportunities moves without you.
- Target resilient balance sheets and fundamentals by reviewing our curated list of solid balance sheet and fundamentals (12 results) that can help anchor a portfolio when conditions change.
- Hunt for quality at a discount through a focused set of 4 high quality undervalued stocks that pair robust financials with more modest pricing.
- Build a steadier income stream by scanning 6 dividend fortresses that concentrate on higher yields backed by underlying financial strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com