


Is United Bankshares (UBSI) Cheap As Florida Expansion Puts Growth Plans In Focus?
Florida expansion puts United Bankshares’ growth plan in focus
United Bankshares (UBSI) has put Florida on its map, announcing a de novo entry into Palm Beach with a planned full service office aimed at banking and wealth clients across South Florida.
Recent trading tells a mixed story. The share price has eased over the past week and month, with a 7 day share price return of 3.36% and a 30 day share price return of 3.73% that both move lower. This comes even as United Bankshares posts an 18.42% year to date share price gain and a 1 year total shareholder return of 32.63%, with the 3 year total shareholder return of 93.86% indicating that long term investors have already seen significant value creation.
Scan how United Bankshares compares with other banks pursuing growth through new markets by reviewing the hand picked list of solid balance sheet and fundamentals (25 results).
Florida now sits firmly in United Bankshares’ playbook, yet the stock already carries a strong multi year return record. Does the current valuation still leave enough upside for new buyers taking fresh risk today?
Preferred P/E of 12x for United Bankshares: Is it justified?
On simple valuation ratios, United Bankshares trades on a P/E of 12x, with the stock at $45.46 and a market value of about $6.18b. That level sits in an interesting middle ground where the shares screen cheaper than some peers but not cheap against the broader US banks group.
The P/E ratio compares the current share price to earnings per share. For a lender like United Bankshares it is a quick way to see what investors are willing to pay for each dollar of profit. A higher multiple often signals expectations for stronger profit growth or lower perceived risk, while a lower figure can point to more modest growth assumptions or concerns about the earnings profile.
Here, the 12x P/E is described as good value compared with a peer average of 13.4x. This suggests the market assigns a lower price tag than a typical comparable bank. At the same time, the same 12x level is flagged as expensive relative to the wider US banks industry on 11.4x, which indicates investors are paying a premium to the sector even though forecast revenue growth of 4.6% and earnings growth of 0.7% per year are both slower than the US market. Put together, these signals imply the ratio could drift toward a lower fair level of 10.8x if sentiment or growth expectations cool.
Explore the SWS fair ratio for United Bankshares.
Result: Price-to-earnings of 12x (ABOUT RIGHT)
Still, the recent share pullback over 7, 30 and 90 days, along with slower forecast earnings growth than the wider US banks group, could pressure the United Bankshares story.
Find out about the key risks to this United Bankshares narrative.
Another view on United Bankshares’ value
The P/E picture hints at a full price for United Bankshares, yet the SWS DCF model presents a different perspective. On that cash flow view, UBSI at $45.46 sits below an estimated value of $66.39, which frames the stock as undervalued. Which lens should carry more weight for you today?
Look into how the SWS DCF model arrives at its fair value.
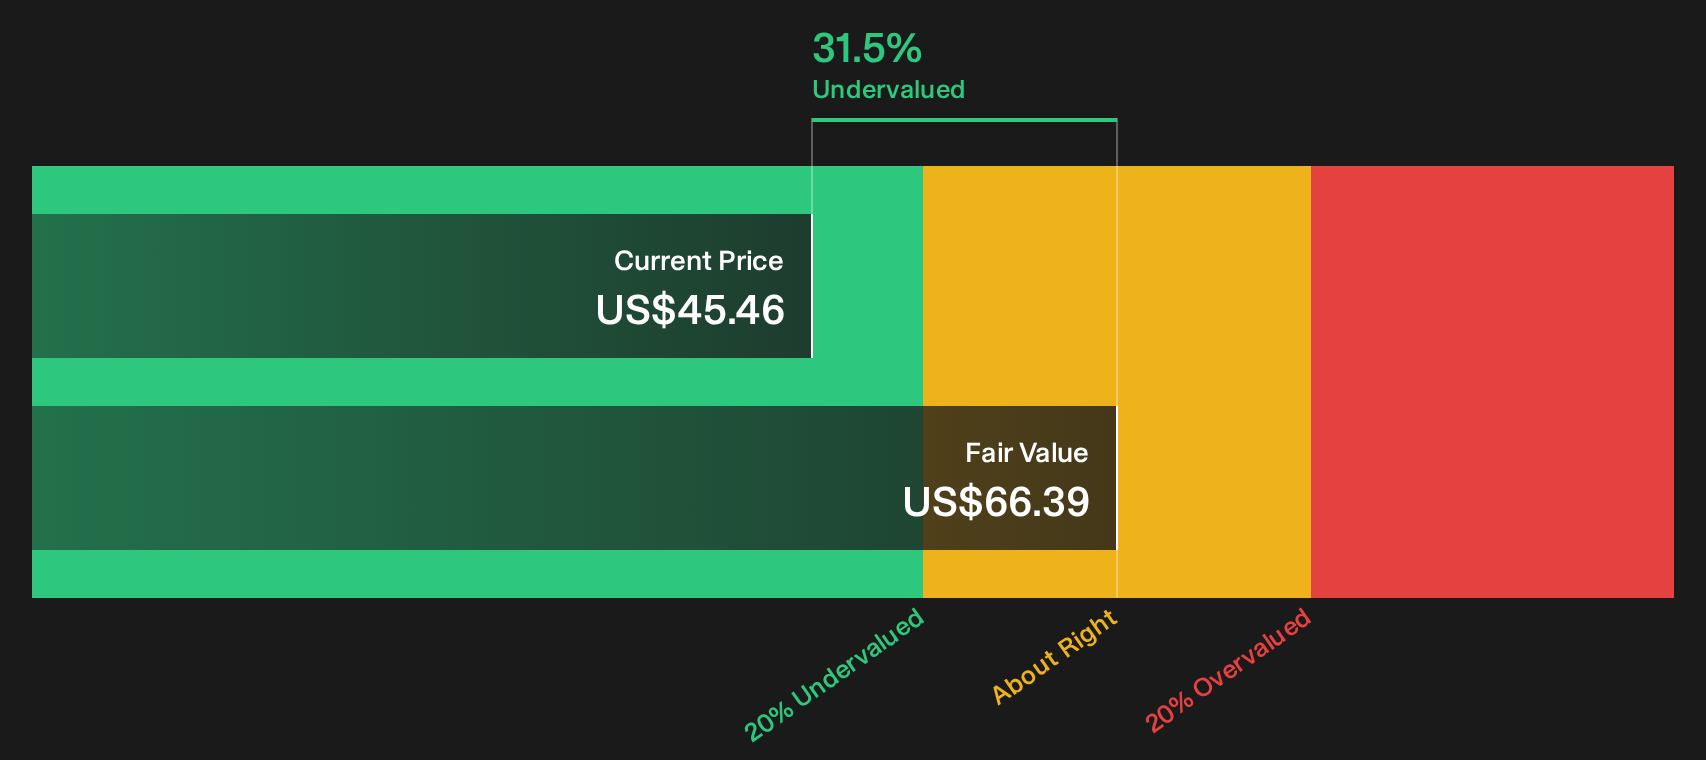
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out United Bankshares for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on United Bankshares can either feel like a warning or an opening, so move quickly, stress test the numbers, and then weigh the 3 key rewards.
Looking for more investment ideas beyond United Bankshares?
You have already done the work on United Bankshares. Do not stop there when a broader watchlist could sharpen your next investing decision.
- Target steadier compounding by reviewing a curated set of lower volatility candidates through the 31 resilient stocks with low risk scores.
- Hunt for potential mispricings by checking companies that pair quality fundamentals with appealing prices in the 29 high quality undervalued stocks.
- Build a cash flow focused portfolio by scanning income oriented opportunities screened as 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com