


Joby Aviation (JOBY) Faces Fresh Pressure, Is The 49% Undervalued View Still Credible?
Joby Aviation (JOBY) is back in focus after a Barclays downgrade to Underweight and a separate jury verdict that awarded Aerosonic about US$116.9 million in a trade secrets dispute involving Joby Aero Inc.
Joby Aviation’s share price reaction has been sharp, with the stock down 5.39% over the last session and 14.87% over 30 days, and the 62.12% year to date share price decline alongside a 66.58% one year total shareholder return fall indicates that momentum has clearly faded as investors reassess both legal risks and execution capacity.
Spot opportunities on both sides of the Joby Aviation story by scanning a curated group of beaten down but financially solid stocks in our 31 resilient stocks with low risk scores.The selloff raises a blunt question: Are investors finally pricing Joby Aviation closer to its loss making, cash intensive reality, or just swinging too far on sentiment after a downgrade and legal hit as we look at valuation next?
Most Popular Narrative: 49% Undervalued
Against a last close of $5.44, the most followed narrative pegs Joby Aviation’s fair value at about $10.68. This implies investors are heavily discounting the long runway that supporters see in its eVTOL platform, partnerships and route build out.
The company is investing heavily ahead of broad commercial adoption, including scaling manufacturing with Toyota, building out facilities in Marina and Dayton, and preparing global operations. This could keep cash use high and delay earnings leverage if real air taxi demand or pricing power falls short of expectations, pressuring future net margins.
See why 43 investors see Joby Aviation as 49% undervalued.
Result: Fair Value of $10.68 (UNDERVALUED)
Still, some of the very factors behind the bullish Joby Aviation narrative could backfire if FAA certification timelines slip or cash burn stays elevated despite new routes and partnerships.
Find out about the key risks to this Joby Aviation narrative.
Another View: Rich Sales Multiple Keeps Pressure On Joby Aviation
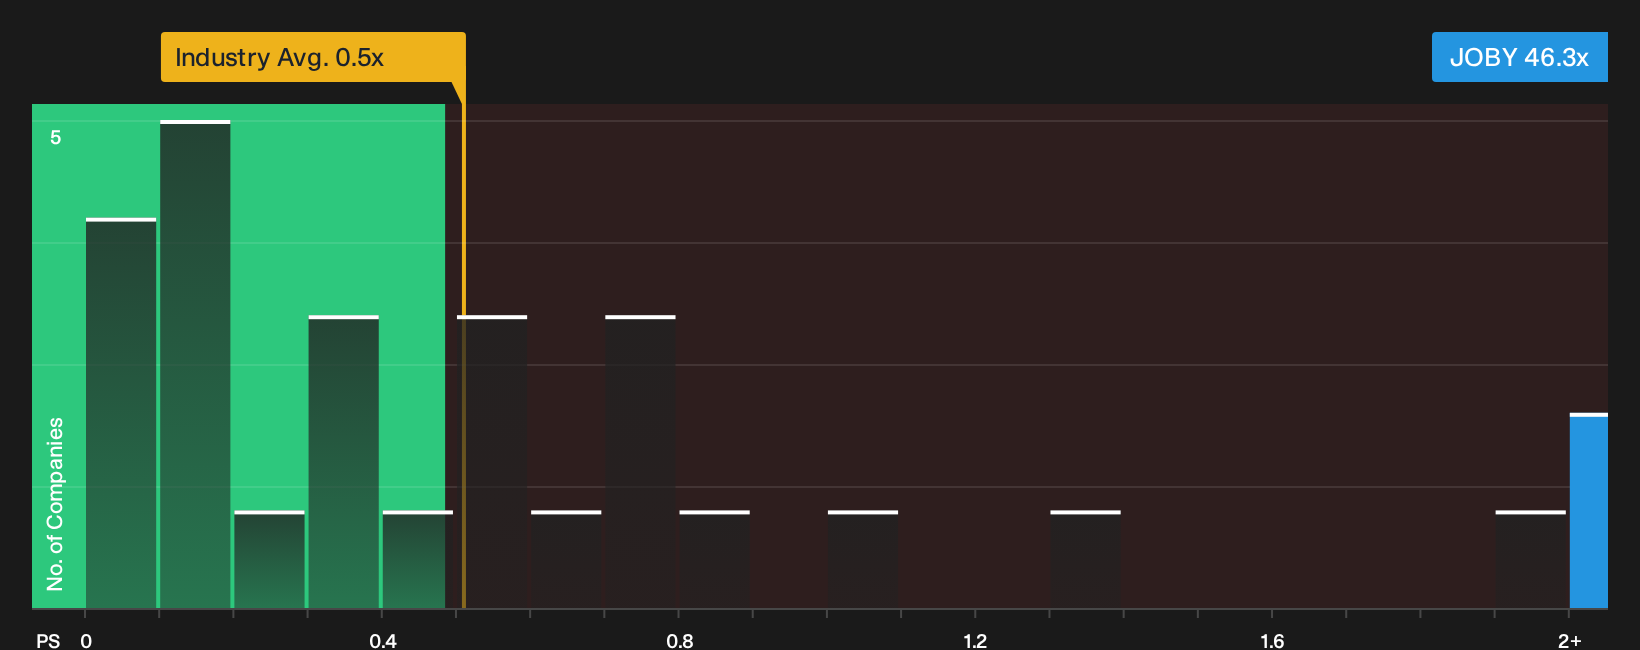
That fair value of about $10.68 paints Joby Aviation as undervalued, yet the current P/S ratio of 46.3x tells a very different story. Global airlines trade around 0.5x sales and peers average 0.7x, while the fair ratio estimate of 2.7x suggests a large valuation gap that could either compress or demand equally large execution.
See what the numbers say about this price in our valuation breakdown with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Joby Aviation is clearly divided right now, so move quickly, review both the caution and the upside, and ground your view in the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Joby Aviation?
If Joby Aviation has you rethinking your watchlist, this is the moment to widen the net and pressure test your next moves with fresh candidates.
- Scan for potential mispriced opportunities by reviewing our curated set of quality stocks on the 29 high quality undervalued stocks.
- Target resilience first by using the list of solid balance sheet and fundamentals (25 results) to focus on businesses with stronger finances backing their story.
- Hunt for less crowded opportunities by checking the 20 high quality undiscovered gems before others start paying attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com