


Exosens (ENXTPA:EXENS) Wins DOE Nuclear Supply Role, Is The Upside Already Priced In?
Client win in U.S. nuclear program puts Exosens in focus
Exosens (ENXTPA:EXENS) is drawing fresh attention after supplying high-performance neutron detectors and technical expertise to Antares Nuclear and Valar Atomics under the U.S. Department of Energy’s Reactor Pilot Program.
The detectors sit inside safety-related neutron flux monitoring systems that track reactor power and the approach to criticality during start-up and testing. This links Exosens directly to two of the program’s first reactor designs to reach this milestone.
Investors have already responded to the U.S. nuclear contract news, with Exosens posting a 1-day share price return of 6.28% and a 30-day share price return of 6.57%, while the 1-year total shareholder return of 35.03% points to momentum that has been building rather than fading.
Scan other nuclear focused opportunities by reviewing the hand picked 16 nuclear energy infrastructure stocks that focus on policy support and reactor build out themes alongside Exosens.
Exosens now appears to be a stronger nuclear equipment supplier after this U.S. win and a 35% 1-year return. The key question is whether that improved story is already fully reflected in the share price.
Most Popular Narrative: 13% Undervalued
Exosens is framed by the most followed valuation narrative as worth €67.13 per share, compared with the latest close at €58.40. This puts the current nuclear contract win into a broader growth story built on defense and sensing demand.
Exosens is ramping production capacity, notably with new facilities in the U.S. and Europe, and a 25% increase targeted by 2027. This directly addresses current supply constraints and enables the company to capture additional volumes, which could potentially boost both revenue and operating margins as scale efficiencies are realized.
See why 5 investors see Exosens as 13% undervalued.
Result: Fair Value of €67.13 (UNDERVALUED)
Still, the bullish Exosens narrative depends on smooth capacity ramp up and clean M&A integration, and setbacks on either front could quickly challenge those valuation assumptions.
Find out about the key risks to this Exosens narrative.
Another View on Exosens: High P/E, Different Signal
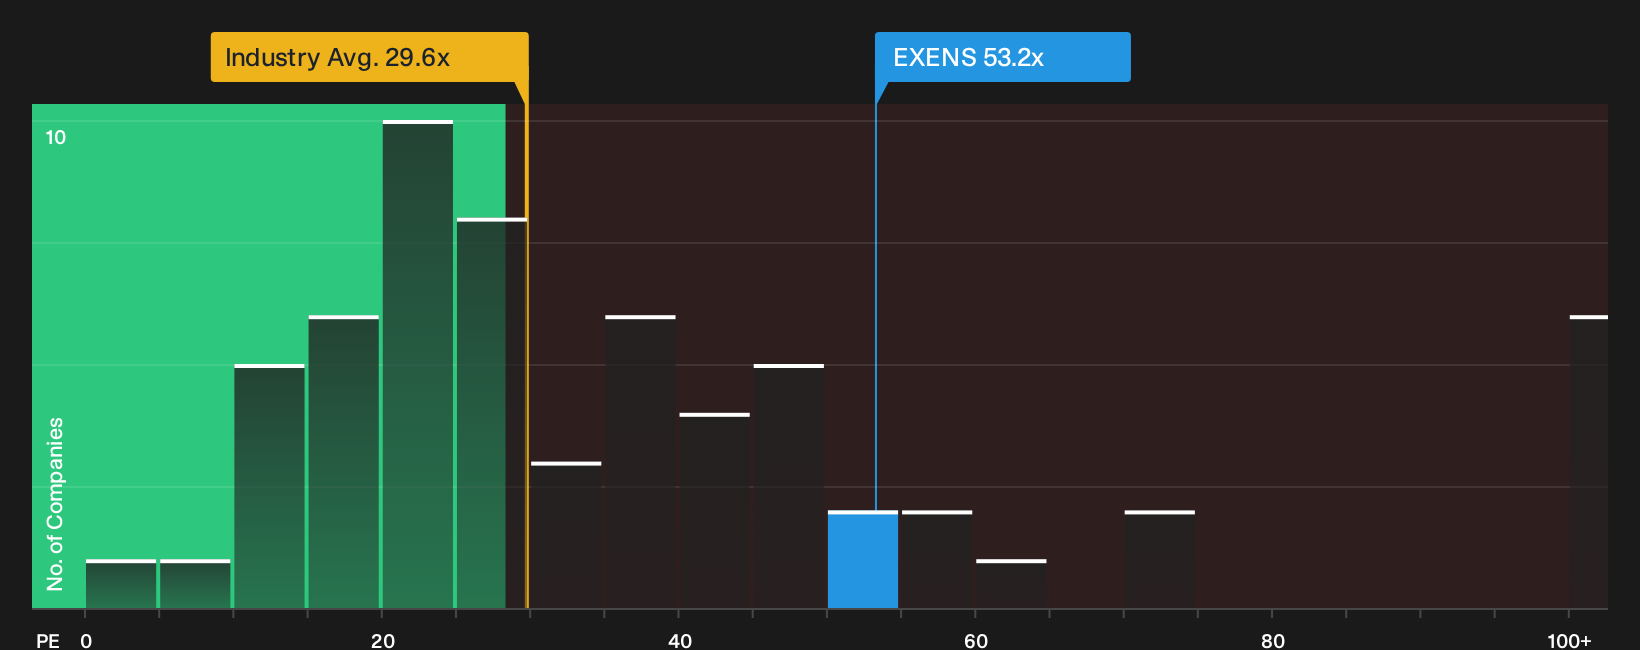
The story changes when you look at Exosens through its P/E instead of fair value models. The shares trade on 53.2x earnings, compared with a fair ratio of 26.4x, the European Aerospace & Defense average of 29.6x, and a peer average of 23.5x. That is a wide gap, and it raises the question of how much execution risk you are willing to accept if sentiment cools.
See what the numbers say about this price in our valuation breakdown, and how that compares to other stocks using the same P/E lens, in See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mix of optimism and caution on Exosens feels finely balanced, move fast to check the data for yourself and weigh both sides. To see how that trade off looks in detail, review the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Exosens?
If Exosens has your attention, do not stop here. Broader context across sectors helps you stress test any single story and sharpen your decisions.
- Spot potential bargains early by scanning companies flagged as high quality and potentially undervalued through the 178 high quality undervalued stocks.
- Strengthen your downside protection by focusing on businesses highlighted in the 223 resilient stocks with low risk scores that pair resilience with measured risk profiles.
- Hunt for under followed opportunities by reviewing the 618 high quality undiscovered gems that combine solid fundamentals with lighter market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com