


DoorDash (DASH) Could Be 23% Undervalued After Its Push Beyond Restaurant Delivery
DoorDash (DASH) just rolled out a broad set of new products and partnerships, including collaborations with Macy’s and Anthropologie, as well as DashOS software, AI tools, corporate connectors, and an in house drone delivery system.
Investors have rewarded this new push beyond restaurant delivery with a modest near term lift, with a 1 day share price return of 2.5% and a 7 day share price return of 3.9%. Yet DoorDash still carries a year to date share price return that is down 10.6% and a 1 year total shareholder return that is down 26.1%, even after a very large 3 year total shareholder return of about 1.6x. This points to strong earlier momentum that has cooled as the market reassesses how much to pay for the next leg of growth.
Compare DoorDash's push into AI and logistics with other potential breakouts by scanning our curated list of 39 profitable AI stocks that aren't just burning cash.
So is this latest 2.5% bump in DoorDash really the market waking up to a sturdier, broader business, or just sentiment snapping back after a rough year? The valuation section turns that question into numbers.
Most Popular Narrative: 23% Undervalued
On the narrative view, DoorDash's fair value sits at $256.26 against a last close of $196.50. This frames the recent share price move as relatively modest compared with a larger upside case built on new revenue lines.
Record performance of DashPass and Wolt+ subscriptions, including a recent period where DoorDash added more paid DashPass subscribers in one year than in the prior two years combined, supports a growing base of recurring, higher margin revenue and higher gross profit per MAU that can compound into earnings growth.
What is behind 80 investors see DoorDash as 23% undervalued.
Result: Fair Value of $256.26 (UNDERVALUED)
Still, two pressure points could puncture the DoorDash upside story: fresh regulatory action that raises compliance costs, and affordability pushback in grocery that caps pricing power and order volume.
Find out about the key risks to this DoorDash narrative.
Another Look At DoorDash's Price Tag
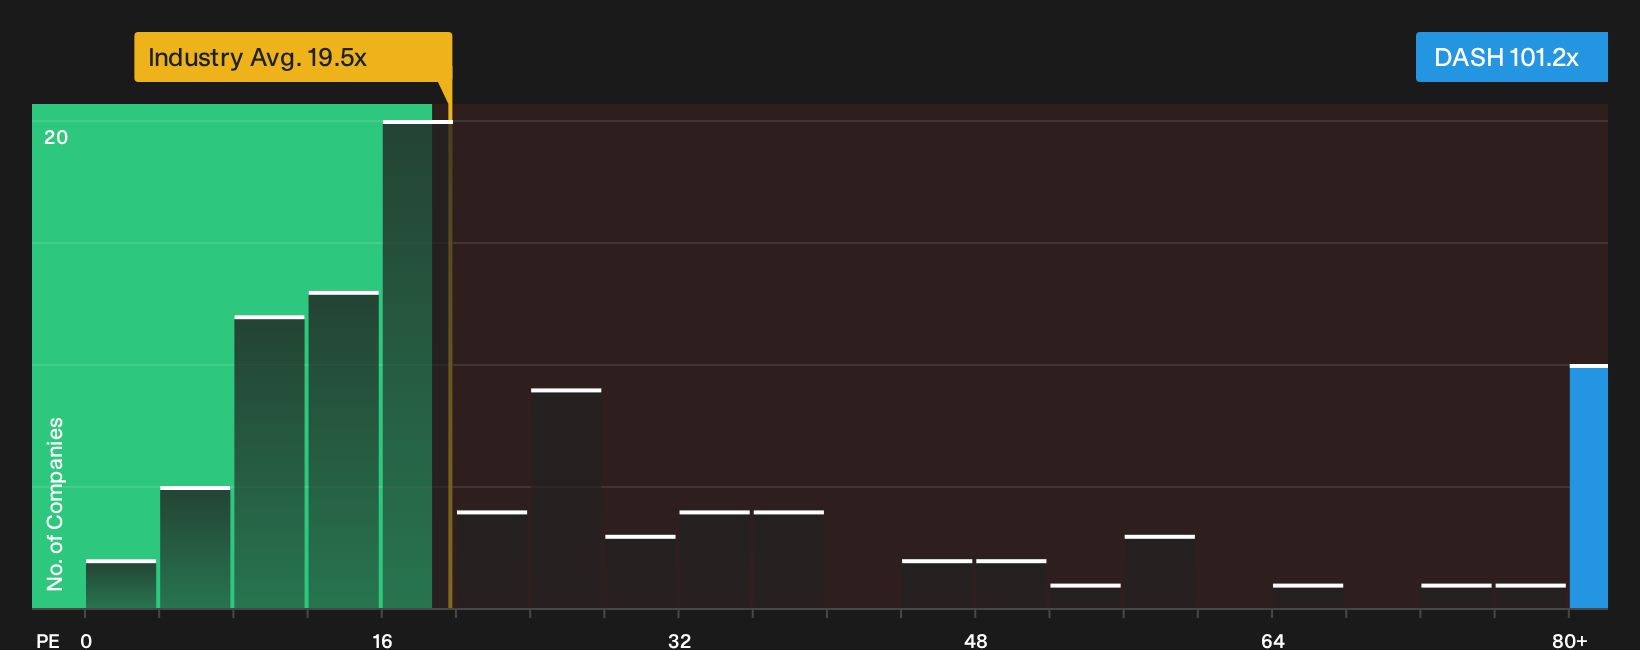
The fair value narrative frames DoorDash as 23.3% undervalued, yet the market is paying a P/E of 101.2x today. That is far above the Hospitality industry on 19.5x, the peer group on 29.3x, and even the fair ratio of 46.7x that the market could move toward over time. If sentiment cools again, how comfortable are you with that kind of valuation air pocket?
For a closer read on what those earnings multiples imply in practice, and how they stack up against peers, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on DoorDash can feel messy, so move quickly, review the same core data, and decide whether the story fits your own risk and reward balance with 4 key rewards and 1 important warning sign.
Ready To Hunt For Your Next DoorDash Sized Idea?
If the DoorDash story has you thinking more broadly about opportunities, use the Simply Wall Street Screener to quickly surface other stocks that match your own playbook.
- Target potential mispricing by scanning a focused pool of companies screened as 29 high quality undervalued stocks.
- Prioritize staying power by filtering for businesses on our list of solid balance sheet and fundamentals (25 results).
- Get ahead of the crowd by reviewing a carefully curated group of 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com