


After Panasonic's 141% Climb, The Story Has Changed
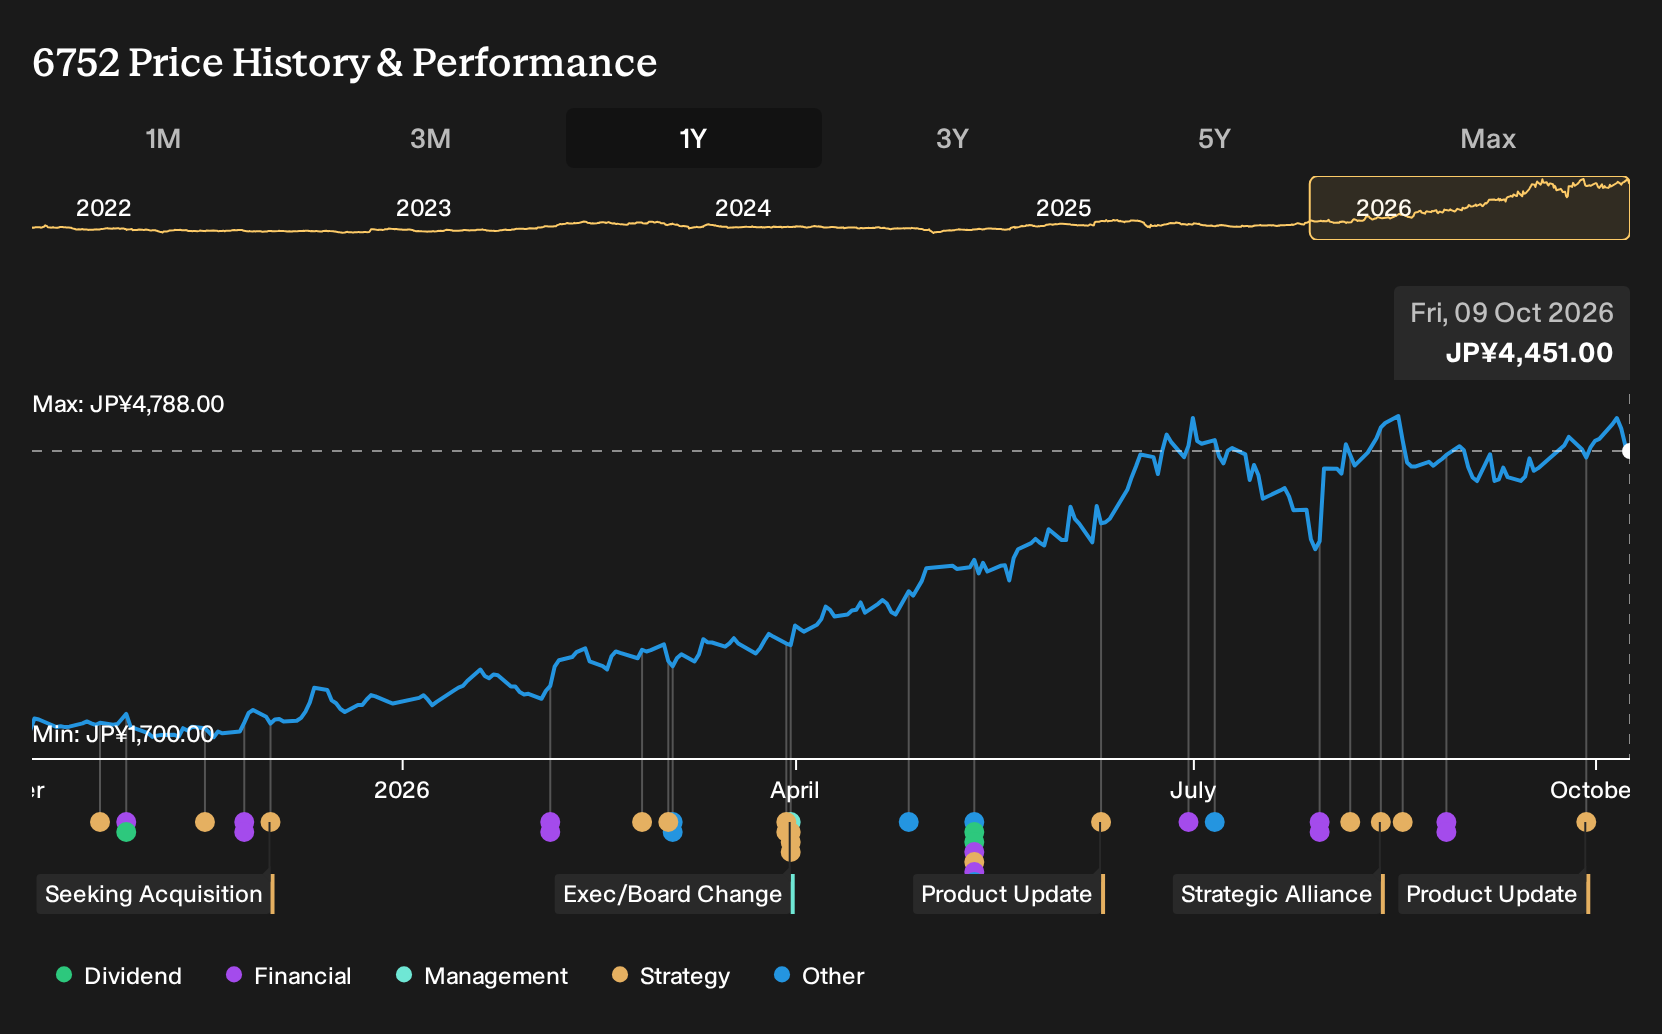
If Panasonic was on your watchlist rather than in your portfolio, the outcome over the past year may feel like a missed call. Investors who held Panasonic over the past year are up 141.3%, including dividends. That move is now being discussed alongside fresh reports of surging global demand forecasts for NMC and fast charging lithium ion batteries. The real question is whether earlier expectations about AI driven energy storage and EV related battery demand gave enough clues that this earnings power shift was possible.
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
Panasonic has already moved. Pinpoint other ways to investigate the theme among 43 power grid technology and infrastructure stocks.
The Panasonic Debate Investors Actually Faced
The shares cost ¥1,874 at the start of the period, which forced anyone looking at Panasonic to decide how much faith to place in future battery demand and restructuring plans.
The bullish Narrative put Fair Value at ¥2,036, or 9% above the start price. Supporters leaned on energy storage linked to generative AI, assuming revenue growth of 0.4%, a profit margin of 6.3% and a future P/E of 11.3x over three years.
The bearish view set Fair Value at ¥1,500, or 20% below the start price. That camp focused on a sharp slowdown in North American EV adoption and expected revenue to decline 2.3% a year even as profit margin only reached 5.1% on a future P/E of 11.1x.
What The Evidence Did To The Panasonic Argument
The clearest update landed in Panasonic’s Q1 2027 figures. Revenue moved to ¥2,018,914m and net income to ¥135,173m, with net margin at 6.7% versus 3.8% a year earlier. That profitability outcome sat closer to the bullish 6.3% margin assumption, even as reports of delayed 4680 battery mass production and frozen plant plans kept some of the bear case about EV demand alive. Overall, the evidence cut both ways.
The key lesson is about which knob mattered most. In this case it was not headline Electrification stories but whether Panasonic could lift net margin toward the forecast range. When you test another battery or energy stock, track margin progression against the thesis line and check whether capacity announcements later show up in that profitability math.
What Panasonic's Price Now Asks You To Believe
Panasonic trades at ¥4,451, a level the selected Narrative views as above its own Fair Value estimate. That stance turns on whether earnings from batteries and adjacent tech can justify the current multiple.
The Narrative highlights a tilt toward AI data center storage, while key EV projects, factory ramps and restructuring plans still need clean execution. The question for anyone paying today’s price is whether that pivot delivers enough stable profit from high fixed cost assets to support the valuation.
"Although Panasonic Holdings is reallocating automotive battery capacity toward data center storage on the back of strong AI related orders, the slower than planned ramp up at the Kansas factory and reliance on production mix optimisation to hit the 46 GWh shipment target keep a risk that future revenue from high fixed cost assets falls short of what current guidance implies, which would weigh on segment earnings and net margins."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Before The Next Story Makes Headlines
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 45% below our estimate - sells subscription tools that replace manual expense handling with integrated billing and invoice workflows.
- Company 2 - 37% below our estimate - runs outsourced communication campaigns that fold PR, social channels and events into one marketing budget.
- Company 3 - 36% below our estimate - wins complex build contracts that bundle seismic upgrades, pollution checks and long term facility upkeep.
That is three of the list. See every one of the 13 undervalued companies on it →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com