


Arm Holdings Has a $4.9 Billion Business Model on Trial. Here’s What It Means for ARM Stock.
Arm Holdings (ARM) faces a new dilemma for a company sitting at the center of the artificial intelligence (AI) boom. As its technology becomes more important, one of its biggest customers is fighting over how much it should cost. That fight is now in court.
Qualcomm (QCOM) and Arm have returned to a Delaware courtroom, with Qualcomm seeking to stop royalty payments to Arm for as long as five years. The stakes are potentially worth billions of dollars, while a separate part of the case is testing how Arm can price its newer chip architecture. Arm’s royalty business model is a major reason it can keep growing.
So what will this trial cost Arm, and does that mean it is time to dump ARM stock? Let’s find out.
Why Qualcomm’s Challenge Matters So Much to Arm?
Arm Holdings’ business model follows a simple concept. Customers pay Arm to use its technology, including CPU designs and other intellectual property. When chips using that technology are eventually shipped, Arm generally receives a royalty. This business model gains traction as Arm's architecture spreads into high-volume markets. If more chips are made using Arm’s technology, the royalty opportunity will keep growing.
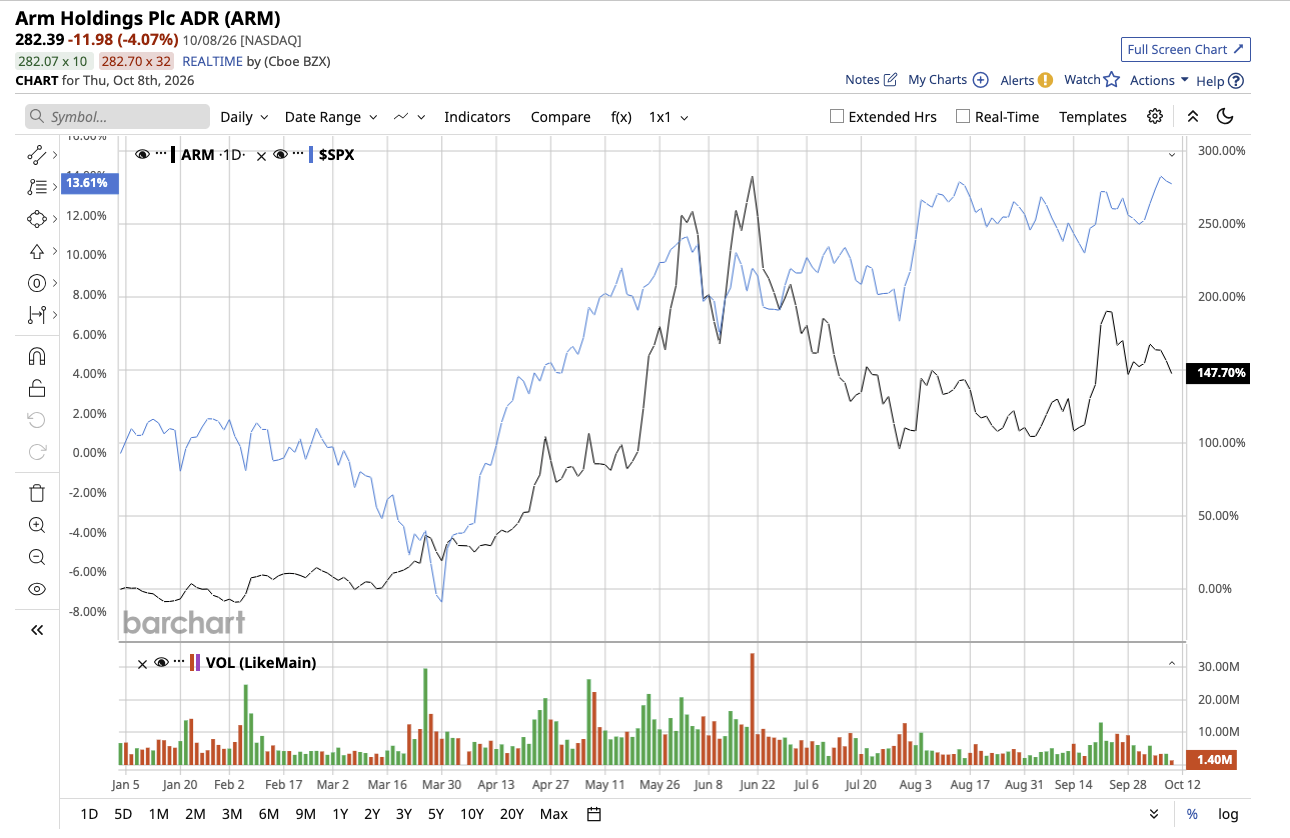
ARM stock’s roughly 148% YTD rally shows that, despite the trial, investors have not abandoned the Arm growth story. This is because Arm generated $4.92 billion of revenue in fiscal 2026, an increase of 23% year over year (YOY). Royalty revenue was $2.61 billion, while licensing revenue reached $2.31 billion. Both businesses grew more than 20% from the year earlier.
Qualcomm is one of Arm's largest customers, having licensed Arm's CPU design for use in its Snapdragon CPUs. Qualcomm is essentially turning to the court for relief that will allow it to stop paying Arm royalties for up to five years.
The Dispute Is Really About Arm's Pricing Power
Qualcomm is challenging how Arm has sought to negotiate pricing for its next-generation architecture. According to Reuters, during the proceedings, Qualcomm's side highlighted an alleged 18,500% increase in royalty rates between Arm's version 9 and version 10 architecture. Qualcomm's older agreement with Arm dates back to 2013, which included a royalty cap of $1.88 per chip for chips with at least five CPU cores. Arm's lawyers questioned whether that arrangement still makes economic sense in a market where some modern data-center processors can contain hundreds of CPU cores.
This makes sense as Arm is no longer operating in a world where its technology is primarily associated with just small smartphone processors. Its architecture is moving deeper into servers, AI infrastructure, automotive systems, edge computing, and other increasingly valuable workloads.
If Arm can successfully charge more for increasingly sophisticated technology, the royalty business model becomes much more powerful. However, if each of its major customers, like Qualcomm, starts challenging it to pay the older, lower rates as chips become more advanced, Arm’s long-term growth story could be constrained.
What the Qualcomm Trial Means for ARM Stock
For now, Arm’s financial performance gives investors some breathing room. The company’s momentum from fiscal 2026 continued into its June quarter. In the first quarter of fiscal 2027, revenue reached $1.29 billion, up 22% from the year-ago quarter. Royalty revenue climbed 22% YOY to $715 million, while licensing revenue rose 23% to $574 million. Adjusted earnings per share increased 29% year over year to $0.45.
Concerning royalty revenue, management highlighted that data center royalty revenue more than doubled year over year in the June quarter. That implies that the company is gradually becoming less dependent on the traditional smartphone market and gaining exposure to a much larger AI infrastructure opportunity. So the main concern for Arm currently is that Qualcomm's case will limit its ability to boost royalty prices as chips get more complex. Qualcomm wants to withhold royalty payments for up to five years, and a verdict against Arm might affect how the company negotiates with other big clients. However, if Arm successfully defends its contracts and pricing model, the trial may boost the company's capacity to capitalize on the expansion of AI and data-center computing.
Should Investors Dump ARM Stock Now?
The Qualcomm trial is certainly a real threat to Arm’s royalty model, but that doesn’t mean it’s time to sell ARM stock. Arm’s revenue and royalty business continue to grow, and the expanding data center opportunity offers a significant source of growth for the company. Unless the court ruling materially weakens Arm’s ability to collect royalties or price its newer technology, the trial is more of a risk that investors need to watch than a reason to abandon the stock.
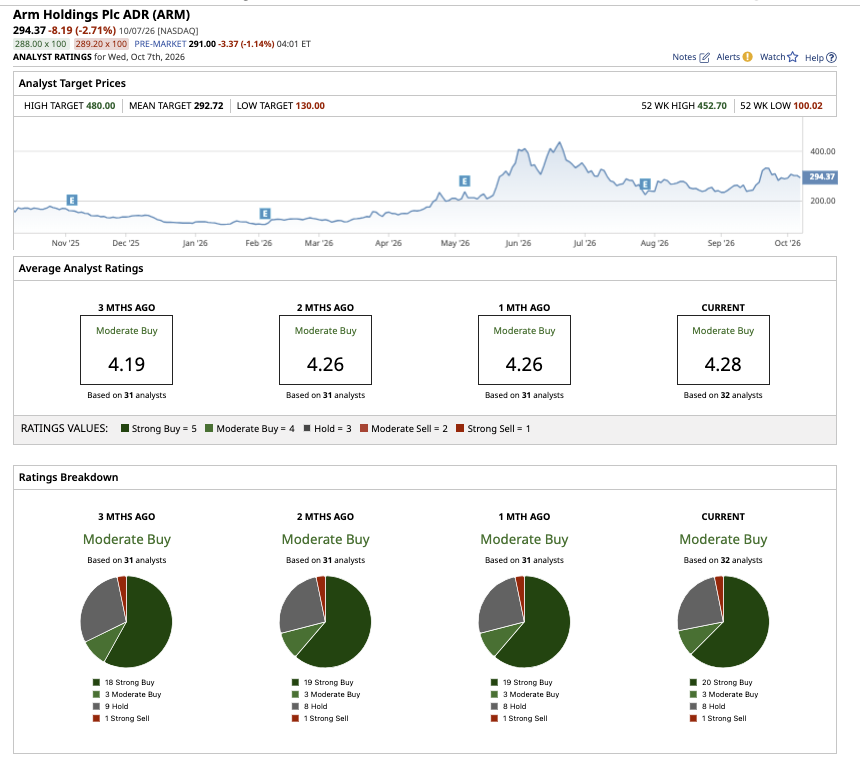
For now, ARM stock still holds a consensus “Moderate Buy” rating on Wall Street. Among the 32 analysts covering the stock, 20 rate it as a “Strong Buy,” three say it is a “Moderate Buy,” eight rate it a “Hold,” and one recommends a “Strong Sell.” The stock has surpassed its average target price of $292.72, while the highest price estimate of $480 indicates a possible 63% rally over the next 12 months.
On the date of publication, Sushree Mohanty did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.