


What Investors Overlooked Before AIXTRON's 181% Run
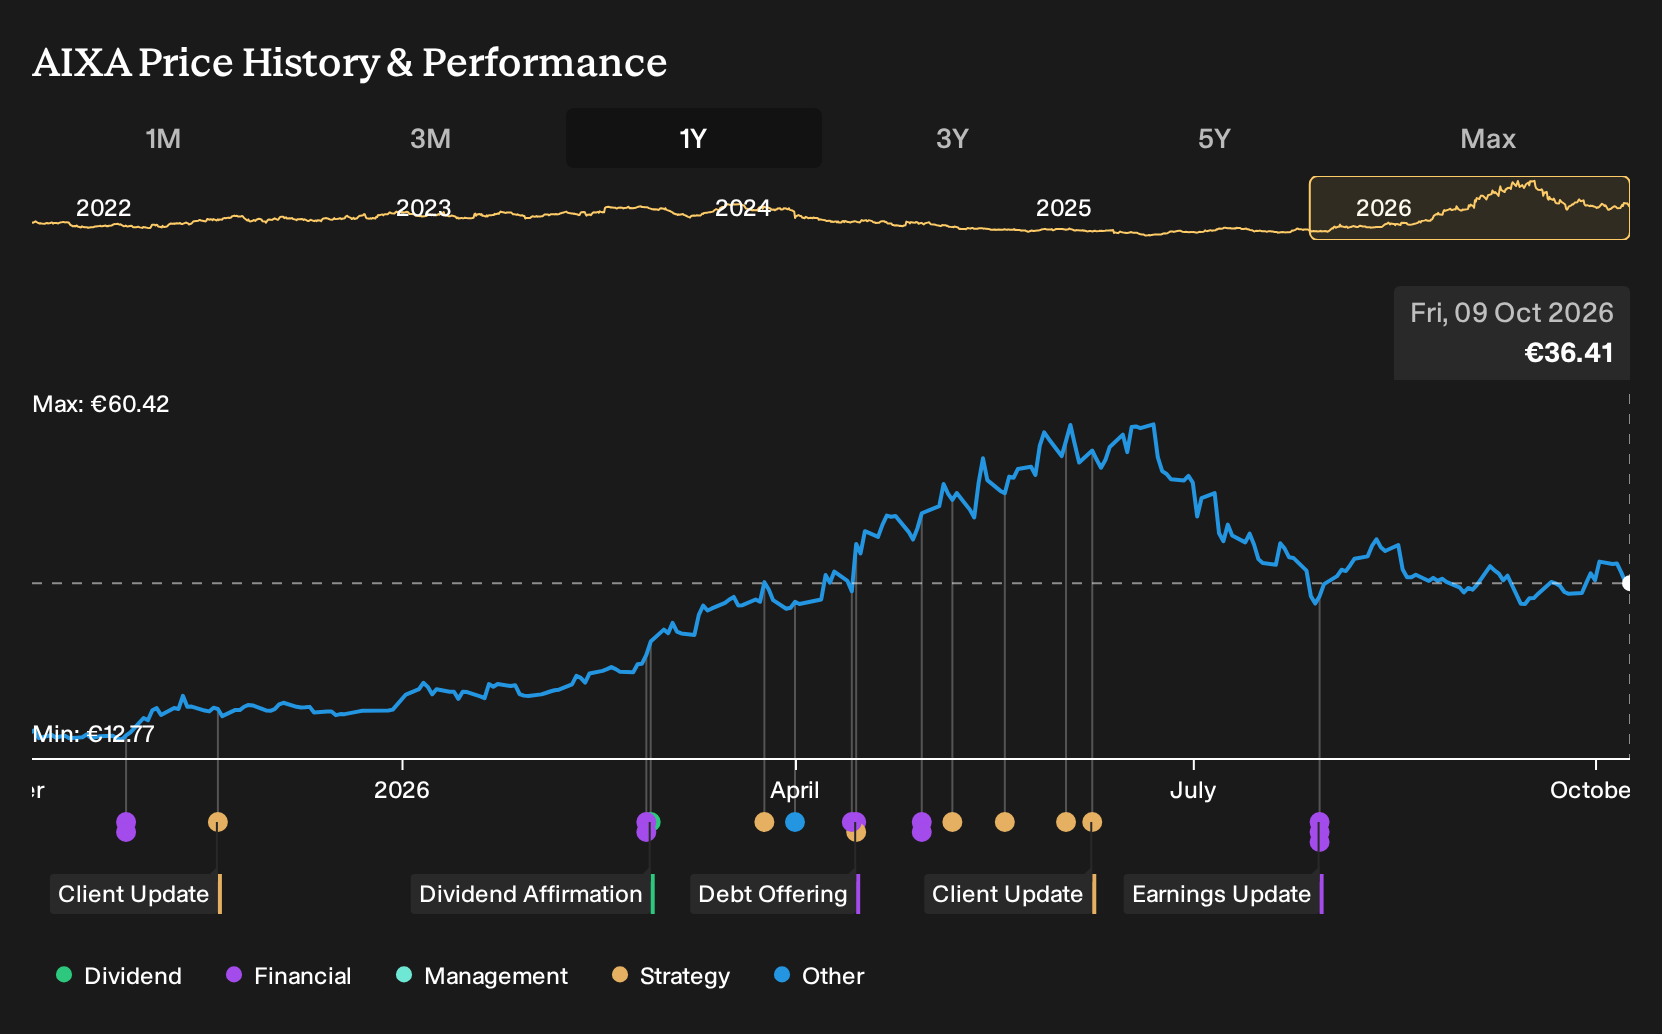
AIXTRON’s year pivoted around one concrete shift, the surge in orders for its optoelectronics tools tied to AI data center build outs, while its SiC equipment line faced a tougher backdrop. Investors who held AIXTRON over the past year are up 180.9%, including dividends. If you had been deciding whether to buy on 9 October 2025, what exactly did you need to believe about those diverging engines of demand?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
This theme extends beyond AIXTRON. See which of 92 AI infrastructure stocks may still merit a closer look.
The Argument You Would Have Been Weighing Up On AIXTRON
The shares cost €14.2 at the start of the period, so any view on AIXTRON hinged on which story you thought was more realistic.
On the optimistic side, the bull narrative put Fair Value at €15.96. That required confidence that optoelectronics demand tied to lasers and AI data centers would support AIXTRON's G10 tools, and that recurring service income from a wider installed base would keep earnings more stable.
The bearish view anchored Fair Value at €10.9. That mindset focused on the risk that severe silicon carbide overcapacity would drag on new tool orders, and that rising China based competitors could pressure margins and market share.
What The AIXTRON Evidence Actually Showed
The clearest data point came from guidance. AIXTRON raised its 2026 outlook after strong AI linked optoelectronics demand and Q1 2026 orders that were 30% higher year on year, with over 65% tied to that segment, which backed the optimistic case. Reported Q2 2026 numbers told a cooler story, with revenue and profit both lower than Q2 2025 even as net margin rose to 16.6%. Overall, the evidence cut both ways.
The main lesson for readers is simple. When an idea rests on one growth engine carrying the rest, as AIXTRON did with optoelectronics, track order intake mix and segment guidance, not just aggregate revenue or headline earnings per share, to see whether that engine is actually pulling harder than the weaker line of business.
What AIXTRON’s Run Leaves You Paying For Now
AIXTRON trades at €36.41 after a 180.9% gain over the past year. The selected Narrative’s Fair Value sits above the current price and leans on AI driven optoelectronics demand plus compound semiconductor adoption as the main profit engines.
On that view, today’s quote still underplays how much recurring service income from a larger G10 installed base could reshape earnings stability.
"Growth in optoelectronics and advanced semiconductor adoption positions AIXTRON's G10 tools for strong sales, global market leadership, and expanding profit margins. Diversified customer base and recurring service revenue enhance earnings stability and support sustained, long-term profitability despite current market headwinds."
The price and this Narrative do not agree. → Uncover what this Narrative says AIXTRON is actually worth
Another Side To AI Demand
AIXTRON highlights how AI hardware spending can reshape one supplier’s order book. Look one step away and the need can appear even larger.
All that compute power relies on specialised racks that soak up electricity and capital. Those systems keep arriving as long as model builders pursue greater capability.
One large chip designer has built its story around that cycle. It pushes new processors and a tightly linked software stack that encourages continual upgrades.
Your question is simple. If that upgrade treadmill keeps turning, what happens to the company selling the priciest racks in the room?
One Narrative has already put a figure on it. → Uncover the company trading 33% below one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com