


Archrock (AROC) Just Gave Investors Something To Think About
Leadership change as a fresh lens on Archrock
Archrock (AROC) investors just got a governance update. Vice President and Chief Accounting Officer Donna A. Henderson plans to retire on December 4, 2026, a shift that puts financial oversight and succession planning in sharper focus.
Archrock’s recent executive news comes as the share price sits at US$30.28, following a pullback, with a 30 day share price return of 7.6% and a 90 day share price return of 20.52%. Longer term total shareholder returns over three and five years, at 158.11% and 340.64% respectively, indicate that investors have been well rewarded even through shorter term swings.
Capitalize on the governance spotlight at Archrock by scanning a curated 31 resilient stocks with low risk scores that may offer similarly resilient balance sheets and steadier business profiles.After a sharp run over the past year and a recent pullback to US$30.28, Archrock now forces a timing call. Is this price already fair, or does patience still pay?
Most Popular Narrative: 32.5% Undervalued
On the most followed narrative, Archrock screens as materially mispriced, with a fair value of $44.88 set against the last close of $30.28.
Archrock, Inc. (NYSE: AROC), a leading outsourced natural gas compression service provider in the United States, has built a unique moat to meet this structural demand with its 4.5 million horsepower (HP) capacity, electric motor drive (EMD) vision, and strategic acquisitions. Archrock''s compression services and aftermarket maintenance operations have transformed the company into an infrastructure monopoly that isolates itself from commodity price volatility, generating predictable cash flows and protected by contracts spanning decades.
See why 43 investors see Archrock as 33% undervalued.
Result: Fair Value of $44.88 (UNDERVALUED)
Still, the Archrock narrative can be knocked off course if compression engine supply constraints ease faster than expected, or if data center gas demand grows more slowly than modeled.
Find out about the key risks to this Archrock narrative.
Another View on Archrock’s Valuation
The user narrative pegs Archrock’s fair value at $44.88, which points to heavy undervaluation at the recent $30.28 share price. The SWS DCF model paints a stricter picture. On that framework, Archrock screens as overvalued, with future cash flows implying a value of $24.24.
This gap between a cash flow based estimate and the market price raises a simple question for investors. Is the cash generation profile too conservative, or are the narrative assumptions around compression demand and contract longevity too optimistic?
Look into how the SWS DCF model arrives at its fair value.
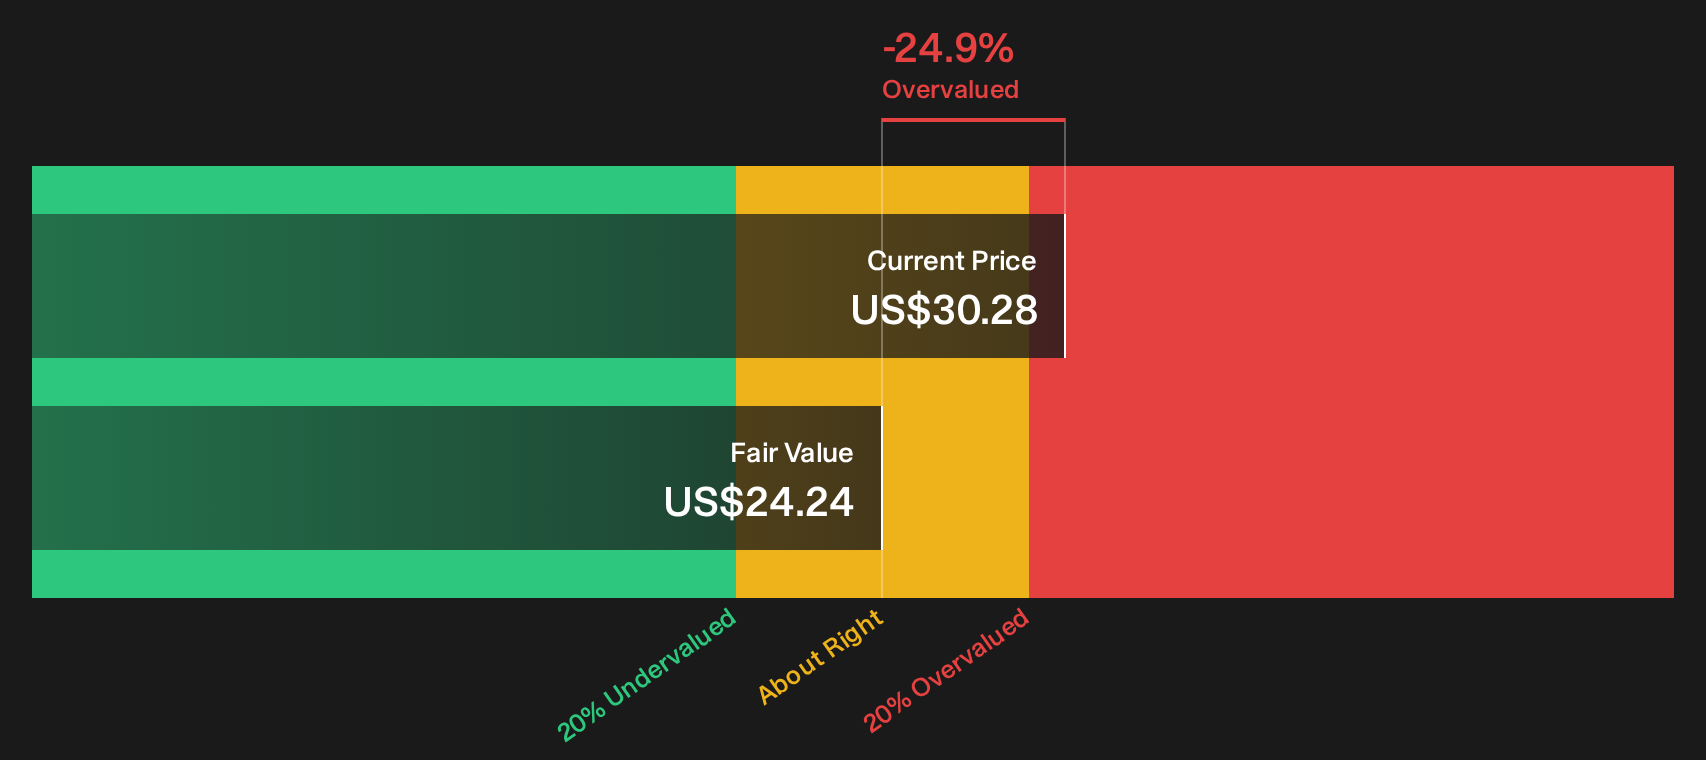
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Archrock for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Archrock’s value and risks create plenty to think about, so move quickly, review the underlying data, and weigh the 5 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Archrock?
If Archrock has sharpened your thinking, do not stop here. Broaden your watchlist with a few targeted idea lists built from the Simply Wall Street Screener.
- Spot potential value opportunities early by reviewing a focused 29 high quality undervalued stocks that filters for quality fundamentals and pricing that may not fully reflect them.
- Strengthen your defense by scanning a list of solid balance sheet and fundamentals (25 results) that prioritizes robust finances and sturdier capital structures when conditions turn rough.
- Hunt for under-the-radar potential with a curated 20 high quality undiscovered gems that highlights quieter stories before they attract wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com