


Magnolia Oil & Gas (MGY), What Is Behind The Latest Attention?
Magnolia Oil & Gas (MGY) just paired fresh production guidance with a strong quarter that topped revenue and EPS expectations, which puts the stock’s recent moves in sharper focus for investors watching US exploration and production names.
Recent price action has been choppy. The share price is down about 13% over the past 30 days and roughly 10% over the last 90 days, even though the year to date share price return is 7.21% and the 1 year total shareholder return is 9.25%.
Compare Magnolia Oil & Gas against other potential opportunities and scan a focused set of resilient energy producers using the 31 resilient stocks with low risk scores.
Magnolia Oil & Gas now trades well below both analyst targets and one estimate of intrinsic value, after a solid quarter and fresh guidance. Is the current share price discounting too much or not enough?
Most Popular Narrative: 26% Undervalued
Magnolia Oil & Gas closed at $24.10 while the most followed narrative pegs fair value at $32.75. This frames the recent share price weakness as a potential gap between expectations and current pricing.
The WildFire Energy acquisition, which brings the pro forma Giddings position to nearly 1.3 million net acres and materially increases proved developed reserves, gives Magnolia Oil & Gas a longer high quality resource base that can underpin future earnings and cash flow.
See why 12 investors see Magnolia Oil & Gas as 26% undervalued.
Result: Fair Value of $32.75 (UNDERVALUED)
Still, the Magnolia Oil & Gas story depends on WildFire delivering cost savings and on EBITDA margins stabilising rather than slipping further from recent levels.
Find out about the key risks to this Magnolia Oil & Gas narrative.
Another View: What Magnolia Oil & Gas Looks Like On Earnings Multiples
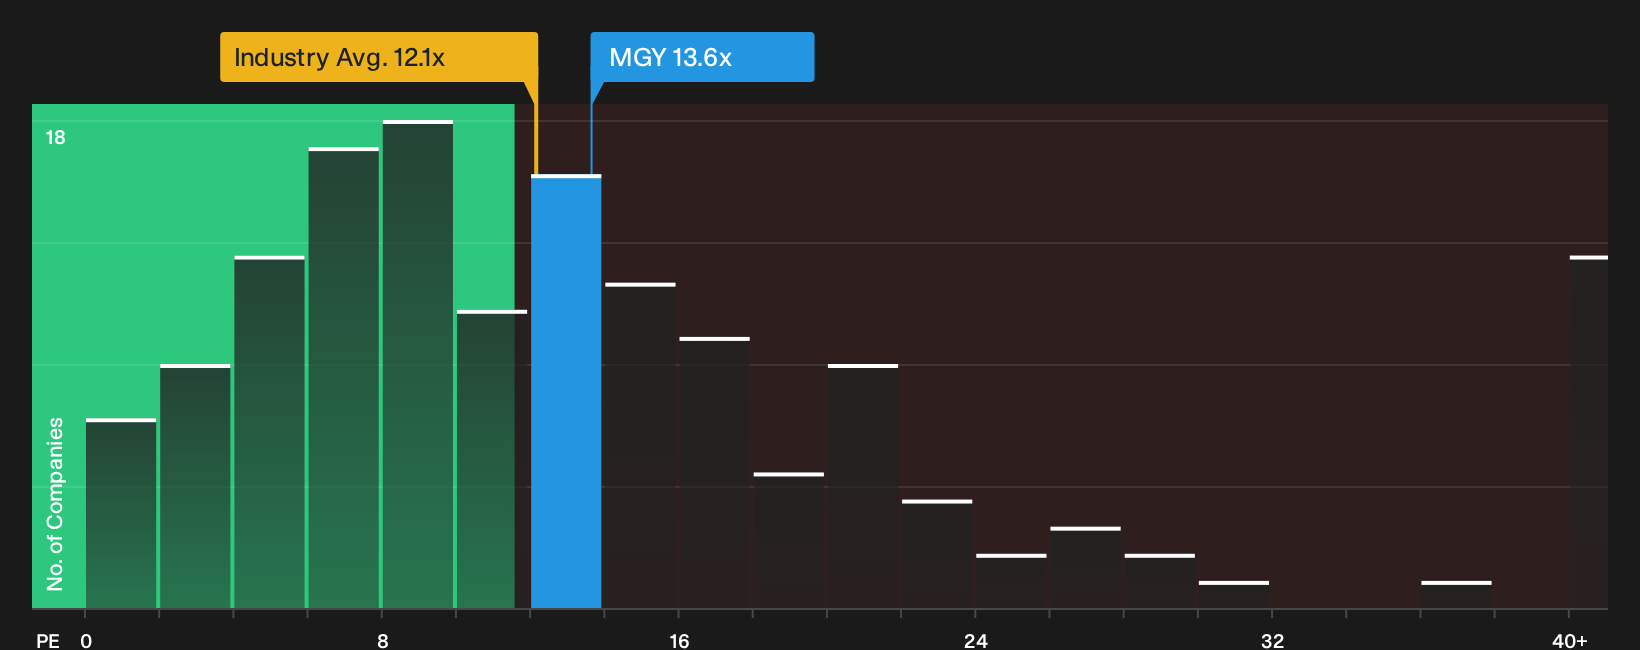
The fair value story for Magnolia Oil & Gas hinges on a narrative price of $32.75, yet the current P/E of 13.6x complicates that picture. That multiple is higher than both US Oil and Gas peers at 10.3x and the wider industry at 12.1x, while still below the 18.1x fair ratio the model suggests the market could move toward. For investors, that mix of premium versus today’s comparables and discount versus the fair ratio raises a simple question: Is this paying up for quality or taking on valuation risk if expectations cool?
See what the numbers say about this price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
That mix of discounted fair value, richer P/E, and the WildFire integration leaves Magnolia Oil & Gas with a split scorecard that investors need to interpret for themselves. Move quickly, review the full picture of potential upsides and flagged issues, and weigh the 3 key rewards and 1 important warning sign.
Looking for more Magnolia Oil & Gas style ideas?
If Magnolia Oil & Gas has your attention, do not stop here. Fresh opportunities routinely surface when you widen your view beyond a single ticker.
- Target resilient value by scanning a curated pool of financially strong bargains through the 29 high quality undervalued stocks.
- Focus on staying power by filtering for companies with robust finances using the list of solid balance sheet and fundamentals (25 results).
- Hunt for overlooked potential by checking a tight group of strong fundamental stories in the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com