


Mitsubishi Estate (TSE:8802) Looks Fully Valued On Singapore Riverfront Joint Venture
Mitsubishi Estate (TSE:8802) has expanded its overseas footprint through a 51:49 joint venture with Frasers Property to redevelop a heritage riverfront site in Singapore’s District 10 into a mixed-use project.
Recent trading tells a mixed story for Mitsubishi Estate. The share price is ¥3,465.0 after a 1-day share price return of 0.67%, yet the 90-day share price return is down 17.09% and the year-to-date share price return is down 10.16%. At the same time, the 5-year total shareholder return of 113.46% points to stronger long-run rewards and indicates that momentum has cooled in the short term, while the longer history still reflects meaningful value creation for patient investors.
Scan beyond Mitsubishi Estate and explore this Singapore riverfront story by comparing it with 74 high quality undiscovered gems that analysts may be missing in real estate and adjacent sectors.
Mitsubishi Estate trades at a sizeable discount to analyst targets even after the buyback and Singapore joint venture news. Is this genuine mispricing or a fair warning label on execution and cycle risk?
Price-to-Earnings of 14.6x: Is it justified?
Mitsubishi Estate trades on a P/E of 14.6x, which sits above both the JP Real Estate industry and its peer group, while the last close is ¥3,465.
The P/E ratio compares the current share price to earnings per share and effectively shows how much investors are willing to pay for each unit of profit. For a diversified property group with office, residential, logistics, and overseas projects, that figure often reflects how much faith the market has in the durability of earnings through property cycles.
Earnings growth of 46.3% over the past year, an 11.1% per year record over five years, and higher net profit margins of 15.2% compared with 12.1% previously line up with a richer P/E. At the same time, forecasts point to earnings growth of 1.8% per year and revenue growth of 3.8% per year, which is slower than the wider JP market, so the market could be paying up more for quality and scale than for rapid expansion. The estimated fair P/E of 16x is above the current 14.6x, which indicates the valuation multiple may have room to move closer to that level if investors remain comfortable with earnings resilience.
Compared with the JP Real Estate industry average P/E of 9.6x and a peer average of 11.9x, Mitsubishi Estate trades at a clear premium. The gap suggests investors are assigning a higher value to its earnings than to the typical sector player and to its closest peers, and that premium appears consistent with the fair P/E estimate that sits even higher than the current market multiple.
Explore the SWS fair ratio for Mitsubishi Estate.
Result: Price-to-Earnings of 14.6x (ABOUT RIGHT)
Still, the Mitsubishi Estate story can be knocked off course if Singapore redevelopment returns disappoint or if broader property cycle weakness affects earnings quality.
Find out about the key risks to this Mitsubishi Estate narrative.
Another View: Mitsubishi Estate Through A Cash Flow Lens
The P/E workup paints Mitsubishi Estate as roughly fairly valued against its own fair ratio, yet our DCF model lands in a slightly different spot. On a cash flow basis, the shares trade at ¥3,465 compared with an estimated future cash flow value of ¥3,449.89, which points to a small premium rather than a clear discount. For an investor, that kind of narrow gap raises a simple question: is this still a margin of safety or just a full price for quality?
Look into how the SWS DCF model arrives at its fair value.
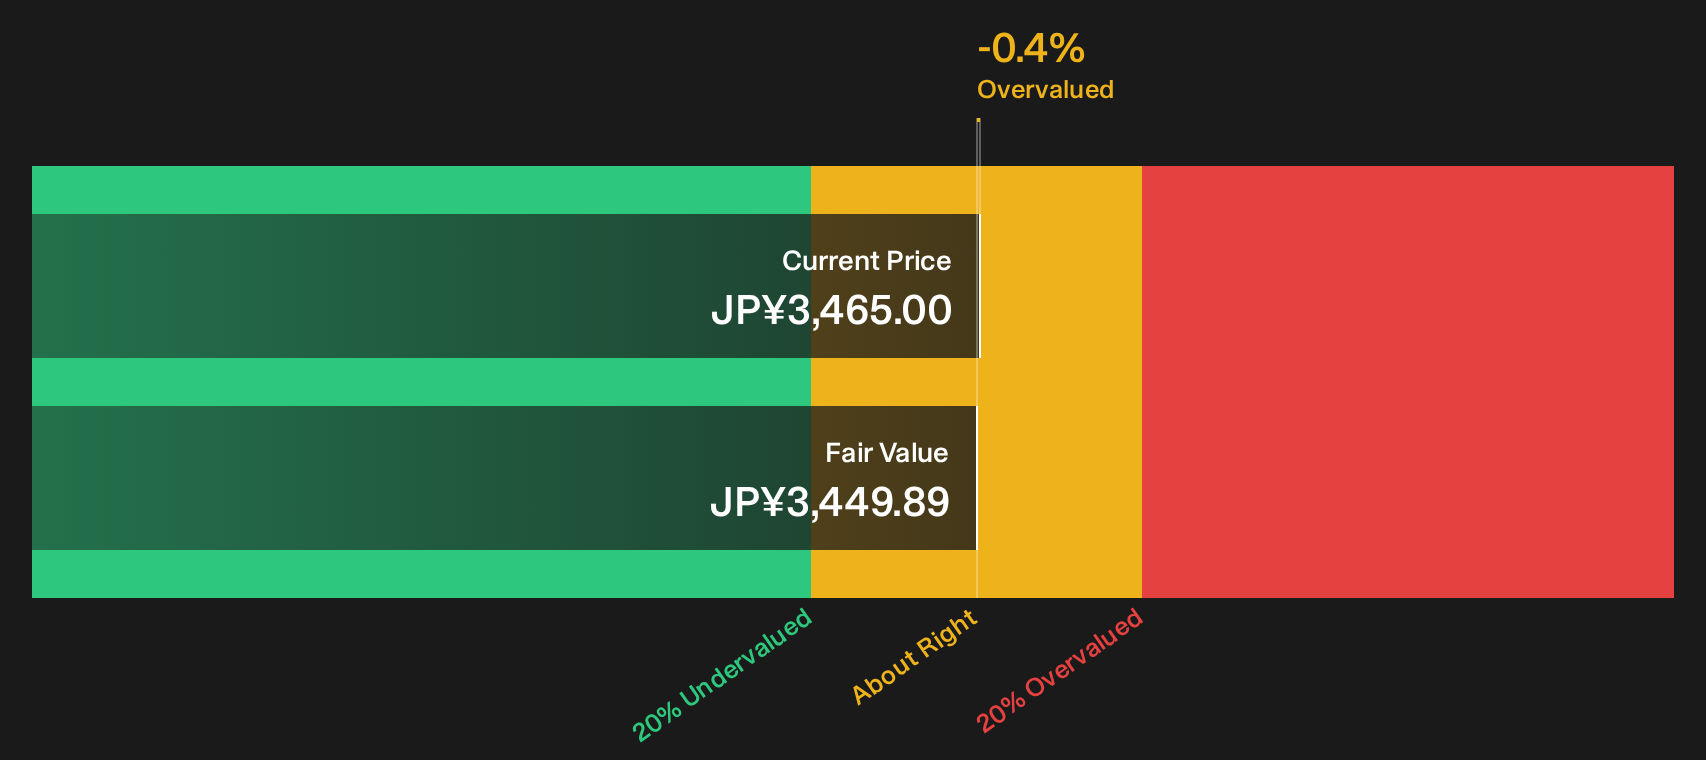
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mitsubishi Estate for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the picture on Mitsubishi Estate still feels mixed to you, that is the point. It is a signal to dig into the full risk reward balance yourself with the 3 key rewards and 2 important warning signs
Looking for more Mitsubishi Estate sized ideas?
If Mitsubishi Estate has caught your attention, do not stop here. There are other opportunities on Simply Wall Street’s screener that could fit your style just as well.
- Target potential mispricing by scanning a curated pool of quality companies trading below fair value with the 13 high quality undervalued stocks.
- Strengthen your income stream by focusing on businesses that offer higher yields in the 28 dividend fortresses.
- Dial down portfolio stress by concentrating on companies with robust fundamentals in the 23 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com