


Champion Homes (SKY) Could Be 23% Undervalued As Housing Policy Support Builds
Recent trading and business snapshot
Champion Homes (SKY) trades around $79.63 after a mixed stretch in the market, with the share price down over the past week, month, and past 3 months but higher across the past year.
The manufacturer of factory-built housing in the U.S. and Canada reports revenue of about $2.67b and net income of roughly $191.37m, giving investors a sense of the current scale of its operations.
Recent trading around $79.63 reflects short term selling pressure, with the share price down over the past week and month. At the same time, the 1 year total shareholder return of about 23.9% points to longer term investors still sitting on gains and reassessing Champion Homes’ risk and growth profile.
Scan how Champion Homes compares with other factory-built housing and consumer durables players by reviewing our curated list of 29 high quality undervalued stocks.
Champion Homes now trades well below both analysts’ targets and an estimated fair value, even after a solid 1 year return. Is that a genuine margin of safety, or a warning that the market’s caution is warranted?
Most Popular Narrative: 23% Undervalued
On the most followed view, Champion Homes is worth about $103.50 a share, compared with the recent $79.63 trading level. This perspective places significant emphasis on how policy support, retail expansion, and the order book translate into future cash flows under an 8.28% discount rate.
Increasing national focus on housing affordability and supportive policy momentum, now reinforced by the 21st Century ROAD to Housing Act becoming law in July 2026 and modernizing rules for HUD-code homes, is expected to drive structural demand for manufactured housing and support Champion Homes volumes and revenue over time.
See why 5 investors see Champion Homes as 23% undervalued.
Result: Fair Value of $103.50 (UNDERVALUED)
Still, Champion Homes faces real pressure if buyers continue shifting toward lower priced community and independent channels, while elevated material costs squeeze gross margins longer than analysts expect.
Find out about the key risks to this Champion Homes narrative.
Another view on Champion Homes valuation
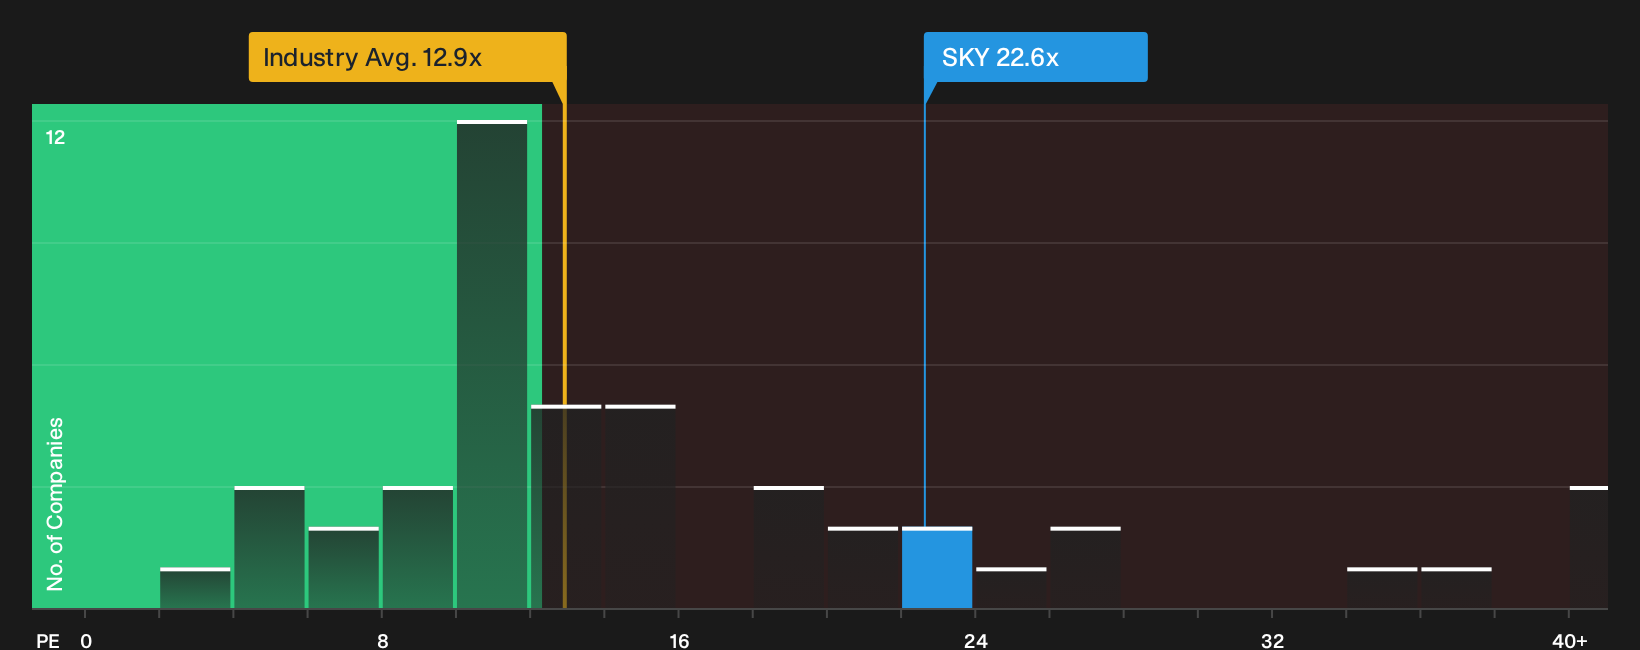
The first narrative leans heavily on discounted future cash flows. On a more plain-vanilla P/E lens, Champion Homes looks expensive, trading around 22.6x earnings versus about 16x for peers and a fair ratio of 18.2x that the market could move toward over time.
This gap matters because if sentiment cools or earnings progress falls short of expectations, a move closer to that 18.2x fair ratio could put pressure on the share price, even if the long term housing story stays intact. Which yardstick do you trust more for your own framework: the cash flow model, or what comparable stocks are trading at right now?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted by the split between discounted cash flow optimism and rich P/E multiples for Champion Homes. Act quickly, review the underlying drivers yourself and pressure test the 3 key rewards.
Looking for more investment ideas beyond Champion Homes?
Do not stop your research with Champion Homes. Fresh opportunities often sit just outside your current watchlist, and a few targeted screens can quickly broaden your options.
- Target potential value plays by scanning companies that screen as 29 high quality undervalued stocks and see which ones merit a deeper look.
- Strengthen your focus on resilience by checking out a list of solid balance sheet and fundamentals (25 results) that can better withstand tougher conditions.
- Hunt for overlooked potential by reviewing a curated group of 20 high quality undiscovered gems before they attract wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com