


Is Almirall (BME:ALM) Still Below Fair Value As Lebrikizumab Data Builds Confidence?
Fresh long term data on lebrikizumab, unveiled at the EADV Congress, has pushed Almirall (BME:ALM) back into focus for investors watching dermatology focused drug developers.
The new lebrikizumab data comes at a time when Almirall’s 1-year total shareholder return has fallen about 14.8%, while the 3-year total shareholder return is positive, and the share price return year to date is down about 21.9%. This suggests that sentiment has cooled despite a busier period for clinical results and congress activity.
Compare Almirall’s dermatology focus with a hand picked group of companies delivering strong cash flows and balance sheet support in the 178 high quality undervalued stocks.
Almirall’s share price has given up ground even as lebrikizumab data and the broader dermatology pipeline gain visibility. At around €10, is most of the rerating already spent, or is the valuation still catching up?
Most Popular Narrative: 31% Undervalued
On the most followed view, Almirall’s estimated fair value of €14.58 sits well above the last close at €10.08. This puts fresh lebrikizumab data into a valuation framework that leans on the whole dermatology portfolio rather than a single trial readout.
Strong and sustained expansion of the dermatology portfolio (notably Ebglyss and Ilumetri) is supported by growing prevalence of chronic skin and autoimmune diseases due to demographic shifts. Aggressive pipeline launches and label expansions are expected to drive double-digit net sales growth through 2030.
See why 14 investors see Almirall as 31% undervalued.
Result: Fair Value of €14.58 (UNDERVALUED)
Still, Almirall’s heavy reliance on Ilumetri and Ebglyss, alongside pressure on biologic margins and pricing, could quickly weaken the case for a 31% undervaluation.
Find out about the key risks to this Almirall narrative.
Another View: Multiples Paint A Tougher Picture For Almirall
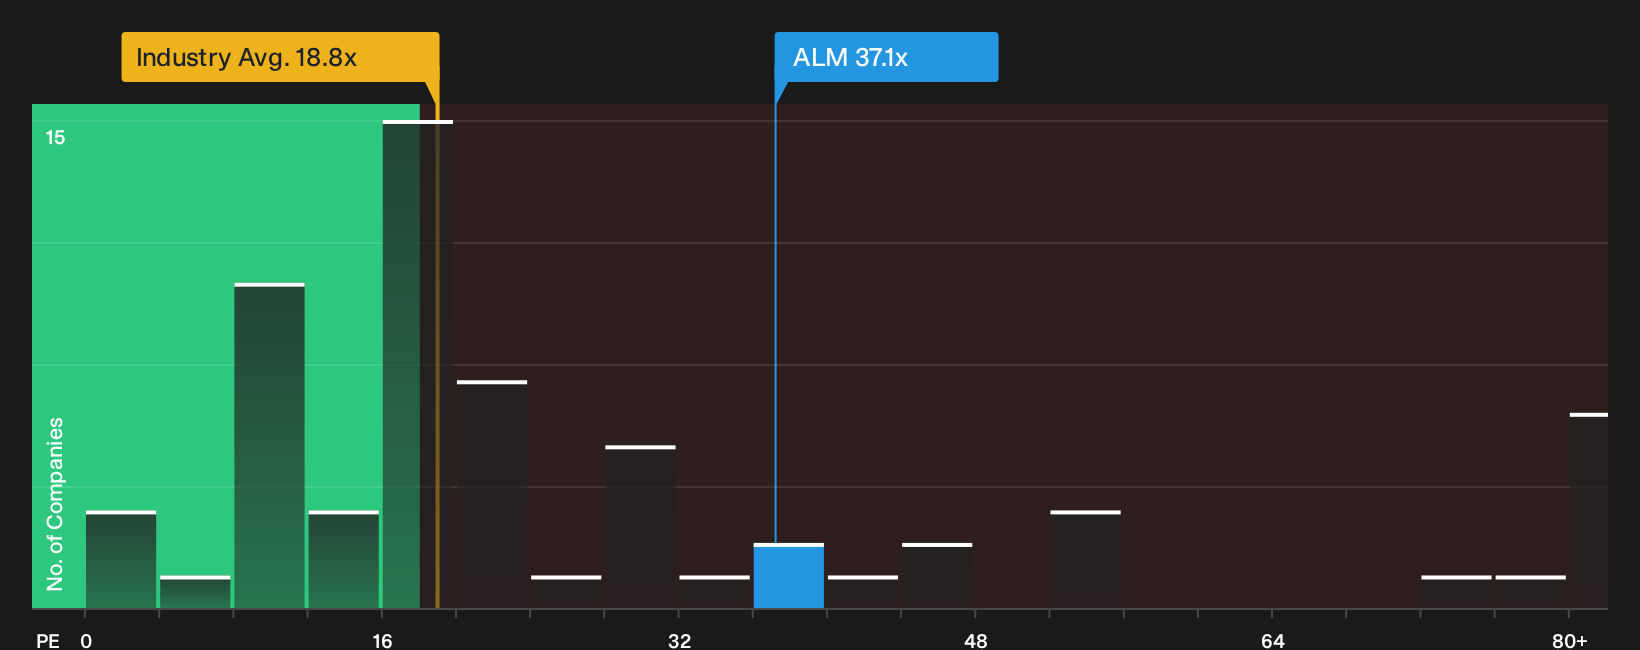
On earnings multiples, Almirall looks much less relaxed than the 31% undervalued fair value label suggests. The shares trade on a P/E of 37.1x, compared with 20.7x for peers and 18.8x for the wider European pharmaceuticals group, while the fair ratio sits at 24.5x.
That gap means investors are paying a richer price today than both sector averages and the level the market could move towards over time. This raises the question of whether the discount to fair value reflects mispricing or simply optimistic earnings assumptions baked into the models.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Whether you have mixed views on Almirall’s valuation or are already leaning toward one side, it is still important to move quickly and test the assumptions against your own research. To see what optimism in the models is based on, take a closer look at the 4 key rewards.
Looking For More Investment Ideas Beyond Almirall?
If Almirall has sharpened your focus on quality and price, do not stop here. Broader idea hunting can quickly change how you build your portfolio.
- Target potential mispricing by reviewing a curated set of attractively priced quality businesses in the 178 high quality undervalued stocks.
- Strengthen your focus on resilience and capital protection by scanning companies with robust finances through the list of solid balance sheet and fundamentals (204 results).
- Get ahead of the crowd by searching for underfollowed opportunities in the 618 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com