


Clearway Energy (CWEN) Beats Earnings Views, Is The 28% Undervalued Case Still Intact?
Clearway Energy (CWEN) surprised the market with Q2 FY26 GAAP EPS of 1.15 compared with an estimate of 0.66, placing the clean power operator’s recent move firmly in an earnings context.
Investors have reacted to Clearway Energy’s earnings surprise with a modest pickup in momentum, with the share price up 0.80% over the last day and 2.90% over the past week, even though the 30 day share price return is down 3.05% and the year to date share price return is down 11.10% at US$30.19.
That softer recent share performance contrasts with a 1 year total shareholder return of 1.99% and a 3 year total shareholder return of 66.48%. This suggests the latest move is being weighed against a much stronger multi year outcome that already includes dividends.
Scan how Clearway Energy’s earnings surprise compares with other potential breakout utilities in our hand picked list of 43 power grid technology and infrastructure stocks.
The earnings beat and mixed return profile leave Clearway Energy at an interesting crossroads. Does the current valuation still skew the risk reward toward new buyers, or has most of the easy upside already been claimed?
Most Popular Narrative: 28% Undervalued
The most followed narrative on Clearway Energy pitches a fair value of $42.08 versus the last close at $30.19, which points to a wide gap that hinges on how credible future cash flows and pipeline projects prove to be.
Clear funding visibility through 2030, including retained cash flow, recent senior unsecured notes with tight spreads to treasuries and accretive equity issuance, positions the company to deploy corporate capital at CAFD yields of around 10.5% on identified projects, which can support CAFD per share growth and help sustain net margin performance.
See why 10 investors see Clearway Energy as 28% undervalued.
Result: Fair Value of $42.08 (UNDERVALUED)
Still, the narrative around Clearway Energy can break if data center power demand slows, or if policy shifts delay projects and squeeze cash flow.
Find out about the key risks to this Clearway Energy narrative.
Another View: Clearway Energy Looks Expensive On Earnings
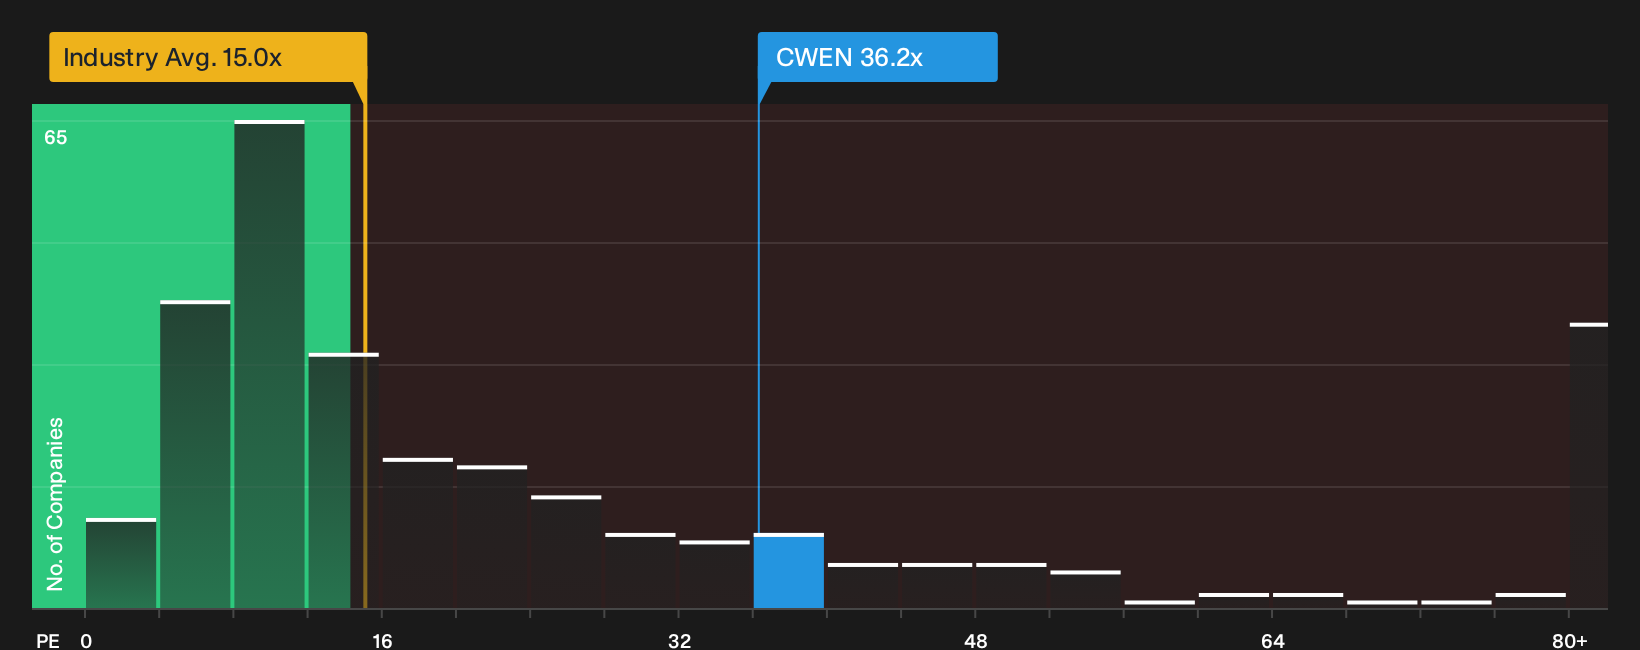
On the flip side of that $42.08 fair value narrative, Clearway Energy screens as expensive on simple earnings math. The stock trades on a P/E of 36.2x, versus 31.6x for peers and 15x for the broader renewable energy group, while the fair ratio sits lower at 26.3x. That gap points to less room for error if growth or margins disappoint. Which lens do you trust when the story and the simple numbers disagree?
To see how this earnings based view stacks up against a fuller valuation breakdown, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals can feel confusing, especially when Clearway Energy shows both clear risks and genuine upside. Act quickly by checking the underlying data and weighing the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Clearway Energy?
If Clearway Energy has sharpened your thinking, broaden your watchlist now with focused stock ideas built directly from the Simply Wall St Screener.
- Target resilient balance sheets by scanning the list of solid balance sheet and fundamentals (25 results), which combines financial strength with room for future opportunity.
- Hunt for mispriced potential and review the 29 high quality undervalued stocks, which pairs quality fundamentals with discounted market expectations.
- Secure income focused opportunities by checking the 8 dividend fortresses, which offers higher yields backed by underlying business strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com