


Higher Treasury Yields Are Reviving Interest In MetLife And Other US Life Insurer Stocks
Long term Treasury yields sit near multi decade highs, Washington is staring at a CBO debt path that climbs toward 120% of GDP, and investors are quietly rethinking which businesses can live with pricier money rather than rely on cheap funding. That mix creates both risk and potential opportunity. This article walks through three U.S. life insurance and annuity providers exposed to these forces and explains why their stories deserve a closer look now.
The stocks in the spotlight below are just a starting sample, since the full screen pulled out 10 more U.S. life insurance and annuity providers with stories that line up with the higher yield theme but are not covered in this article. To go straight to the source and identify, compare, and analyze those ideas for yourself, head into the US Life Insurers and Annuity Providers Benefiting from Higher Long-Term Yields screener.
Brookfield Wealth Solutions (BNT)
Brookfield Wealth Solutions is a retirement and wealth protection group whose annuities and life insurance align closely with the higher long term yields theme. It generates about US$9.4b of revenue from annuities and US$2.6b from P&C, and has a market value around US$13.3b.
Brookfield Wealth Solutions sits squarely in the life and annuity camp that is often most exposed when long term yields move, with annuities generating the bulk of its roughly US$9.4b segment revenue alongside P&C and corporate lines. Higher reinvestment rates can help long duration products, although very low recent profitability and a high P/E mean investors are still watching what happens when a single pressure on returns either eases or intensifies.
If you want to see whether that pressure on returns is already getting priced in or still masking upside, start with the DCF valuation analysis for Brookfield Wealth Solutions before sentiment catches up.
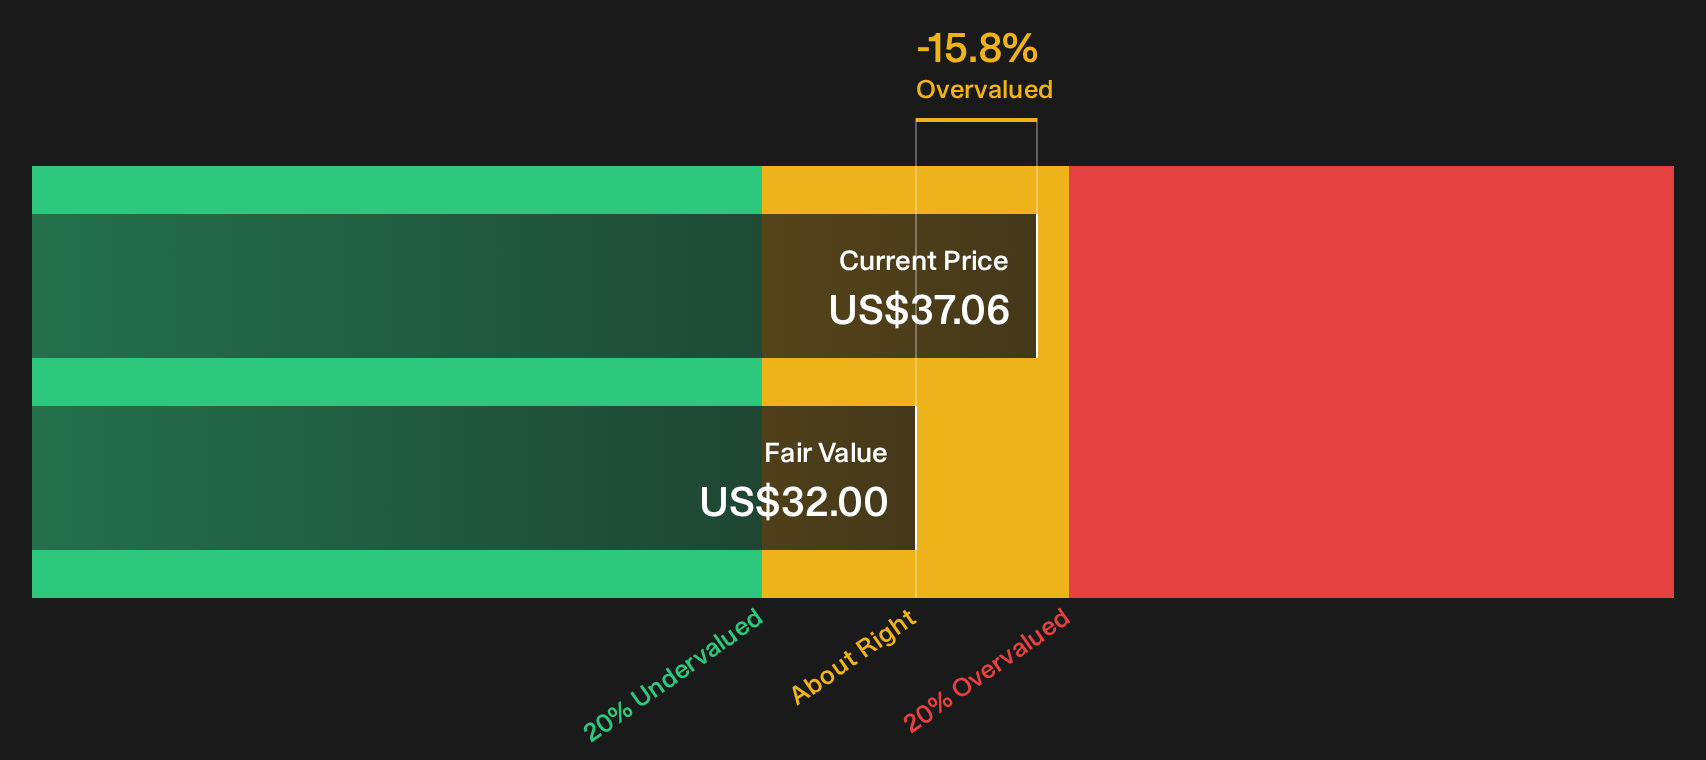
Globe Life (GL)
Globe Life leans into the screener theme as a US focused life insurer whose long duration protection policies depend heavily on the gap between what it earns on its investment portfolio and what it owes policyholders, so higher long term yields matter a lot.
Globe Life generates about US$3.4b from life coverage, US$1.6b from supplemental health policies and US$1.2b from investments, all almost entirely in the United States, and carries a market value of roughly US$12.6b.
"Planned deployment of AI applications across administration, underwriting and sales support is aimed at lowering the administrative expense ratio from about 7.3% of premium and lifting agent productivity, which could support higher net margins and net operating income over time."
What happens to those economics if one still developing piece of the distribution mix shifts faster or slower than management expects will be crucial.
That hinge point around distribution and margins is exactly what the full narrative for Globe Life unpacks, revealing where the economics could be quietly accelerating or stalling next.

MetLife (MET)
MetLife is one of the biggest global life insurance and annuity players, closely tied to the higher long term yield theme through spread driven earnings. It generates about US$27.1b from U.S. Group Benefits and US$21.5b from Retirement and Income Solutions, with meaningful contributions from Asia at US$12.4b and Latin America at US$9.1b. The group also records US$6.3b from Corporate & Other and US$1.1b from MetLife Investment Management, supporting a diversified model relative to its roughly US$62.5b market value.
MetLife provides a large scale way to gain exposure to higher long term yields through life insurance and annuities, while also incorporating global benefits and asset management. The key question is how its reinvestment opportunity connects with ongoing efficiency initiatives.
"Ongoing investment in technology and AI, including more than US$3.2b of spend over five years and visible automation in underwriting, claims and RFP processing, points to further unit cost efficiency that can support net margins and earnings quality."
How that efficiency push interacts with even a small shift in one less visible spread driver could reshape how sustainable those margins appear.
That shift in spread drivers is exactly what the full narrative for MetLife maps out, highlighting where MetLife’s earnings engine could be accelerating or quietly decoupling from expectations.

Seeking Fresh Alternatives Before They Fly
Fresh ideas move first. Breakout stories gather momentum, then the best entry points get caught by the crowd and pricing power starts dropping. Scan these under the radar lists and get in early.
- Spot resilient cash generators by running through the list of solid balance sheet and fundamentals (25 results) and focus on businesses where strong finances give management more room to handle surprises.
- Chase income while others hesitate and comb the 8 dividend fortresses to find higher yielding payers that still pair distributions with balance sheet support.
- Track AI demand behind the headlines and work through the 92 AI infrastructure stocks to see which enablers could benefit as workloads and data traffic build.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com