


Could Anthropic Defense Partnership Change The Bull Case For Hitachi Stock
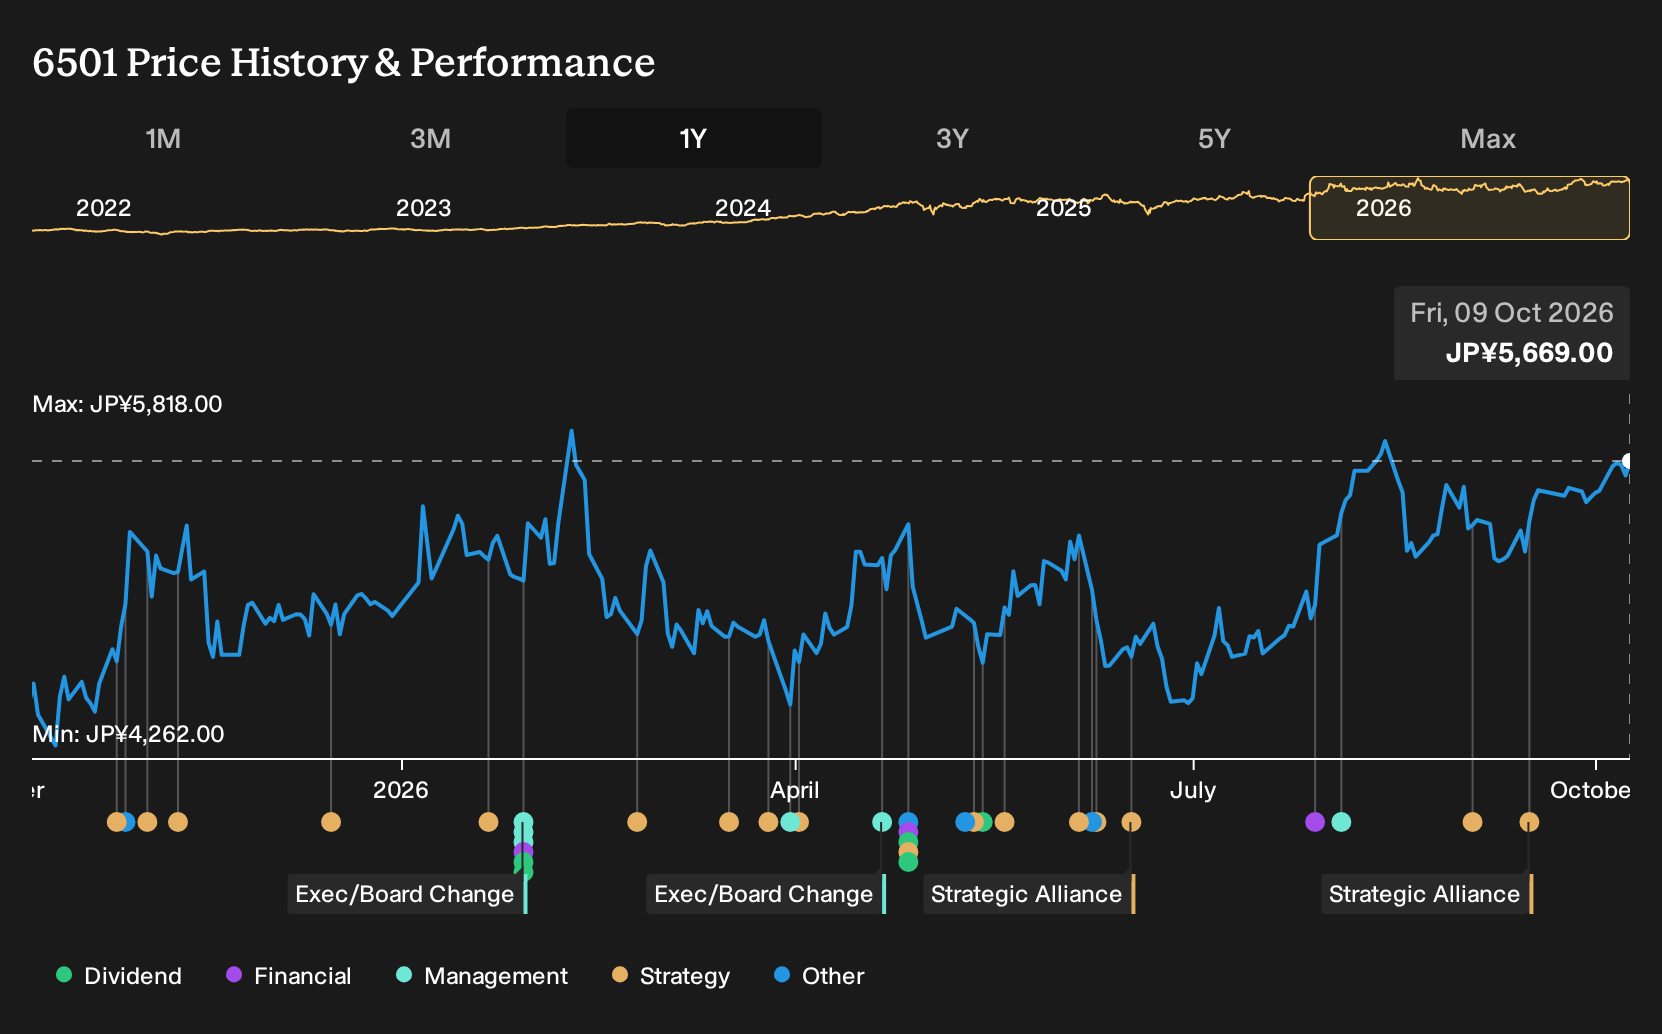
- Hitachi recently expanded its relationship with Anthropic by joining the Critical Infrastructure Defense Program as a founding partner, aiming to embed Claude AI models into offerings used by utilities, transportation operators, and other critical infrastructure customers.
- This move links Hitachi's operational technology and digital systems with advanced cybersecurity tools. It could influence how its energy grids and Lumada-based services address rising AI-driven cyber risks for core infrastructure clients.
- We will now explore how Hitachi's role in Anthropic's defense program could shape its broader investment narrative around digital infrastructure.
Scan other AI security and digital infrastructure players moving on similar themes with our curated list of 92 AI infrastructure stocks as this Hitachi Anthropic partnership takes shape.
Hitachi Investment Narrative Recap
To own Hitachi, you need to believe the long term shift toward power grid upgrades, electrification and higher margin digital services like Lumada and HMAX continues to support the business mix. The Anthropic partnership fits neatly into that view, giving Hitachi another way to embed AI into operational technology without changing the overall thesis.
The most important near term swing factor still looks like execution on large Energy capex and backlog while managing cost inflation and project risk. The Anthropic cyber defense work may help the digital story, but the bigger risk remains underutilized grid capacity investments and any prolonged investment restraint from overseas customers.
The recent share buyback update is the clearest adjacent data point to consider alongside this Anthropic news. From July to September, Hitachi repurchased 27,314,700 shares for ¥142,359.03m, completing a total of 47,661,000 shares for ¥242,358.61m under the April 27 program, equal to 1.06% of shares.
For you as a shareholder, that repurchase indicates management is willing to return cash while it spends heavily on Energy capacity, Lumada expansion and physical AI like HMAX. It also slightly tightens the share count as earnings grow, which can matter if execution on the large Energy backlog or AI centric services delivery becomes choppier than expected.
Hitachi's current analyst narrative points to forecast revenues of ¥14,382.3b and projected earnings of ¥1,328.5b by 2029, which lines up with an assumed 9.2% yearly revenue growth rate and an earnings increase of about ¥528.9b from earnings today of ¥799.6b.
Uncover why Hitachi's fair value indicates a 16% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternative view puts execution risk in Hitachi’s massive ¥10t Power Grid backlog ahead of AI upside from Anthropic. The most cautious analysts were only modeling revenue of about ¥13,589.5b and earnings near ¥1,302.5b by 2029, which implies a flatter path. Those estimates pre date this partnership; as a result, expectations may shift.
Explore 4 other Hitachi fair value estimates, including one that suggests as much as 13% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Hitachi research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Hitachi. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hitachi's overall financial health at a glance.
Looking for more investment ideas beyond Hitachi?
Once you have a view on Hitachi, it can help to compare that thesis with other businesses that share similar quality traits or income characteristics. The Simply Wall St Screener gives you a fast way to line up those options side by side.
- If you want companies that pair quality with what may be appealing entry points, start with a curated set of 13 high quality undervalued stocks that already screen for both fundamentals and pricing.
- For investors who care most about capital strength and cleaner balance sheets, check out a list of solid balance sheet and fundamentals (23 results) that can sit alongside Hitachi in a more resilient portfolio mix.
- If you prefer ideas that are off the beaten path yet still grounded in hard numbers, review a 74 high quality undiscovered gems that might complement a position in a larger group like Hitachi.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com