


Is Westlake (WLK) Cheap On Its Cologne PVC Plant Closure?
Westlake (WLK) is back in focus after the company moved to close its higher cost PVC plant in Cologne, Germany, a step tied to weak demand and elevated European energy prices.
For context, Westlake’s share price has softened over the year, with a 30-day share price return down 12.03% and a year-to-date share price return down 15.99%, while the 1-year total shareholder return has declined 15.42% and the 3-year total shareholder return is down 45.23%. This points to fading momentum as management reshapes its European footprint.
Scan how Westlake’s restructuring compares with peers tackling similar pressure on costs and demand by reviewing the hand picked list of solid balance sheet and fundamentals (25 results) in capital intensive sectors.
Westlake is now weighing a cleaner European footprint against bruised sentiment around plastics demand and plant closures. Is the recent share slide still about the story, or about the price you pay for it?
Most Popular Narrative: 33% Undervalued
Westlake’s most followed valuation story pegs fair value at $92.31 a share compared with a last close of $62.29, putting the recent pullback against a much higher narrative anchor.
Westlake continues to benefit from having around 85% of Performance and Essential Materials production tied to North American natural gas and NGL feedstocks, which were largely unaffected by the recent oil price spike. This allowed a 21% sequential average sales price increase in Q2 2026 to flow through to margins and supported future earnings sensitivity to global polyethylene, caustic soda and PVC pricing.
See why 9 investors see Westlake as 33% undervalued.
Result: Fair Value of $92.31 (UNDERVALUED)
Still, persistent pricing pressure in key chemical chains and higher North American feedstock or energy costs could quickly challenge the bullish Westlake narrative.
Find out about the key risks to this Westlake narrative.
Another View: SWS DCF Flags Caution
The popular fair value story puts Westlake at $92.31, yet the Simply Wall St DCF model points in a different direction. On that cash flow view, the stock at $62.29 is trading above an estimated value of $49.42, so the DCF lens frames Westlake as overvalued. Which lens do you trust more when the narratives disagree?
Look into how the SWS DCF model arrives at its fair value.
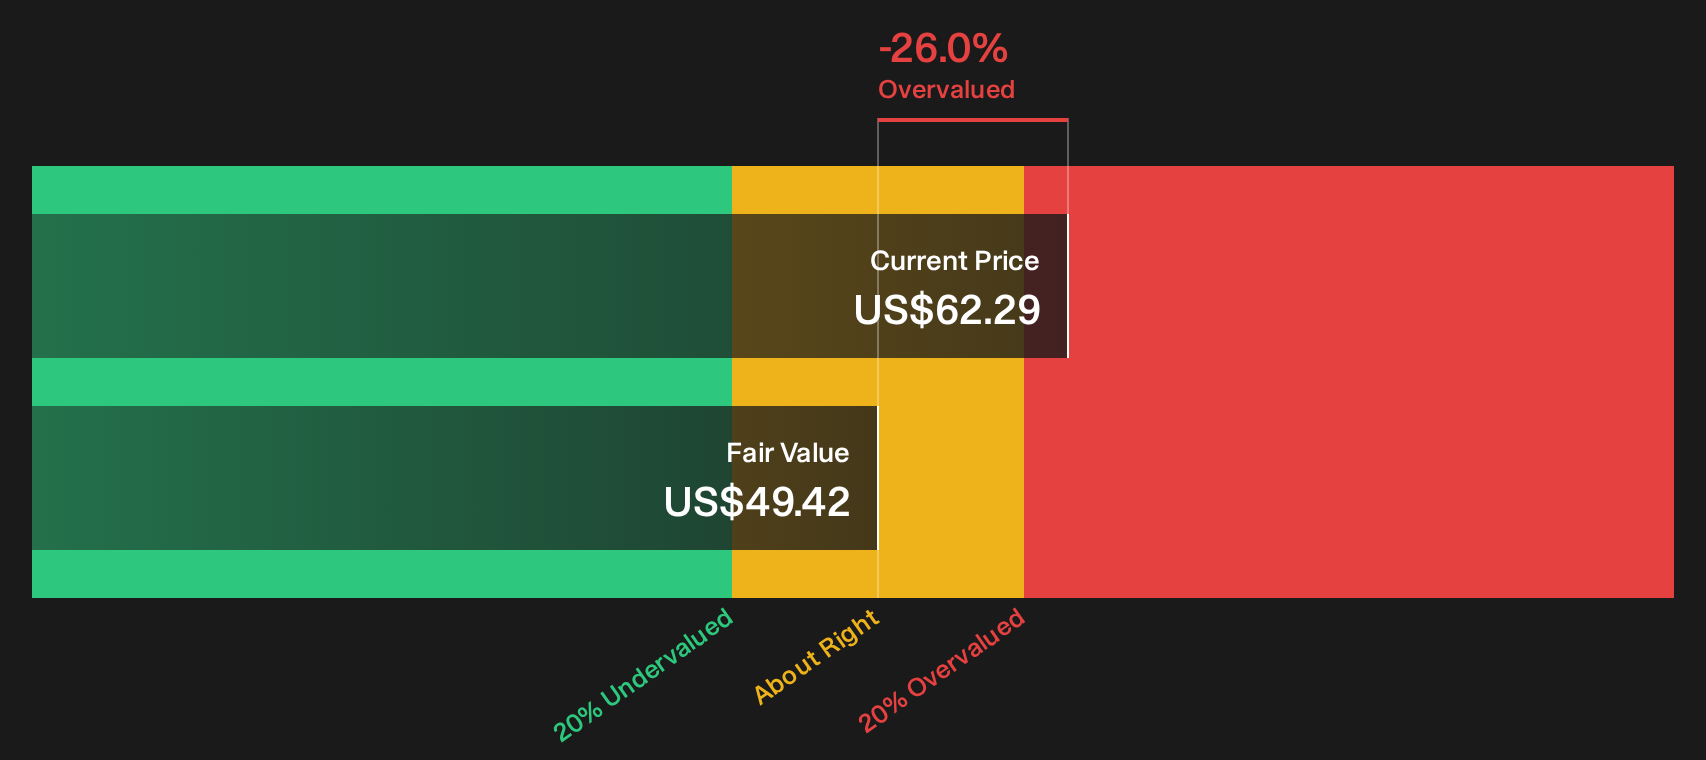
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Westlake for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Uncertain about whether the mixed mood around Westlake really fits the numbers in front of you today, or just the recent headlines? Move quickly, pull apart both the upside and the downside, and finish by weighing the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Westlake?
If Westlake has you rethinking where risk and reward really line up, do not stop here. Broader ideas often emerge when you scan high quality lists built from consistent rules.
- Target resilient balance sheets by reviewing the list of solid balance sheet and fundamentals (25 results) that pair financial strength with room for future capital deployment.
- Hunt for mispriced quality and sort through the 29 high quality undervalued stocks before the rest of the market focuses on the same opportunities.
- Prioritise cash returns and compare payout heavy candidates inside the 8 dividend fortresses while yields and balance sheets still look attractive.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com