


China Feihe (SEHK:6186) Could Be 50% Undervalued After Special Dividend News
China Feihe (SEHK:6186) has put cash returns front and centre by declaring a one off special dividend of HK$0.2905 per share, or about HK$2.56b, for eligible shareholders in October 2026.
Investors have reacted positively in the short term, with a 1 month share price return of 9.11% and a 1 day move of 3.38% taking China Feihe to HK$2.755. However, the share price return is still down 31.64% year to date and the 5 year total shareholder return has declined 70.47%. This suggests recent momentum is rebuilding from a much weaker long term base as the special dividend and relatively low P/E ratio draw fresh attention to the stock.
Scan how China Feihe compares with other dividend focused opportunities by checking our hand picked list of 223 dividend fortresses before this income theme moves on.
The question now is whether China Feihe’s rebound is investors re-rating the underlying milk and supplements business, or a short term reaction to a one off payout and low P/E headline.
Preferred P/E of 11.6x: Is it justified?
On current numbers, China Feihe trades on a P/E of 11.6x, which lines up with a stock that the market values below its own estimated cash flow fair value of HK$5.44 and below the peer average.
The P/E ratio compares the share price to earnings per share and gives a quick sense of how much investors are paying for each unit of profit. For a dairy and nutritional supplements group like China Feihe, where earnings quality is flagged as high but profit trends have been under pressure, this metric helps frame how much faith the market places in any potential profit stabilisation or improvement.
The signal is mixed. Management reports high quality earnings and the SWS DCF model suggests HK$5.44 per share. At the same time, earnings have declined 27.2% per year over the past 5 years and net profit margins have moved from 13.6% to 9.7%. That kind of pressure, together with a dividend yield of 9.07% that is not well covered by earnings, points to a market that is pricing in caution even as the fair ratio work suggests the P/E could move closer to 12.8x over time.
Compared with other food groups in Hong Kong, the picture becomes clearer. The P/E of 11.6x sits below the peer average of 20x and slightly under the Hong Kong Food industry average of 12.2x, which signals that investors are attaching a clear discount despite China Feihe trading at what the model calls good value versus both the sector and that 12.8x fair ratio level.
Explore the SWS fair ratio for China Feihe.
Result: Price-to-earnings of 11.6x (UNDERVALUED)
Still, the narrative around China Feihe could shift quickly if earnings pressure resumes or if the high headline dividend yield proves difficult to sustain.
Find out about the key risks to this China Feihe narrative.
Another view on China Feihe’s value
The first check used P/E and pointed to China Feihe as inexpensive against peers. A second lens, the SWS DCF model, values the stock at HK$5.44 per share compared with the HK$2.755 price. That gap suggests the cash flow outlook is more optimistic. Which signal do you trust more right now?
Look into how the SWS DCF model arrives at its fair value.
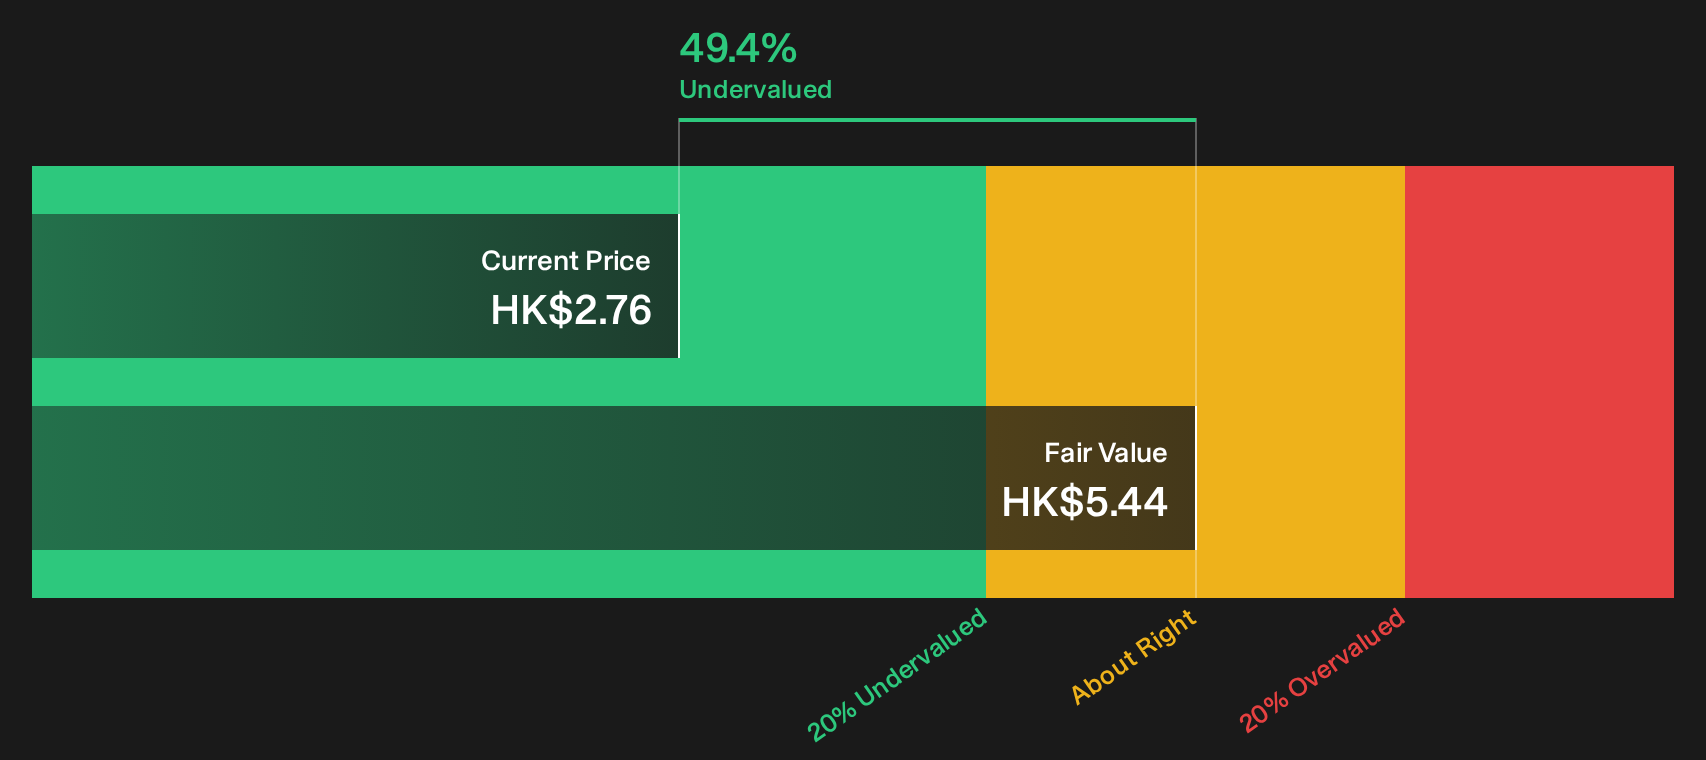
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out China Feihe for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 178 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around China Feihe is clearly split, with income appeal and valuation upside on one side and earnings pressure on the other. Move quickly and weigh the evidence that matters most to you with the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond China Feihe?
If you only focus on China Feihe, you could miss other opportunities that fit your income, quality or value goals. Use the tools available and give yourself options.
- Target resilient balance sheets by scanning companies in the list of solid balance sheet and fundamentals (204 results) that may better match your comfort with financial strength.
- Hunt for potential value by reviewing the 178 high quality undervalued stocks and see which stocks line up with your preferred mix of price and fundamentals.
- Strengthen your income watchlist by comparing the yields in the 223 dividend fortresses before the next round of payouts is on the table.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com