


How Raised RevPAR Guidance At Host Hotels & Resorts (HST) Has Changed Its Investment Story
- Host Hotels & Resorts reported Q2 2026 results with adjusted EBITDA RE up 5.8%, adjusted FFO per share up 8.6%, and higher full-year RevPAR growth guidance to a range of 4.75% to 5.25%.
- Management paired renovation progress at Hyatt and Marriott branded properties with an asset sale and special dividend, reflecting a tight focus on where capital is deployed and how cash is returned to shareholders.
- We will now examine how Host Hotels & Resorts raising its RevPAR guidance could reshape the broader investment narrative around the business.
Compare Host Hotels & Resorts' latest RevPAR guidance and cash returns with other real estate plays by scanning our hand-picked list of solid balance sheet and fundamentals (25 results).
Host Hotels & Resorts Investment Narrative Recap
To own Host Hotels & Resorts, you need to be comfortable with a story built around premium resorts, large renovation programs and event driven demand. The raised RevPAR growth guidance to 4.75% to 5.25% points to solid near term pricing and occupancy support from leisure travel and events like the World Cup, which feeds directly into the current earnings narrative.
The near term swing factor is still how effectively Host brings its multi year, US$2.1b renovation pipeline into full contribution while limiting disruption to existing guests. The biggest risk remains pressure on business travel and weather related interruptions, which can offset resort strength and leave RevPAR and EBITDA more volatile than the headline guidance suggests.
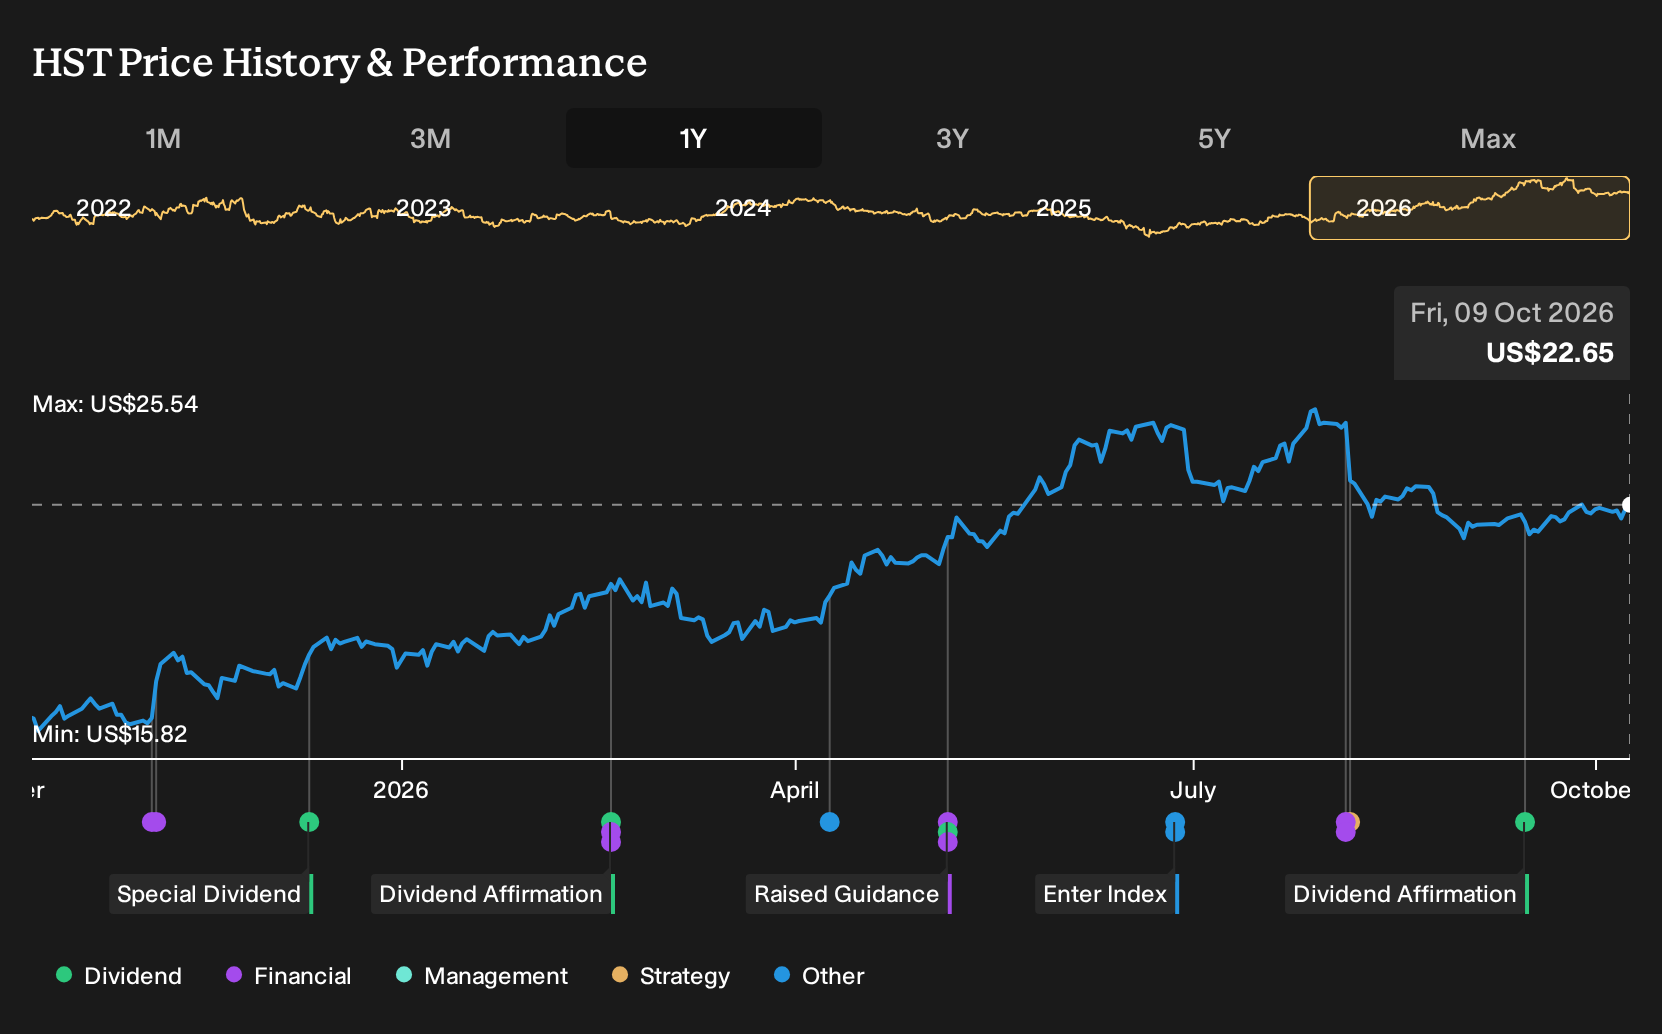
The special dividend tied to the Sheraton Parsippany sale is the announcement that matters most around this update. It shows Host Hotels & Resorts turning asset sales and operating cash into direct cash distributions, in addition to regular payouts, at a time when analysts already flag the shares as trading below some intrinsic value estimates and a P/E that screens lower than many peers.
For you as a shareholder or potential investor, that combination of raised RevPAR guidance and incremental capital return sharpens the focus on execution. The story now relies more heavily on Host’s ability to keep resorts performing, convert World Cup and other group demand into sustained cash flow, and still fund heavy capex without stretching a balance sheet that already carries a high level of debt and an unstable dividend track record.
Host Hotels & Resorts is currently modeled to reach about US$6.3b of revenue and US$822.9 million of earnings by 2029, with analysts assuming fairly flat top line performance and a decline from roughly US$1.0b of earnings today. This implies an earnings reduction of about US$177 million over that period.
Uncover why Host Hotels & Resorts' fair value indicates a potential 12% upside to its current price before that discount starts to close.
Exploring Other Perspectives
One contrasting angle on Host Hotels & Resorts centers on group and convention demand. Bullish analysts, working before this RevPAR guidance hike and special dividend, were comfortable modeling about US$6.6b of revenue and US$754.5 million of earnings by 2029. You might read that as a far more optimistic story. It is worth comparing those assumptions with your own before deciding which narrative feels closer to how you see the business evolving after this latest update.
Explore another Host Hotels & Resorts fair value estimate, including one that suggests as much as 56% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Host Hotels & Resorts research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Host Hotels & Resorts. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Host Hotels & Resorts' overall financial health at a glance.
Looking For More Investment Ideas Beyond Host Hotels & Resorts?
If this update on Host Hotels & Resorts has sharpened how you think about risk, balance sheets and cash returns, use that same lens to scan a wider field of opportunities with the Simply Wall St Screener.
- If capital preservation is your priority, start with companies that pair resilience with tempered volatility by checking out 31 resilient stocks with low risk scores.
- For investors who care most about financial strength and staying power, run your eye over our hand picked list of solid balance sheet and fundamentals (25 results).
- If you want ideas that are off most radars yet still underpinned by strong fundamentals, widen your search with 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com