


Diesel Relief Could Lift Heartland Express Stock And Other Transport Shares
Oil diplomacy is shifting again, with Moscow offering diesel relief at the same time tanker attacks keep shipping risk elevated. That mix of potential cheaper fuel and stubborn route disruption is already filtering into transport and logistics stocks, and some could quietly benefit while others face a squeeze. This article walks through three stocks from the Global Transportation and Logistics screener that appear especially exposed to this latest twist in energy geopolitics.
The stocks covered below are just a sample, and the full screen surfaced 59 more transport and logistics businesses with equally compelling fuel exposure stories that are not discussed here. If you want to go beyond the shortlist and identify which operators best fit your own risk and return goals, head straight into the Global Transportation and Logistics Stocks screener.
Heartland Express (HTLD)
Overview: Heartland Express is a North American truckload carrier that hauls diesel-fuel-intensive dry van and temperature-controlled freight for large shippers.
Operations: Heartland Express generates about US$736 million in trucking transportation revenue, with all reported sales coming from customers in the United States.
Market Cap: US$860 million
Heartland Express provides focused exposure to diesel-sensitive trucking, with US$736 million of U.S. truckload revenue and routes that are closely tied to fuel costs. Recent profitability improvement and expectations for stronger earnings place greater emphasis on how diesel prices evolve, particularly if any existing pressure on its fuel cost advantage changes direction.
If that fuel leverage matters to your thesis, start with the DCF valuation analysis for Heartland Express and see whether current pricing already reflects the earnings swing risk.
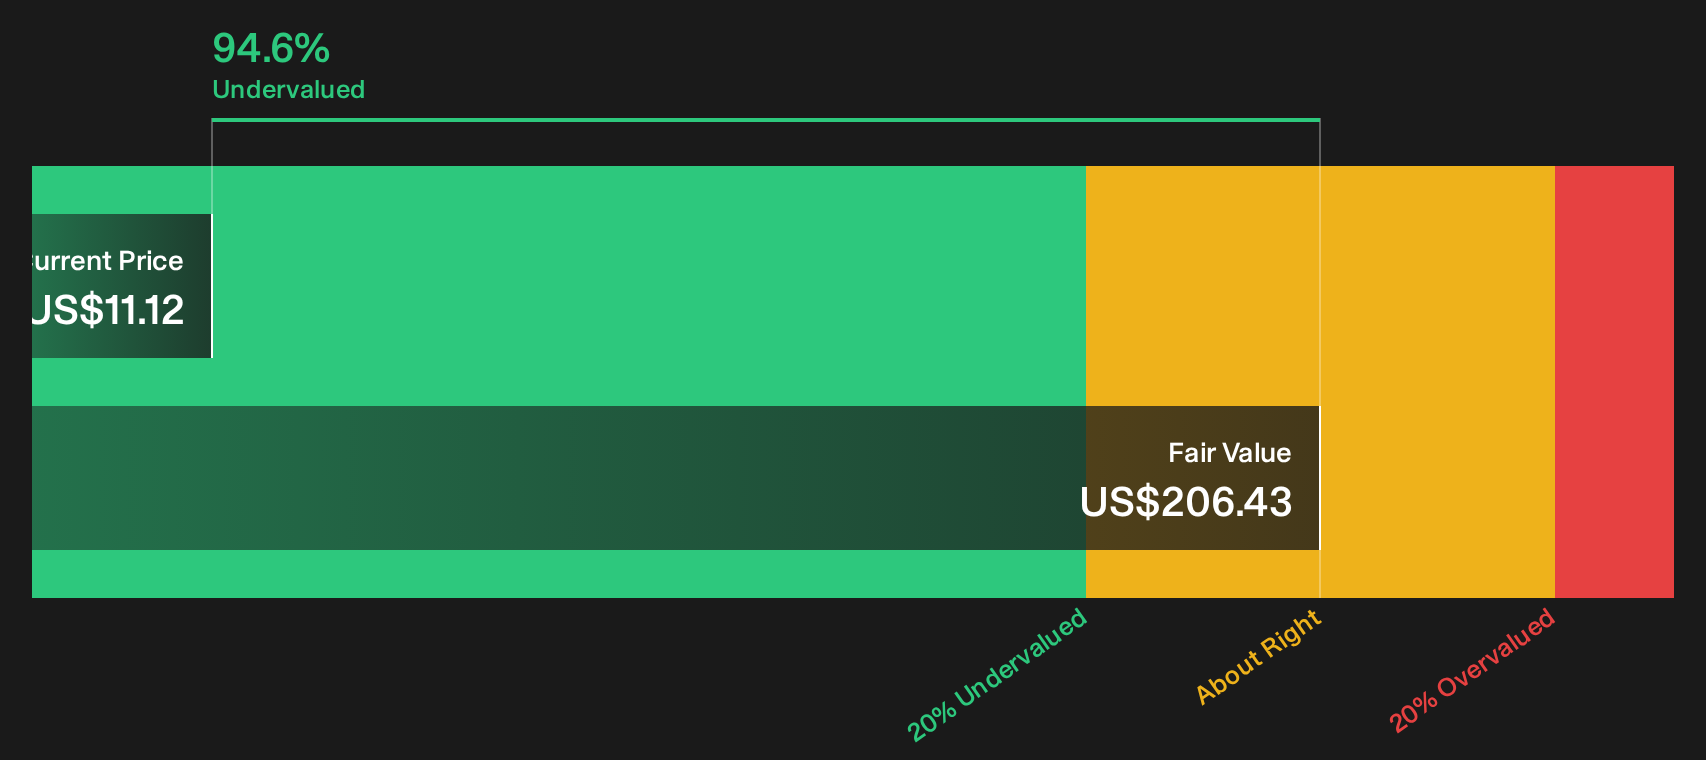
Qantas Airways (ASX:QAN)
Overview: Qantas Airways is an Australian airline group providing domestic and international passenger flights, air freight services and a large loyalty program.
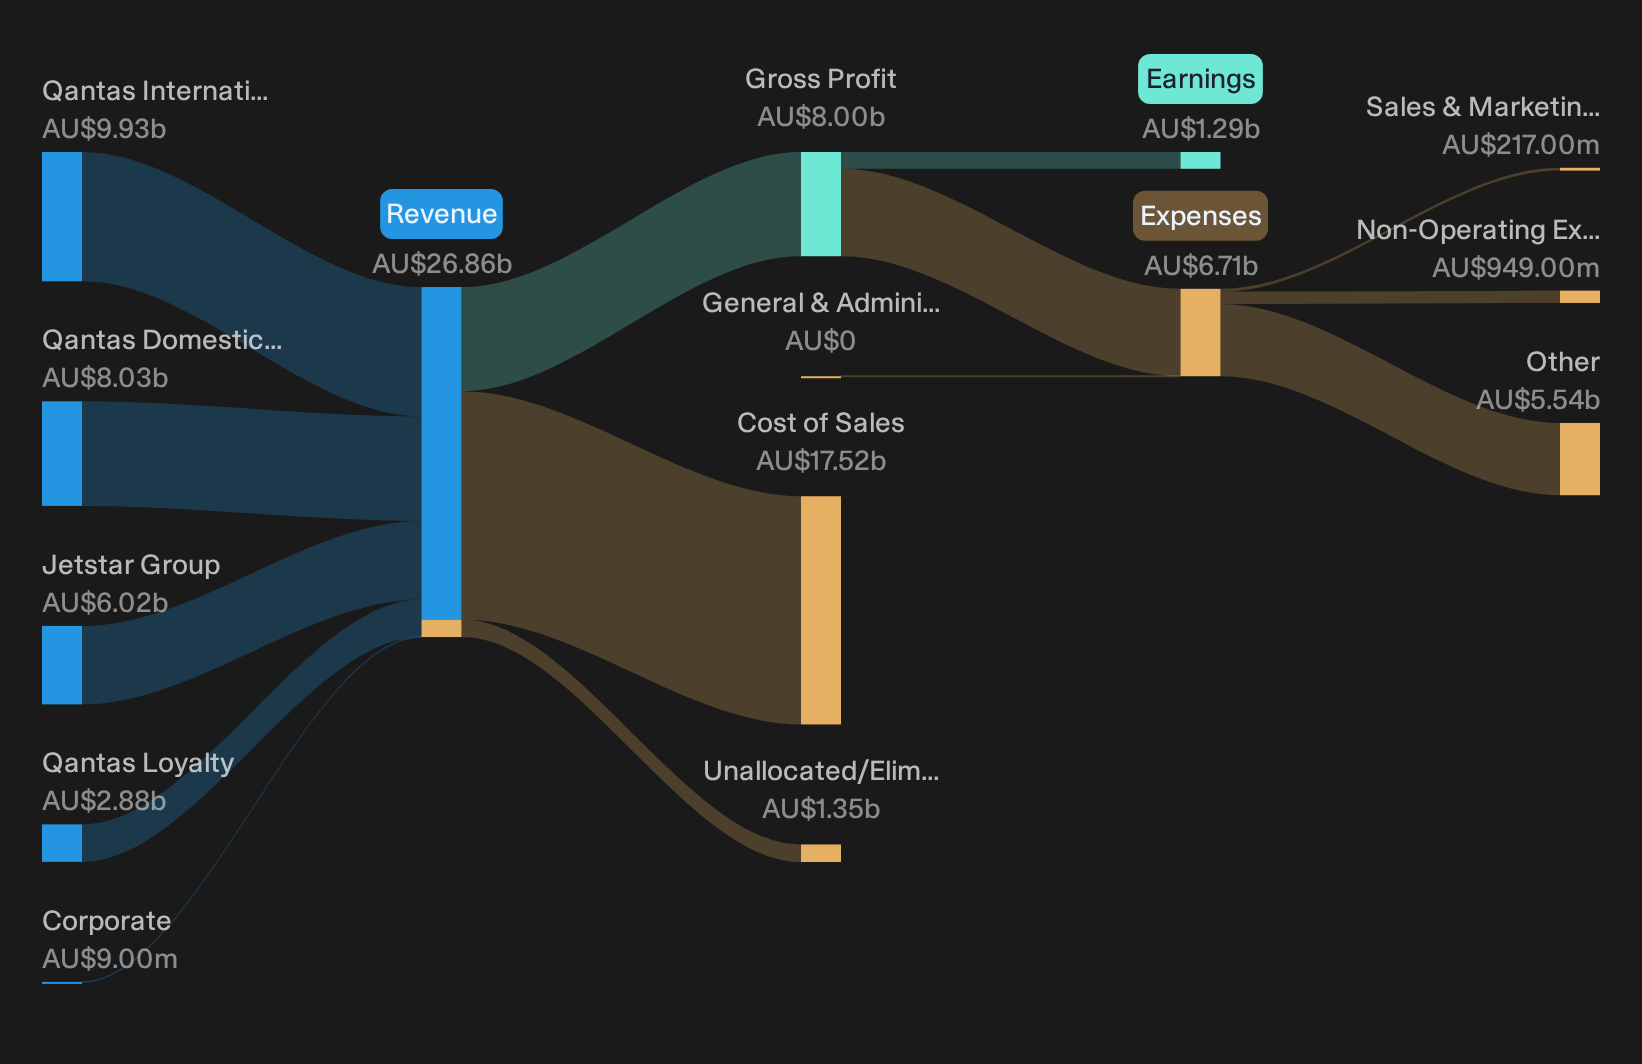
Operations: Qantas Airways earns most of its revenue from Qantas International at A$9.9b, Qantas Domestic at A$8.0b and Jetstar Group at A$6.0b.
Market Cap: A$12.6b
Qantas Airways is a central piece of this transport and logistics screen because jet fuel and diesel linked refined products run straight through its income statement. Any shift in fuel prices or hedging outcomes can quickly change the economics of both its domestic network and long haul flying.
"Fuel price fluctuations materially impacting margins"
The real swing factor for Qantas Airways now is how one still unresolved pressure on its cost base interacts with that fuel exposure over time.
That unresolved pressure on the cost base is exactly where your edge could come from. The full narrative for Qantas Airways shows how fuel risk might be masking upside potential.
Schneider National (SNDR)
Overview: Schneider National is a large North American freight carrier that moves goods by truck, intermodal rail and asset light logistics, leaving earnings closely tied to diesel intensive surface transport.
Operations: Schneider National generates about US$2.5b from Truckload, US$1.3b from Logistics and US$1.1b from Intermodal, almost entirely in the United States.
Market Cap: US$5.5b
Schneider National matters for this fuel focused screen because it combines diesel hungry truckload fleets with rail linked intermodal and asset light logistics that all feel lower pump prices in different ways, which sets up an interesting cost story as diesel relief intersects with already tight trucking capacity.
"Continued investment in technology and AI driven tools across Schneider National’s logistics, driver support and recruiting operations, including reported 17% productivity gains in frontline logistics staff and ongoing cost savings programs of US$40 million in both 2025 and 2026, points to further operating expense efficiency that can support higher net margins and earnings over time."
What really moves the needle from here is how one evolving supply side shift interacts with that efficiency push to reshape pricing power.
If that shift is what you care about, the full narrative for Schneider National shows how Schneider National’s efficiency push could translate into accelerating earnings power and pricing resilience.

Seeking Alternatives Before The Crowd
Fresh ideas move first. By the time momentum headlines hit, early opportunities may already be flying. Scan under the radar for now, while it matters, and get in early.
- Hunt for potential value plays among quality companies using the 29 high quality undervalued stocks, before any breakout narrative gets widely caught in market momentum.
- Track future facing infrastructure trends by scanning the 92 AI infrastructure stocks while these enablers of AI demand are still dropping quietly into institutional radars.
- Target resilient balance sheets in a single pass through the list of solid balance sheet and fundamentals (25 results) so you are not chasing stability only after volatility spikes.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com