


Does Nikkei 225 Addition Change The Bull Case For Kokusai Electric Stock (TSE:6525)?
- Kokusai Electric Corporation was added to the Nikkei 225 Index in October 2026. This marked its inclusion in one of Japan's key equity benchmarks and may change how many institutional and passive investors gain exposure to the stock.
- The index entry highlights Kokusai Electric's role in semiconductor manufacturing equipment and draws more attention to its exposure to Chinese demand, US expansion plans, and capital spending commitments in portfolio decisions.
- We will now look at how Kokusai Electric's Nikkei 225 inclusion could influence the investment narrative that had been forming beforehand.
Scan how Kokusai Electric's index debut compares with other potential benchmark entrants by reviewing the hand picked list of solid balance sheet and fundamentals (23 results) in related sectors.
Kokusai Electric Investment Narrative Recap
To hold Kokusai Electric, you need to be comfortable with a story built on semiconductor capital spending for advanced nodes and a very concentrated end market. The Nikkei 225 inclusion may raise the profile of that thesis, but it does not change the underlying reality that earnings are tightly linked to wafer fab investment cycles and customer budgets.
The near term swing factor still sits in order momentum from China and large NAND or DRAM projects, after a quarter where revenue and operating profit both declined year on year. The biggest risk remains that Chinese demand stays weak while Kokusai Electric commits to higher R&D and capex, putting pressure on margins and free cash flow.
The clearest recent announcement that ties back to this index inclusion is the plan to spend ¥20b over two years on a US demonstration center, alongside sharply higher R&D. For Kokusai Electric, this is about expanding the tool lineup and shortening evaluation cycles for North American clients, not just adding a flag in a new geography.
This build out could act as a practical catalyst if it supports a better product mix in higher margin, advanced node tools and helps reduce reliance on Chinese orders over time. The risk is straightforward. If the expected demand from AI, advanced NAND, and GAA logic does not come through at the scale implied by current forecasts, that extra fixed cost would weigh on profitability.
Kokusai Electric's current narrative points to ¥509.6 billion in revenue and ¥106.7 billion in earnings by 2029. This outlook is built on analysts assuming revenue grows 25.4% per year and profit rises from ¥34.9 billion today to that level, which implies earnings need to increase by about ¥71.8 billion over the period.
Uncover why Kokusai Electric's fair value indicates an 8% potential upside to its current price before the market closes that gap.
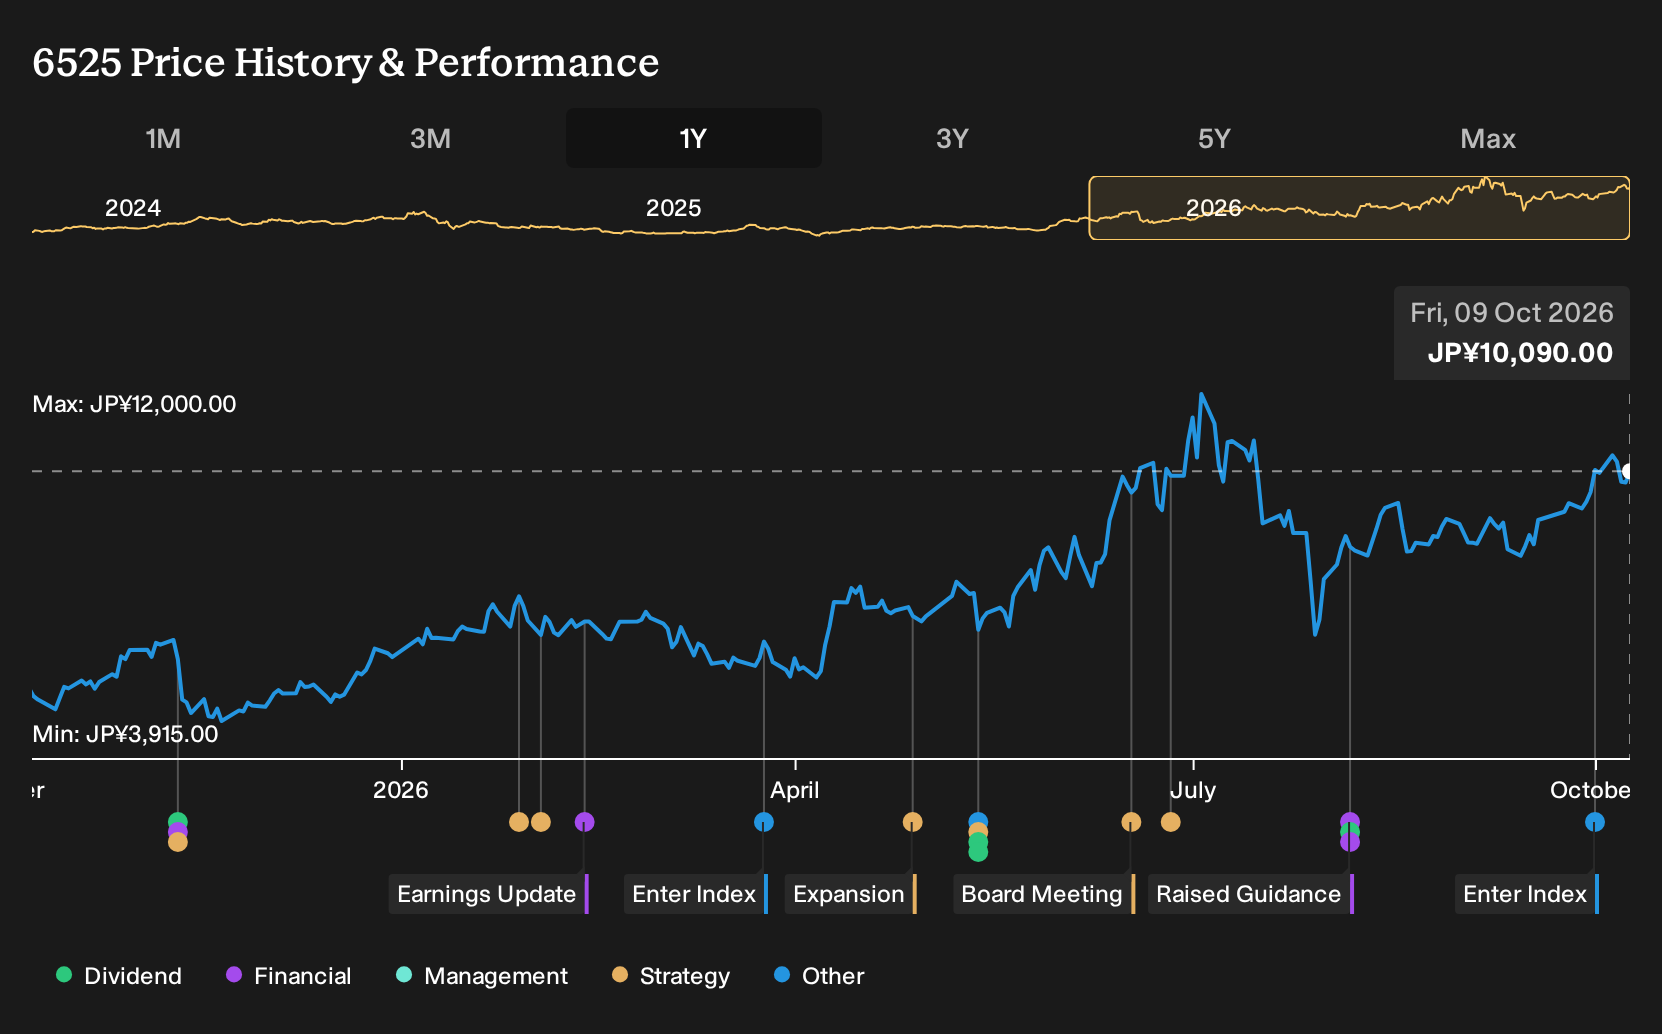
Exploring Other Perspectives
The biggest point of friction comes from geopolitics. While the baseline view leans on demand for advanced chip tools, the most cautious analysts worry export controls could cap Kokusai Electric’s reach. They were pencilling in ¥437.0 billion of revenue and ¥93.1 billion of earnings by 2029, before this Nikkei 225 inclusion, which might prompt them to rethink.
Explore another Kokusai Electric fair value estimate, including one that suggests as much as 52% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Kokusai Electric research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Kokusai Electric. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kokusai Electric's overall financial health at a glance.
Looking For More Ideas Beyond Kokusai Electric?
If the Kokusai Electric story has sharpened your thinking about risk, growth and balance sheet strength, it can be useful to line it up against a wider set of opportunities using the Simply Wall St Screener.
- For investors who want quality on sale, scan a curated group of companies that look attractively priced on both fundamentals and valuation signals using the 13 high quality undervalued stocks.
- If you care most about resilience through the cycle, focus on businesses with stronger finances and lower leverage identified in the 23 resilient stocks with low risk scores.
- When you are hunting for lesser known opportunities with solid financial underpinnings, cast a wider net with the 74 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com