


What United Microelectronics Holders Got Right Before A 229% Run
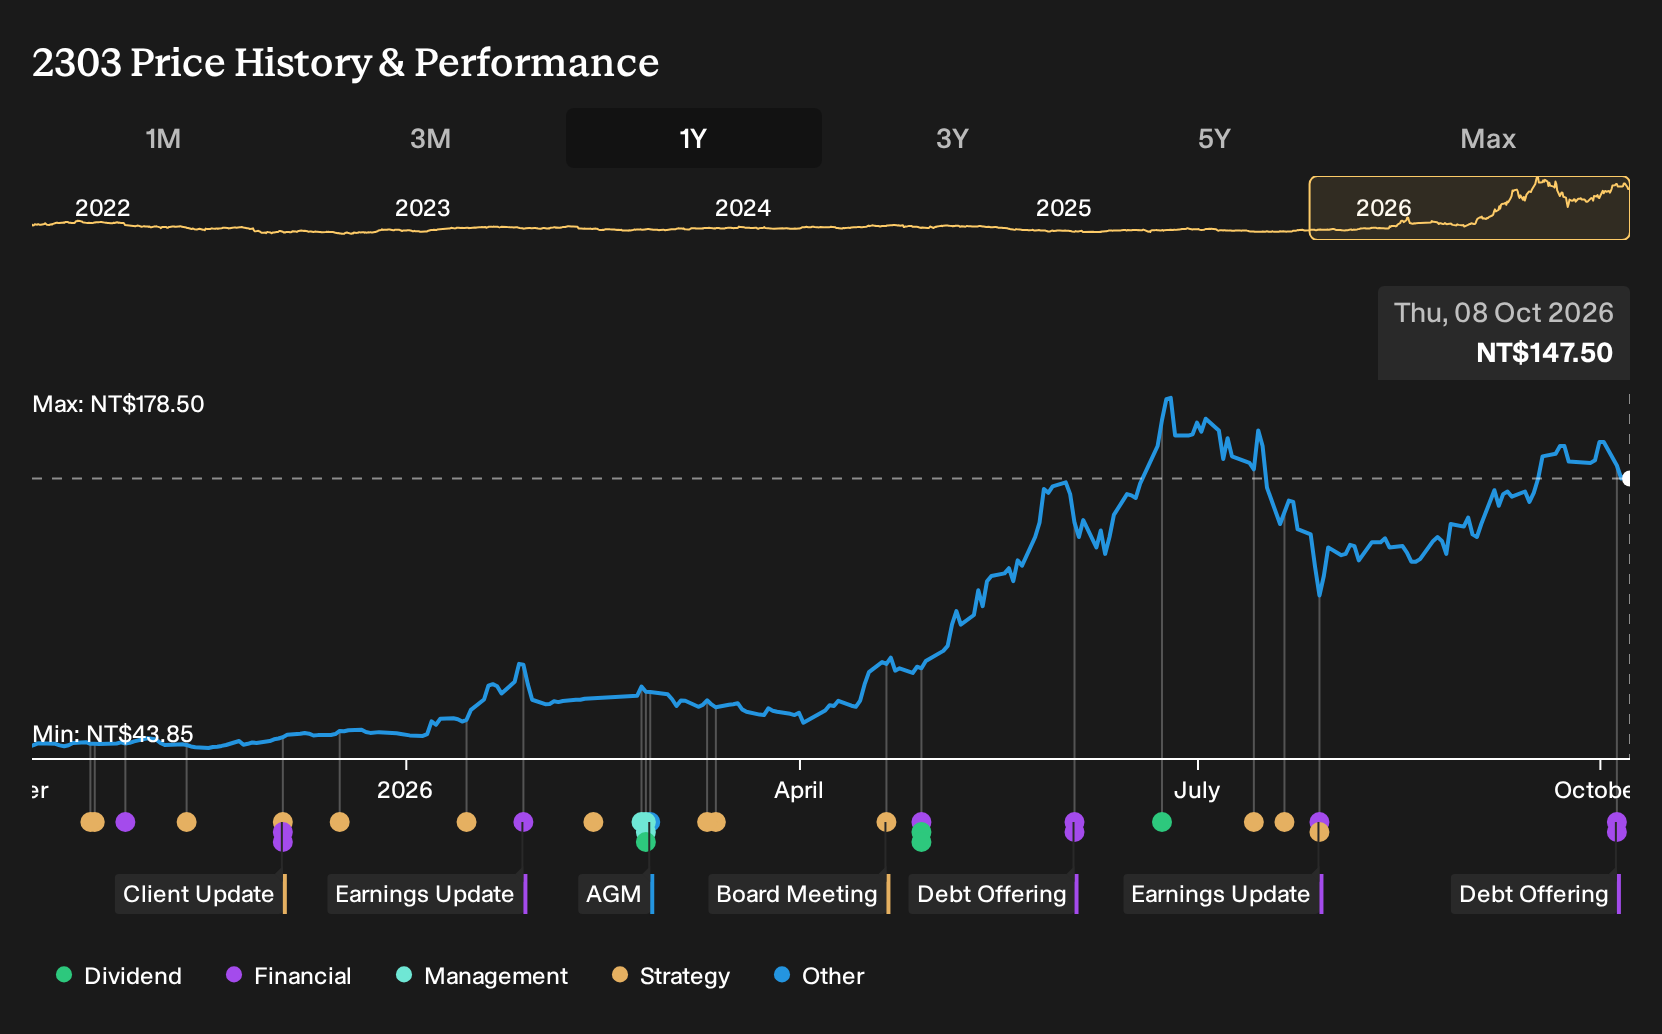
If United Microelectronics sat on a watchlist instead of in a portfolio, the past year likely feels expensive. For United Microelectronics shareholders, the return over the past year was 228.6%, including dividends. That outcome invites a harder look at what was already on record in October 2025. Were robust expectations for specialty 22 and 28 nanometer demand and high fab utilization the key business assumptions that could have signalled this as more than just another cyclical foundry story?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
The easy part of this move is behind United Microelectronics. Zero in on 178 high quality undervalued stocks for companies trading below our estimates.
The Two United Microelectronics Stories Investors Had To Weigh
The shares cost NT$44.8 at the start of the period, which left you choosing between two very different stories about United Microelectronics.
The bullish narrative put fair value at NT$60. It leaned on specialty 22 and 28 nanometer demand, and on the idea that deep customer partnerships could support higher margin, less cyclical revenue.
The bearish view pointed to fair value of NT$32. That case focused on mature node dependence, and on the risk that global self sufficiency policies could spur overcapacity and heavy pricing pressure.
What The Results Changed For United Microelectronics
The clearest piece of evidence was the Q2 2026 earnings line. Net income moved from NT$8,902.53 million in Q2 2025 to NT$42,259.962 million in Q2 2026, and net margin shifted from 15.2% to 61.5%. Revenue moved from NT$58,757.657 million to NT$68,732.662 million. Taken together, those figures supported a more positive narrative around United Microelectronics’ profitability.
The useful takeaway is simple. When a story rests on higher margin specialty demand and stronger pricing, you can test it by watching net income and net margin together, then checking whether they move in the direction implied by that thesis.
What United Microelectronics' Run Up Already Assumes
With United Microelectronics now at NT$148, this Narrative’s Fair Value sits below the current price and frames the stock as already pricing in a demanding outcome.
The core tension is simple. You would be assuming future projects earn enough to comfortably cover heavier capital spending. The question is how rising depreciation against mature end markets tests that belief.
"The numbers imply the share price already credits United Microelectronics with successfully scaling AI related and specialty revenues while absorbing higher capex and depreciation without a material hit to profitability. United Microelectronics is positioning advanced packaging and 12 inch silicon photonics as new growth pillars."
One Narrative disagrees with today's price. → See where this Narrative says United Microelectronics should trade
Where United Microelectronics’ Demand Connects
United Microelectronics depends on steady chip orders. Those same AI systems also need somewhere to store and recall their data.
It is not only logic wafers that matter. Another specialist focuses on memory and storage that keep training runs and inference workloads supplied.
This provider sells the capacity that holds models, datasets and context. Without that layer, expensive accelerators can sit idle, waiting for information.
As AI spreads from clouds into cars, devices and factories, that memory supplier faces its own set of scale decisions and capital choices.
That argument has a Narrative and a number behind it. → See the company one Narrative values 21% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com