


Learn Why The Bull Case For Molson Coors Stock Could Change Following Margin Pressure
- Molson Coors Beverage is contending with declining unit sales, rising costs that outpace revenue, and a sharp compression in operating margin, which has left the business unprofitable and put pressure on returns from its invested capital.
- The combination of weak margins and challenged returns suggests Molson Coors may need to rethink its product and cost structure to better align capacity, pricing, and consumer demand across beer, beyond beer, and non-alcoholic offerings.
- We will now look at how Molson Coors Beverage's investment narrative is affected by its weaker margins and current lack of profitability.
Broaden your watchlist beyond Molson Coors Beverage by scanning our hand picked 31 resilient stocks with low risk scores. This group may offer sturdier fundamentals than a brewer wrestling with weak margins and soft demand.
Molson Coors Beverage Investment Narrative Recap
For Molson Coors Beverage to make sense in a portfolio, you would need to believe the brewing group can turn its current loss making position into sustainable profit by tightening costs and lifting returns on each dollar invested. The short term swing factor is whether the cost savings program and mix shift away from struggling core beer can slow the recent margin compression.
The biggest risk right now is that soft demand in core beer, combined with high input costs, keeps undercutting that margin repair effort. If weak volumes persist while freight, fuel and aluminum stay expensive, the business could see further operating deleverage and a slower path back to acceptable returns.
Recent commentary around Molson Coors Beverage has centered on the three year US$450m cost savings plan and network changes such as brewery closures. That initiative directly relates to the current pressure on operating margin, because rising costs have already outpaced revenue and pushed the group into a loss. Execution on this program is the clearest near term lever for improving performance.
The same updates also highlighted mix exposure to beyond beer and non alcoholic products, with Monaco Cocktails and Fever Tree already contributing a small share of net sales. For you as an investor, these newer categories connect to the catalyst narrative that higher margin offerings, together with cost efficiencies, could help offset a sluggish U.S. beer market and intense discounting in markets such as the U.K.
Molson Coors Beverage's current analyst storyline points to revenues of US$11.2b and earnings of US$946.8m by 2029, based on a flat top line over the next 3 years. This implies earnings would need to swing by roughly US$3.2b from today’s loss of US$2.3b to reach that profit level.
Uncover why Molson Coors Beverage's fair value indicates a 22% potential upside to its current price before that discount to expectations narrows.
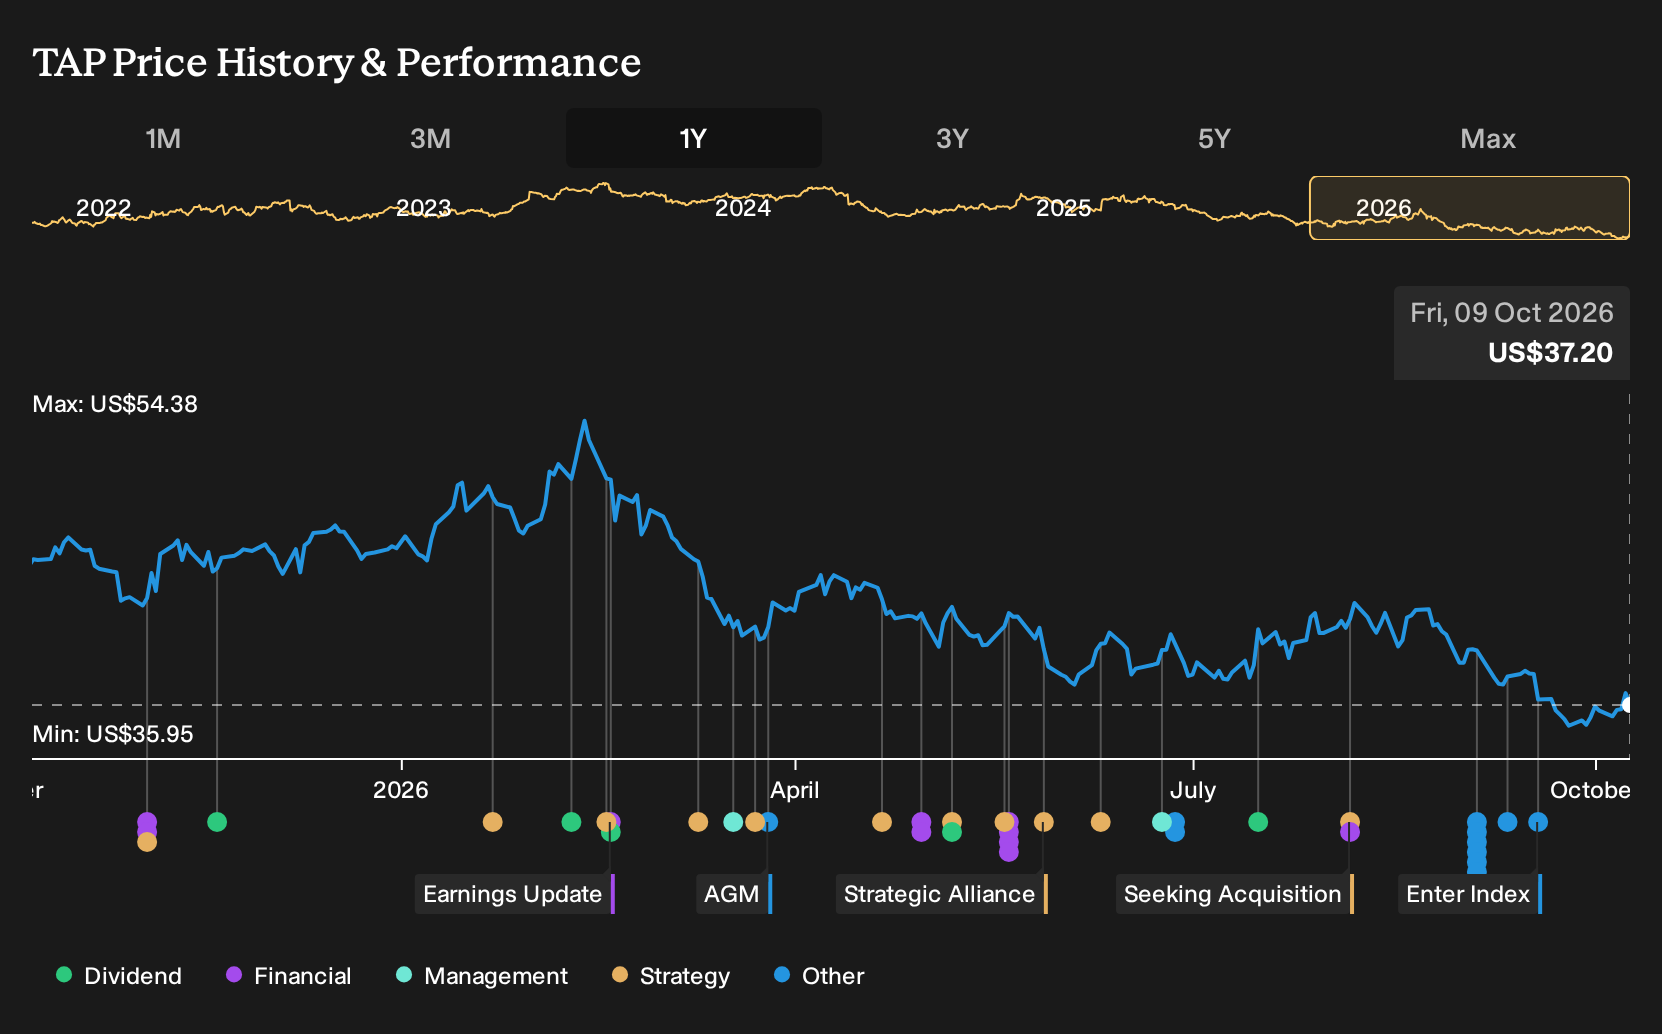
Exploring Other Perspectives
One alternative view on Molson Coors Beverage puts far more weight on the Horizon 2030 plan and the US$450m cost savings effort as a potential earnings engine. The most optimistic analysts were pencilling in flat to slightly higher revenue of about US$11.7b and earnings near US$1.5b by 2029 before this news, so opinions clearly span a wide range and may shift as fresh information lands.
Explore 4 other Molson Coors Beverage fair value estimates, including one that suggests potential upside of as much as 305% from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Molson Coors Beverage research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Molson Coors Beverage. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Molson Coors Beverage's overall financial health at a glance.
Looking for more investment ideas beyond Molson Coors Beverage?
If Molson Coors Beverage has you thinking harder about risk, income, or long term value, broaden your watchlist with a few targeted stock groups built using the Simply Wall St Screener. Each one filters for a different edge so you can focus quickly on the type of opportunity that matters most to you.
- If capital protection sits near the top of your priorities, you can start with a group of companies that screen for resilience through the 31 resilient stocks with low risk scores, which aim to combine steadier financial profiles with lower measured risk.
- For readers focusing on value, consider a focused universe of potentially mispriced businesses through the 29 high quality undervalued stocks, which concentrates on quality and pricing signals.
- If income is a central goal for your portfolio, you can review a pool of high yielding payers via the 8 dividend fortresses, which concentrates on stocks offering 5%+ dividend yields.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com