


MSC Industrial Direct (MSM), What Is Drawing Fresh Attention Now?
MSC Industrial Direct (MSM) has drawn fresh attention after recent share performance data highlighted a mix of short term softness alongside stronger longer term gains, prompting investors to reassess the distributor’s role in industrial supply chains.
Recent trading suggests momentum for MSC Industrial Direct is cooling. The share price return of 7.47% over 30 days and 4.45% over 90 days sits against a much stronger year-to-date share price gain of 50.87% and a 1-year total shareholder return of 56.87%.
Scan how MSC Industrial Direct’s momentum compares with peers by checking similar industrial distributors in our hand picked list of solid balance sheet and fundamentals (25 results) for potential next ideas.
After a near 51% year to date surge, MSC Industrial Direct now trades within a fraction of the average analyst target, yet screens at a sizable premium to some fair value estimates. Is that caution signal from the models deserved?
Most Popular Narrative: 1% Undervalued
On the most followed view of MSC Industrial Direct, the $131.00 fair value estimate sits just above the last close at $129.51. This leaves almost no valuation gap and puts the focus squarely on execution rather than multiple expansion.
The expansion of MSC Industrial Direct's In-Plant programs and vending machine installations remains a live driver, with vending machines at about 30,800 units and in-plant programs at 426. Both channels are reporting mid teens average daily sales growth, which continues to support future revenue and earnings potential as these solutions scale from a larger base.
See why 10 investors see MSC Industrial Direct as 1% undervalued.
Result: Fair Value of $131.00 (ABOUT RIGHT)
Still, soft demand that previously saw average daily sales decline, along with recent volume pressure and tariff and cost risks, could quickly challenge this fair value narrative.
Find out about the key risks to this MSC Industrial Direct narrative.
Another Take On MSC Industrial Direct’s Valuation
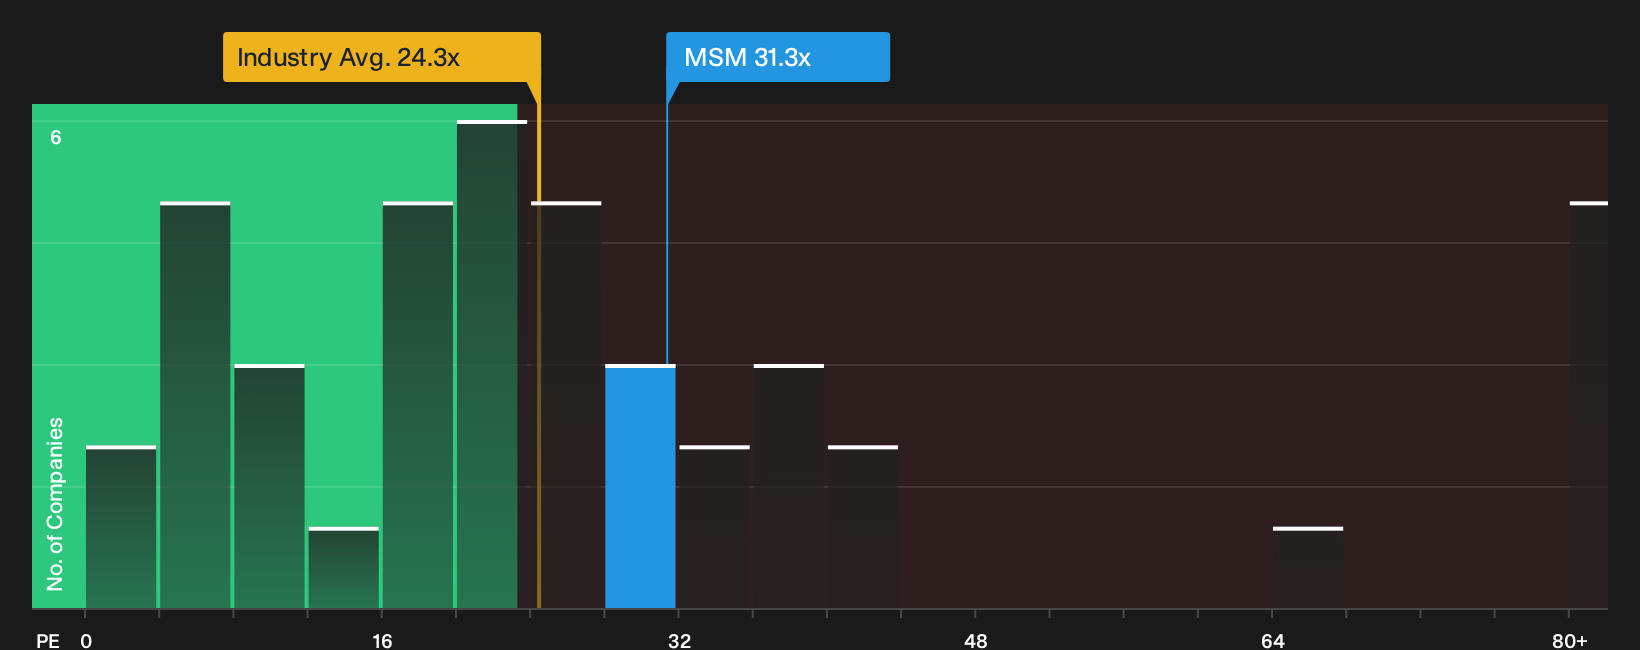
The first view framed MSC Industrial Direct as roughly in line with a $131.00 fair value. A different lens tells a tougher story. The current P/E of 31.3x sits well above the US Trade Distributors group at 24.3x and a fair ratio of 20.5x. That pricing gap points to meaningful valuation risk if sentiment cools rather than further upside.
The P/E premium raises a simple question: How confident are you that MSC Industrial Direct’s execution will convince the market to keep paying so far above that fair ratio?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this MSC Industrial Direct debate feels finely balanced, act quickly and review the numbers yourself so the conclusion is yours, not the market’s. To see what investors find most encouraging in the current setup, start with 3 key rewards.
Looking for more MSC Industrial Direct style ideas?
You have seen what MSC Industrial Direct looks like on the numbers. Do not stop there. Broaden your watchlist with fresh, data backed ideas today.
- Target sturdier balance sheets and fundamentals by reviewing our focused list of solid balance sheet and fundamentals (25 results) that filters for financially resilient businesses.
- Pursue better value by scanning the 29 high quality undervalued stocks that highlights companies with strong fundamentals trading below their assessed worth.
- Strengthen your income lineup by checking the 8 dividend fortresses to spot higher yielding candidates with an emphasis on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com