


Ambu (CPSE:AMBU B) Board Addition Puts Fair Value Back In Focus
Board change puts Ambu in focus
Ambu (CPSE:AMBU B) has drawn fresh attention after appointing Jose Ignacio Abia Buenache as an observer to its Board, introducing a high profile healthcare operator to the governance table.
Abia serves as Chief Executive Officer and Board member at Grifols and previously held senior roles at Olympus Corporation for more than two decades, experience that many investors will now weigh against Ambu’s current share performance and valuation profile.
Recent trading has turned more positive for Ambu, with a 1 month share price return of 11.39% and a 7 day gain of 8.17%, although the share price return year to date is still down 15.54% and the 1 year total shareholder return has fallen 29.01%. This leaves the recent bounce looking more like early momentum than a full change in trend as investors digest both this boardroom addition and earlier operational updates.
Scan how Ambu compares with other potential healthcare opportunities by reviewing a curated group of 127 healthcare AI stocks that investors are watching for the next leg of momentum.
Ambu has climbed in the past month while the longer track record still shows sizeable declines. Is this latest move a signal of improving fundamentals, or just a swing in sentiment that the current valuation needs to answer?
Most Popular Narrative: 11% Undervalued
Simply Wall St's most followed narrative currently estimates Ambu's fair value at DKK81.77 using a 5.78% discount rate, compared with the last close at DKK72.85. This puts the latest boardroom move against a backdrop of earnings and margin expectations already built into valuation models.
Scaling of manufacturing capacity (notably the ramp-up of the Mexico facility and ongoing automation and optimization efforts) provides operational leverage. This should allow for improved gross and EBIT margins as volume grows and more products for key markets are sourced closer to customers, which may offset some tariff and FX cost headwinds.
See why 7 investors see Ambu as 11% undervalued.
Result: Fair Value of DKK81.77 (UNDERVALUED)
Still, the Ambu story carries clear risk triggers, including rising single use endoscopy competition and the possibility that higher costs will continue to pressure future margins.
Find out about the key risks to this Ambu narrative.
Another View on Ambu’s Valuation
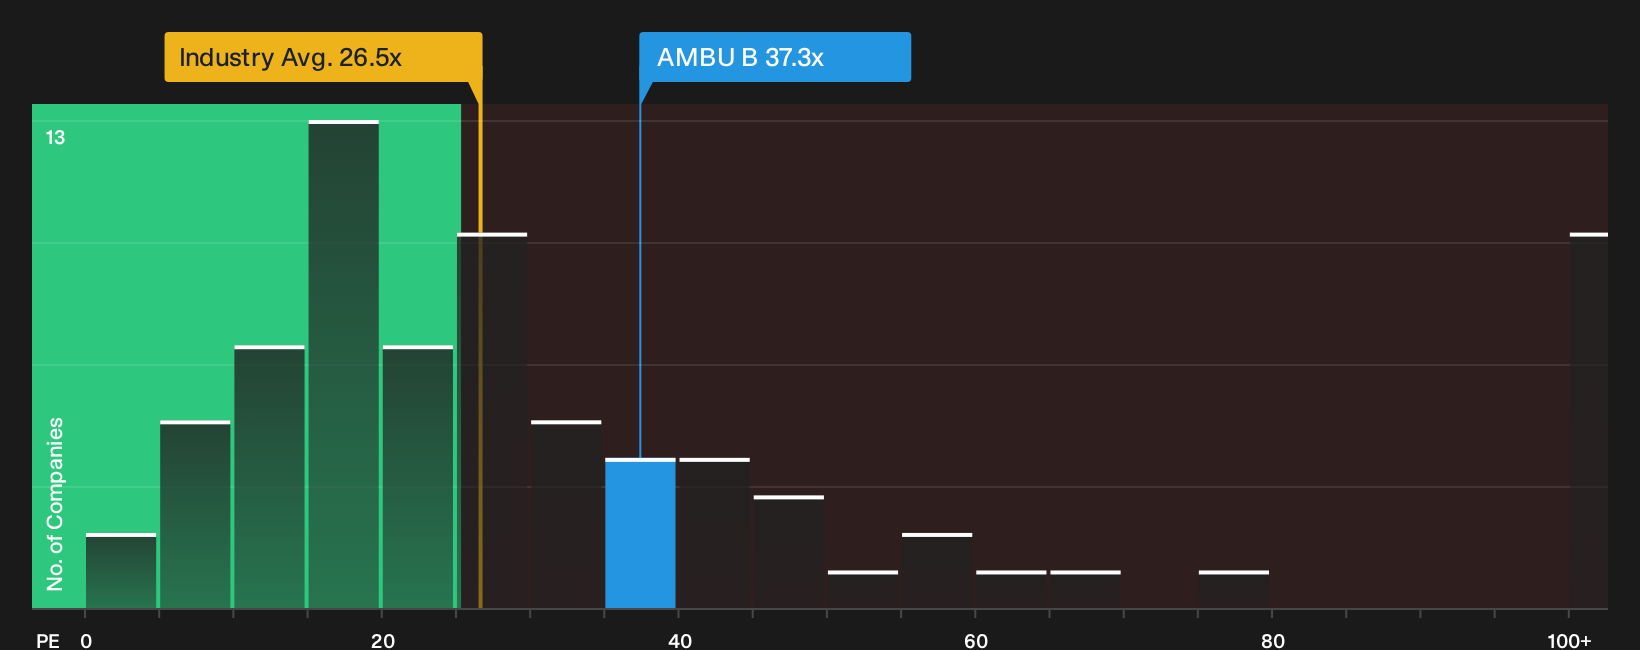
The Simply Wall St fair value model points to Ambu trading at a 52.8% discount to its estimate of worth, yet the current P/E of 37.3x sits well above the European Medical Equipment industry at 26.5x and the peer average at 28.9x, and even above a fair ratio of 28.8x. For a holder, that mix of apparent discount on one model and premium on earnings raises a simple question: Which signal deserves more weight in your own framework?
To unpack how that earnings multiple could adjust over time, and what it might mean for upside or downside risk, review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Ambu's valuation and board changes can feel unclear. Move quickly to review both sides of the story for yourself with 3 key rewards and 1 important warning sign.
Looking for more Ambu investment ideas?
Do not stop your research with Ambu alone. The market moves fast, and fresh opportunities do not wait. Use the Simply Wall St Screener now to spot quality setups before they become crowded and harder to act on.
- Target potential mispricings early by reviewing a 178 high quality undervalued stocks that might offer a more attractive entry point than widely followed large caps.
- Secure stability in your portfolio by focusing on a list of solid balance sheet and fundamentals (204 results) that can better withstand shocks and funding pressure.
- Get ahead of the crowd by scanning a 618 high quality undiscovered gems that have strong fundamentals but limited current attention from the broader market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com