


Cronos Group (TSX:CRON) Earnings Beat Puts Valuation Back In Focus
Cronos Group (TSX:CRON) is back in focus after better than expected Q2 2026 results, with strong revenue growth, improving margins, and a pending Netherlands acquisition drawing fresh attention to the stock’s recent gains.
At a CA$4.62 share price, Cronos Group has seen momentum build, with a 30 day share price return of 6.94% and a 90 day share price return of 17.86%. The 1 year total shareholder return of 31.25% and 3 year total shareholder return of 81.18% point to a much stronger recent phase than its 5 year total shareholder return, which declined 31.76%.
Scan beyond Cronos Group’s recent surge and size up other cannabis players showing similar momentum with the hand picked 9 high quality undiscovered gems in this corner of the market.
Cronos Group just posted a sharp run and a rich Q2 profit margin. The live question now is whether the real upside sits ahead of investors or already sits in the rear view mirror as the valuation math unfolds next.
Most Popular Narrative: 12% Undervalued
Cronos Group is framed as modestly underpriced in the most followed narrative, with a fair value of CA$5.24 versus the CA$4.62 last close. This puts the focus on whether that valuation gap holds as forecasts and sentiment shift.
Strategic investment capacity, highlighted by a strong balance sheet with $834 million in cash and zero debt, enables Cronos to pursue further product innovation, international expansion, and value-accretive partnerships, positively impacting net margins and future earnings growth. Reduced operating expenses and a strategic revenue mix shift toward higher-priced international markets are leading to material improvements in adjusted EBITDA and gross margin, setting the stage for a return to sustained profitability.
See why 10 investors see Cronos Group as 12% undervalued.
Result: Fair Value of CA$5.24 (UNDERVALUED)
Still, the Cronos Group story depends heavily on GrowCo capacity coming through as planned and on regulatory decisions in markets like Israel and Germany not turning less favourable.
Find out about the key risks to this Cronos Group narrative.
Another View On Cronos Group’s Valuation
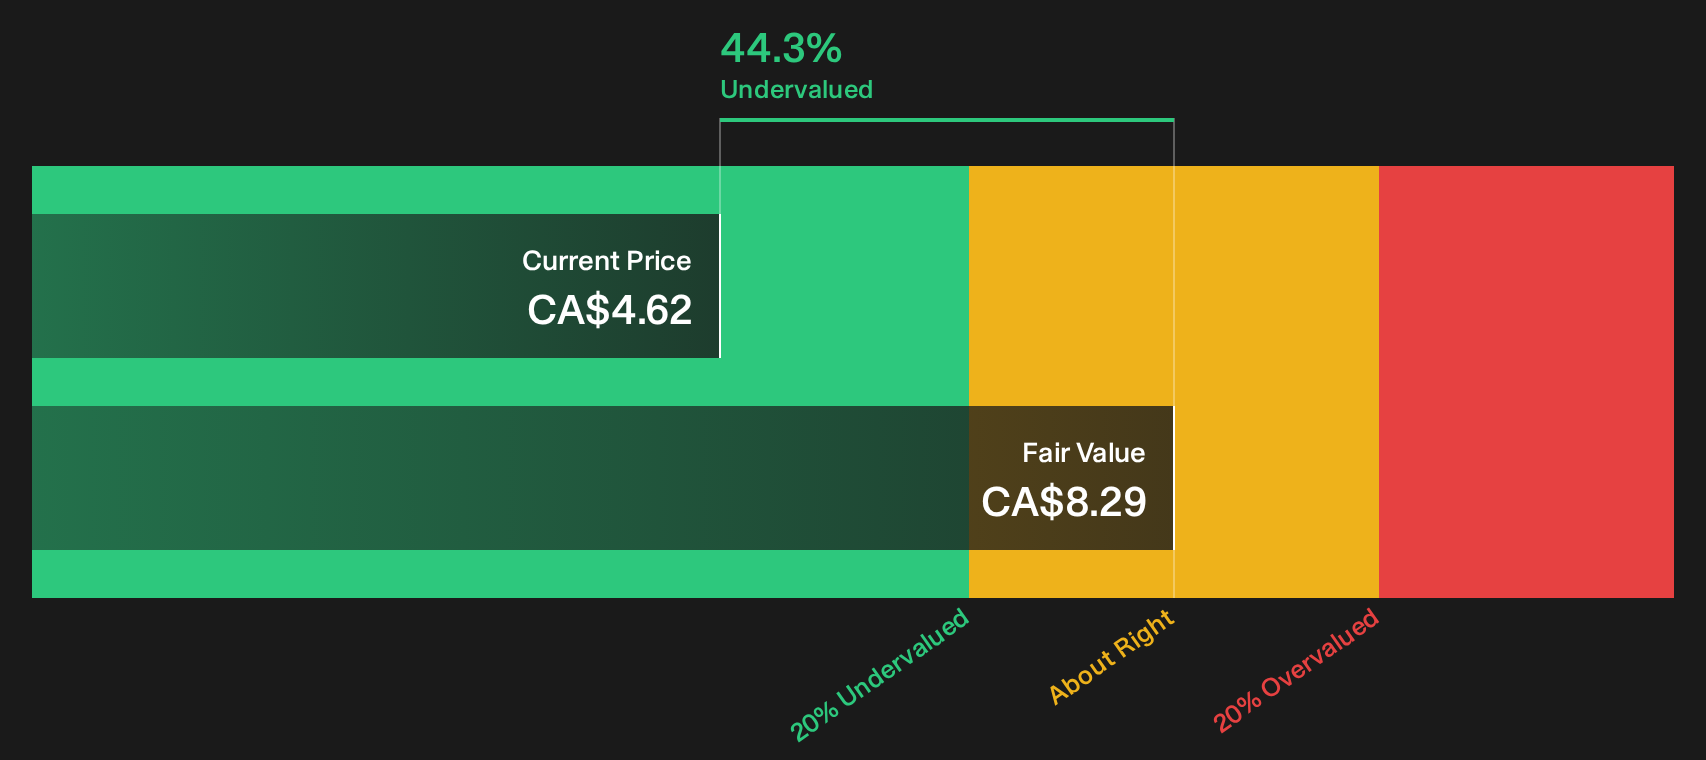
The narrative leans on analyst targets and implied fair value around CA$5.24. Yet the SWS DCF model paints a different picture, with Cronos Group trading at roughly a 44% discount to its estimated future cash flow value of CA$8.29. That gap raises a simple question: Which story should you trust more, earnings multiples or cash flow math?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If the mixed sentiment around Cronos Group has you on the fence, move quickly from headline takeaways to your own scoreboard by weighing both sides of the story through 3 key rewards and 1 important warning sign.
Looking for more ideas beyond Cronos Group?
Cronos Group might be on your radar now, but you do not want to miss other potential opportunities lining up in different corners of the market.
- Target resilient cash generators by scanning a 8 high quality undervalued stocks that combines quality fundamentals with pricing that may not fully reflect underlying strength.
- Build a steadier income stream by reviewing a 3 dividend fortresses that screens for higher yielding companies with a focus on durability.
- Prioritise capital protection by searching a 7 resilient stocks with low risk scores aimed at businesses with balance sheets and risk profiles that may better handle shocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com