


How Investors May Respond To Sotera Health (SHC) Raised 2026 Outlook
- Sotera Health recently reported Q2 2026 constant currency revenue growth of 8%, raised full year guidance for both revenue and adjusted EBITDA, and completed a CEO transition. Alton Shader took charge with a focus on customer-centric execution.
- Fresh DCF work suggesting Sotera Health’s intrinsic value sits well above its current share price has sharpened attention on whether its heavy investments in EO controls, cobalt 60 capacity and multi-modality sterilization can translate into durable cash generation.
- We will now look at how Sotera Health’s upgraded 2026 outlook could reshape the investment narrative investors have been working with.
Compare Sotera Health's valuation story with other potential underpriced opportunities by scanning our hand picked list of 29 high quality undervalued stocks that pair resilient cash generation with balance sheet strength.
Sotera Health Investment Narrative Recap
To own Sotera Health, you need to be comfortable that outsourced sterilization and lab testing remain essential services with long contracts and relatively predictable volumes. The near term story hinges on whether the Q2 2026 momentum in revenue and adjusted EBITDA, plus raised guidance, can be sustained as new capacity for EO controls and cobalt 60 is brought onstream.
The biggest swing factor right now is execution on that heavy 2026 capital spending while keeping EO litigation and regulatory costs contained. Recent results and the CEO transition do not fundamentally change those drivers. They mostly sharpen attention on how quickly these projects translate into stable earnings and cash flow.
The clearest recent marker for that thesis is Sotera Health’s Q2 2026 update. Constant currency revenue growth of 8% and higher adjusted EBITDA margins, alongside a lift in full year guidance, provide a real time read on how pricing, mix and utilization are holding up as investment ramps.
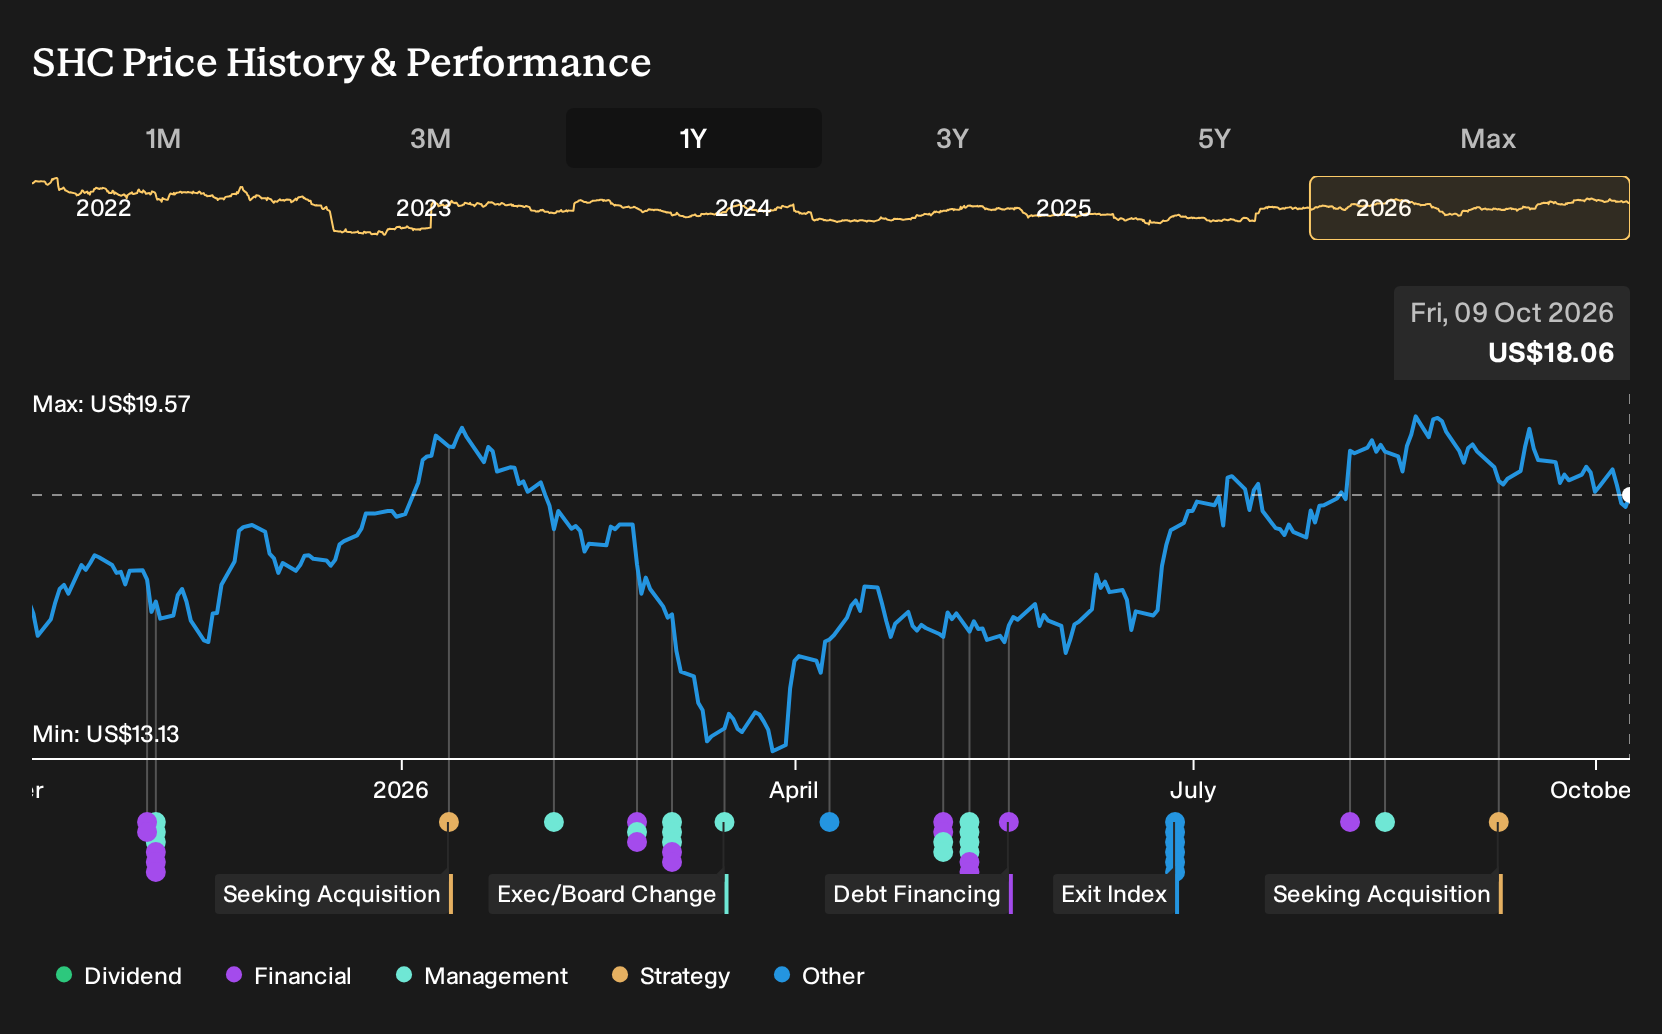
Those numbers matter because the main catalysts are volume growth in sterilization, margin improvement at Nelson Labs, and the eventual step down in capital expenditure after the current US$200 million to US$225 million program. Your call is whether the combination of upgraded guidance and a DCF value that sits above the US$18.06 share price offsets the live risks around EO regulation, litigation and leverage.
Sotera Health's current analyst framework points to revenues of US$1.4b and earnings of US$321.4 million by 2029, based on 5.8% yearly revenue growth and an earnings increase of about US$157.9 million from US$163.5 million today.
Uncover why Sotera Health's fair value indicates a 26% potential upside to its current price, which could narrow quickly if sentiment toward Sotera Health shifts.
Exploring Other Perspectives
The more optimistic twist on Sotera Health focuses on cobalt related capacity. The most bullish analysts were already pencilling in about US$1.5b of revenue and US$359.8 million of earnings by 2029, compared with the lower US$1.4b and US$321.4 million consensus, before this latest guidance and CEO update landed. Those views may shift, so treat them as starting points and compare several angles.
Explore another Sotera Health fair value estimate, including one that suggests there may be as much as 68% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Sotera Health research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Sotera Health. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sotera Health's overall financial health at a glance.
Looking For More Investment Ideas Beyond Sotera Health?
If the Sotera Health story has you thinking about portfolio gaps or fresh angles, it can help to line it up against other businesses with different risk and return profiles using the Simply Wall St Screener.
- For income focused investors who still want financial resilience, compare Sotera Health to companies on our 8 dividend fortresses that aim to pair sizeable payouts with staying power.
- If capital preservation sits near the top of your checklist, scan a 31 resilient stocks with low risk scores to find businesses that score well on balance sheet strength and earnings stability.
- When you want to cast a wider net for quality away from the most followed tickers, broaden your watchlist using a 20 high quality undiscovered gems that highlights under the radar stocks with solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com