


Barrick Mining (B) Faces A 16% Fair Value Gap On Q3 Results Countdown
Upcoming Q3 release puts Barrick Mining in focus
Barrick Mining (B) is moving into the spotlight as it prepares to release third quarter 2026 results before the market opens on Monday, November 9, 2026.
Management plans a live webcast and presentation at 11:00 a.m. ET, followed by a question and answer session with analysts. This will give investors a concentrated window to assess how the miner is tracking against recent share price swings.
Recent trading tells a mixed story for Barrick Mining. The share price is US$41.06 after a 14.25% 90 day share price return, while the 30 day share price return fell 6% and the year to date share price return is down 6.85%.
Over a longer stretch, total shareholder return has been stronger, with a 28.04% 1 year gain and triple digit 3 and 5 year total shareholder returns that suggest momentum built over time rather than a short term swing around this earnings release.
Scan how Barrick Mining compares with peers by reviewing its latest moves alongside the hand picked 36 elite gold producer stocks ahead of the next round of quarterly updates.
After a 1 year total return of 28.04% and a pullback over the past month, Barrick Mining now sits at a crossroads. Investors may ask whether the current valuation still leaves enough potential upside to justify the risk.
Price-to-earnings of 10.3x for Barrick Mining: Is it justified?
On simple earnings terms, Barrick Mining looks inexpensive. The shares last closed at $41.06, and the stock trades on a P/E of 10.3x that sits well below both the wider US market and the metals and mining group it belongs to.
The P/E ratio compares the current share price with earnings per share. For a producer like Barrick Mining, it gives a quick read on how much investors are paying for each dollar of profit, which is often how large, established miners are weighed up against each other.
Barrick Mining’s current multiple of 10.3x is materially below the US market at 18x and also below the US metals and mining industry average of 17.8x, as well as a peer group average of 17.6x. It also sits well under an estimated fair P/E level of 20.5x, which indicates a level the market could move towards if sentiment and fundamentals stay aligned with that benchmark.
Explore the SWS fair ratio for Barrick Mining.
Result: Price-to-earnings of 10.3x (UNDERVALUED)
Still, Barrick Mining faces clear risk if gold and copper prices weaken, or if major sites like Carlin or Cortez encounter operational setbacks.
Find out about the key risks to this Barrick Mining narrative.
Another view on Barrick Mining’s value
The P/E story points one way, but the SWS DCF model points another. Based on projected cash flows, our DCF estimate sits at $34.58 per share, which is below the current $41.06 price and indicates that Barrick Mining may be overvalued using this approach. Which yardstick do you trust more?
Look into how the SWS DCF model arrives at its fair value.
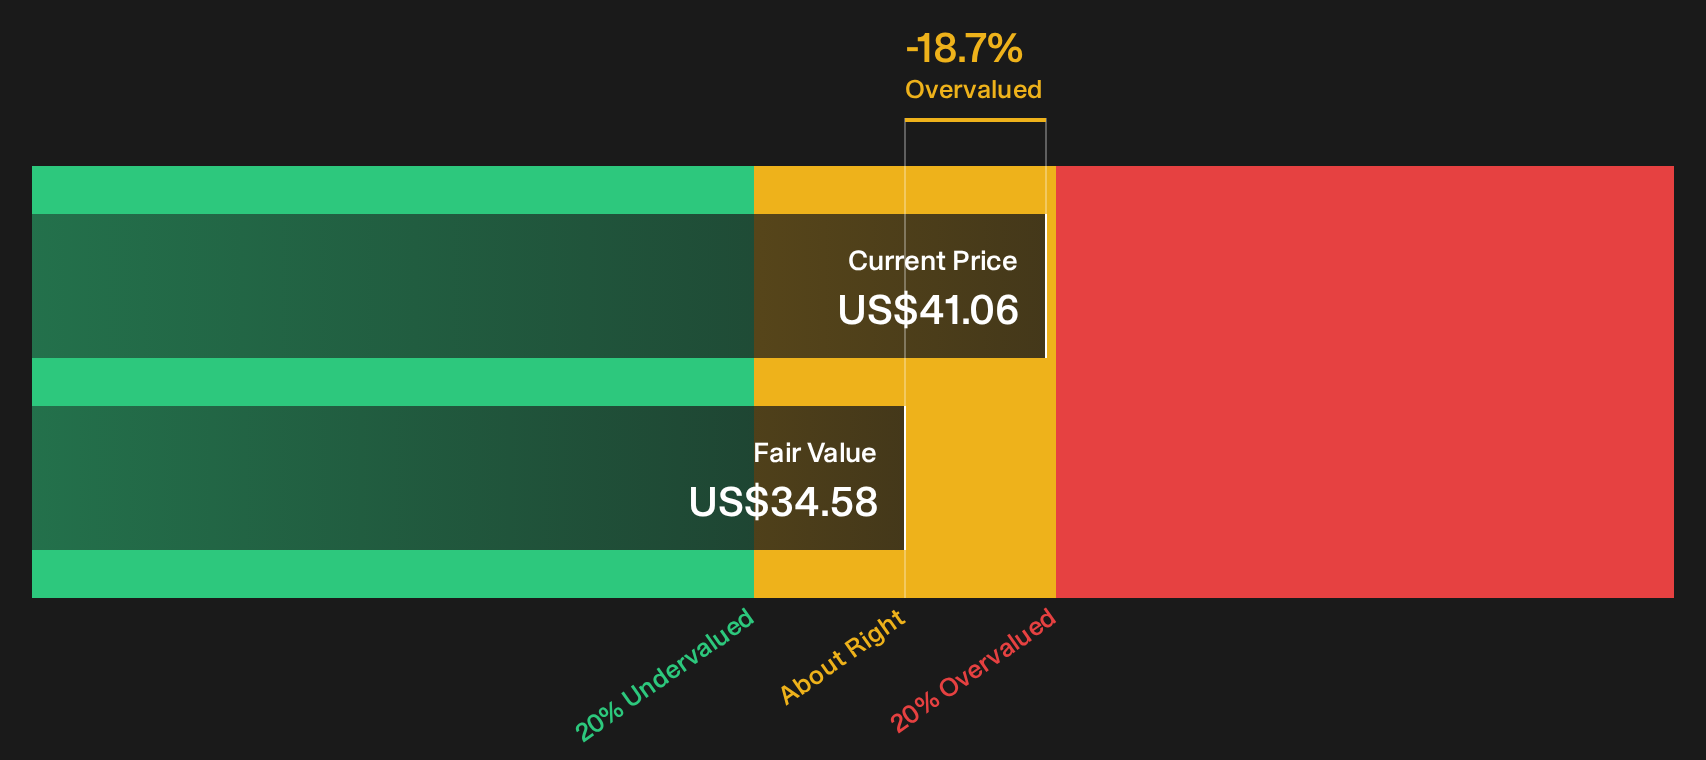
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Barrick Mining for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or clear opportunity? With both risks and rewards in play around Barrick Mining, move quickly from headline impressions to data, then weigh the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Barrick Mining?
Do not stop with Barrick Mining. Broaden your watchlist with other opportunities that match your style, from value setups to income ideas and sturdier balance sheets.
- Target value potential by scanning companies trading on appealing fundamentals through the 29 high quality undervalued stocks.
- Strengthen your income focus by reviewing a shortlist of high yield payers in the 8 dividend fortresses.
- Prioritise resilience by filtering for financially robust businesses via the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com