


Aritzia (TSX:ATZ) Lifts Guidance As Q2 Strength Tests Whether The Valuation Still Works
Aritzia (TSX:ATZ) is back in focus after second quarter results showed higher sales, a sharp jump in net income supported by tariff refunds, and upgraded guidance that points to stronger expectations for fiscal 2027.
The Q2 surprise has fed directly into the tape, with Aritzia’s share price jumping 20.5% on the day to CA$146.91 and delivering a 1-month share price return of 19.6%. The 1-year total shareholder return of 70.8% and a very large 3-year total shareholder return of more than 5x signal strong longer term momentum, even though the 90-day share price return slipped 1.8% before this earnings rebound.
Capitalize on the momentum around Aritzia by scanning a curated 9 high quality undiscovered gems that may be flying under most investors' radar.Bulls see Aritzia’s Q2 surge and richer 2027 outlook as validation of the premium. Bears point to tariff refunds and a fast US buildout as temporary or risky. Which side does today’s valuation actually support?
Most Popular Narrative: 21% Undervalued
Aritzia’s most followed narrative pegs fair value at CA$185.21, meaning the CA$146.91 close trades at a sizeable discount while still assuming a premium P/E and healthy profitability.
Aritzia's geographic expansion strategy, particularly in the United States, has shown strong performance and presents significant growth potential through ongoing boutique openings. This is likely to drive revenue growth.
See why 64 investors see Aritzia as 21% undervalued.
The narrative uses a 7.47% discount rate and assumes revenue growth of 17.76% a year, profit margins near 13.15%, and a future P/E of about 30x. That combination supports the CA$185.21 fair value estimate and underpins analyst confidence that the stock can justify a premium if those cash flows arrive broadly as modelled.
Result: Fair Value of CA$185.21 (UNDERVALUED)
Still, Aritzia’s reliance on aggressive US expansion and higher marketing spend could pressure profitability if new boutiques or digital initiatives underperform expectations.
Find out about the key risks to this Aritzia narrative.
Another View: Aritzia Looks Expensive On Earnings
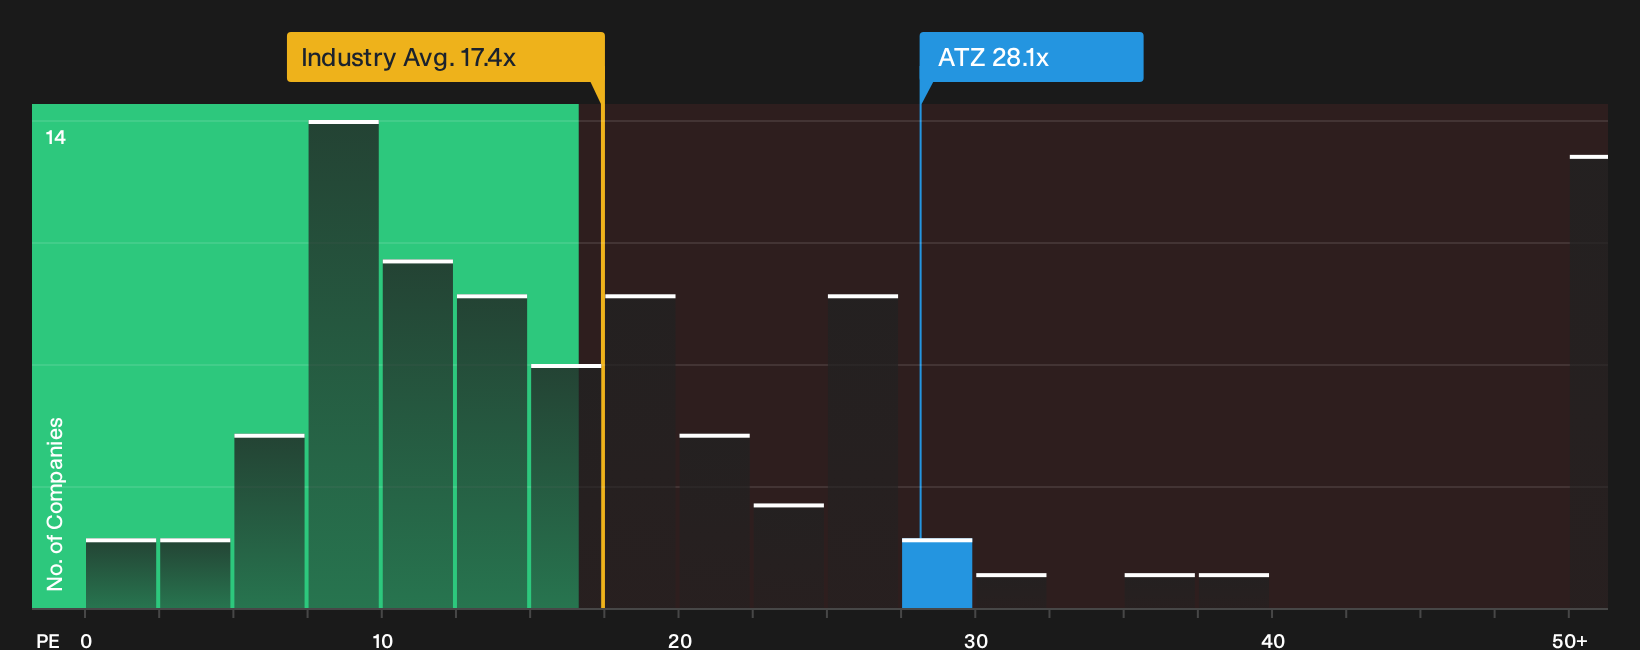
The story changes once you shift from Aritzia’s fair value models to the plain P/E tag. The stock trades on 28.1x earnings, compared with 17.4x for the North American specialty retail group and a fair ratio of 27x, which suggests less room for error if sentiment cools.
That gap versus both the sector and the fair ratio indicates valuation risk if growth or margins soften faster than expected, even though the peer average sits much higher at 63.9x. Is the premium multiple a cushion or a ceiling from here?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or clear message? Momentum, premium pricing, and a blend of 1 or more risks and 1 or more rewards leave room for debate. Move fast, dig into the underlying data yourself, and weigh the 4 key rewards and 1 important warning sign.
Looking for more Aritzia sized investment ideas?
If you stop at Aritzia, you risk missing other opportunities that fit your style, your risk tolerance, and your return goals in very different ways.
- Target resilient compounding by scanning a 7 resilient stocks with low risk scores that filters for companies aiming to keep volatility and risk scores in check.
- Prioritise quality at a reasonable price by running through a curated 8 high quality undervalued stocks focused on strong fundamentals at less demanding valuations.
- Build income potential into your watchlist by assessing a 3 dividend fortresses that concentrates on 5%+ yields with a focus on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com