


Kratos Defense & Security Solutions (KTOS) Lands New Space And Missile Milestones, Is The Valuation Too Rich?
Kratos Defense & Security Solutions (KTOS) is back on investor radars after a string of technical milestones, including a successful 5G NR NTN connectivity trial on its OpenSpace platform and validation of the GEK800 missile engine.
Kratos Defense & Security Solutions has attracted fresh attention after the OpenSpace 5G NR NTN trial, over US$100 million in new space and cyber contracts, GEK800 engine validation with GE Aerospace, and buying interest from Cathie Wood’s ARK funds.
Even with those catalysts, the stock has given up ground recently, with the 30 day share price return down 9.3% and the year to date share price return down 46.6%. At the same time, longer term total shareholder returns of about 150% over three years and 88% over five years point to a very different experience for investors who held through earlier cycles.
Scan beyond Kratos Defense & Security Solutions and size up other contractors riding similar defense and space demand with our hand-picked 91 robotics and automation stocks.
After that kind of pullback in Kratos Defense & Security Solutions, the real tension is simple. Do you commit at today’s price, or wait and hope the valuation resets further first?
Most Popular Narrative: 59% Undervalued
Kratos Defense & Security Solutions most followed valuation storyline puts fair value at about $102.19 against a last close near $42.36. The current share price therefore sits well below what that framework implies, even after accounting for rich assumptions on growth and profitability.
Kratos' early investments in serial production of tactical drones (e.g., Valkyrie) and rapid scaling in missile propulsion and microelectronics put it ahead of competitors as demand for unmanned and autonomous solutions escalates globally. With sole-source and first-to-market positions, Kratos is poised for significant incremental revenue and higher-margin growth as large contracts come online, particularly as international orders (with premium margins) ramp up.
See why 158 investors see Kratos Defense & Security Solutions as 59% undervalued.
This widely referenced model leans on a 7.97% discount rate and assumes earnings can climb from $30.9 million to $188.7 million by around 2029, with profit margins improving from 2.0% to 6.4%. It also includes annual revenue growth assumptions above 20% and a future P/E of 156.7x those 2029 profits, which is much higher than the 35.3x multiple cited for the broader US Aerospace & Defense group in the same framework.
That kind of gap means the fair value is highly sensitive to execution on production ramps, cash generation and contract conversion, as well as to how long investors stay comfortable assigning a premium multiple to Kratos Defense & Security Solutions relative to peers. If margins, growth or investor appetite for paying that level of P/E end up lower than modeled, the $102.19 figure would likely need to be revised, and the apparent 59% discount would shrink.
Result: Fair Value of $102.19 (UNDERVALUED)
Still, Kratos Defense & Security Solutions leans heavily on government budgets and upfront spending on new facilities, so any contract delays or weaker cash conversion could puncture that 59% undervalued story quickly.
Find out about the key risks to this Kratos Defense & Security Solutions narrative.
Another View: Kratos Defense & Security Solutions Looks Expensive On Sales
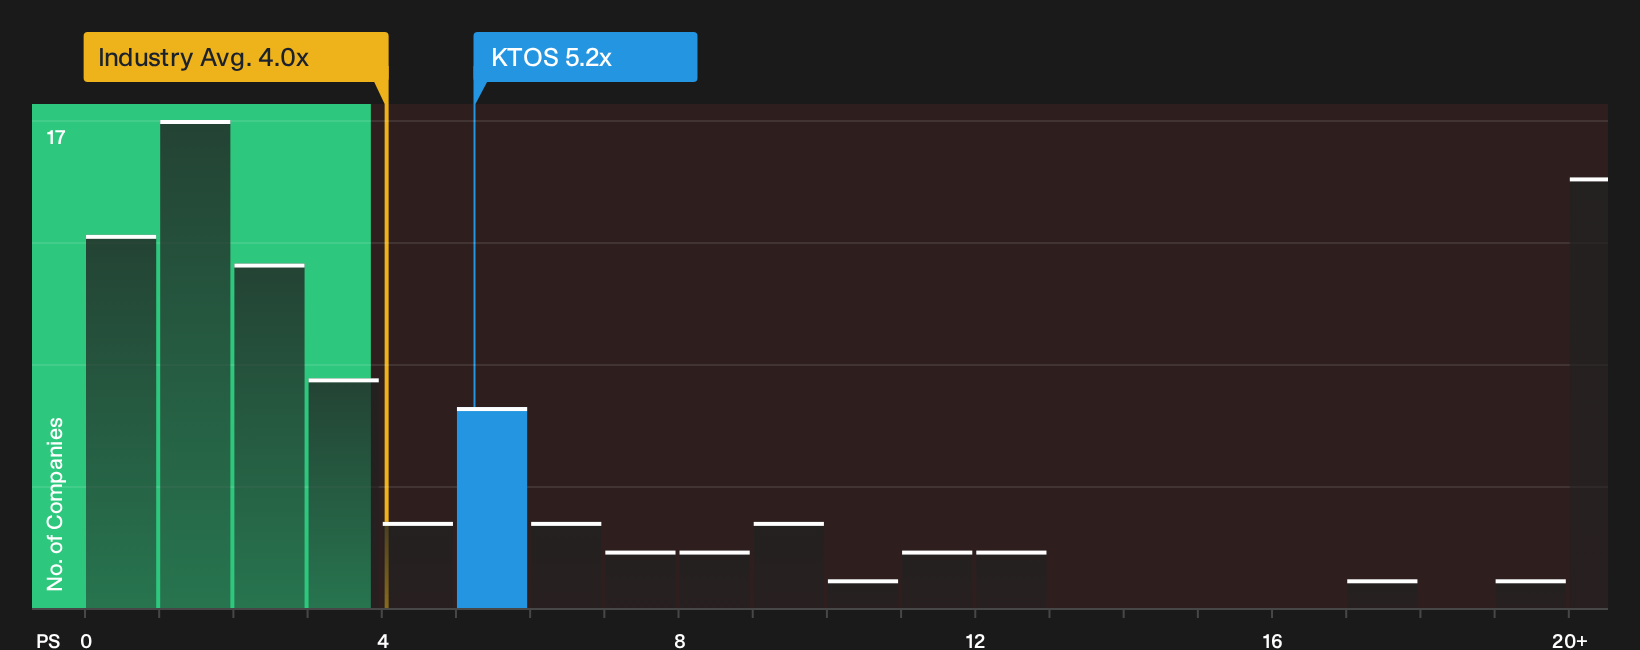
The DCF work suggests Kratos Defense & Security Solutions trades only about 2.6% below an estimated fair value of $43.48. On simple P/S though, the stock changes hands at 5.2x compared with 4.0x for the US Aerospace & Defense group and a 3.0x fair ratio, which points to rich expectations baked into today’s price. If growth or margins slip from the bullish narrative, how quickly could that premium unwind?
See what the numbers say about this price in our valuation breakdown, then compare Kratos Defense & Security Solutions with peers before making any move, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals so far on Kratos Defense & Security Solutions, and that is exactly why you should move quickly, interrogate the numbers yourself and weigh both sides of the story. To see how the balance of concerns and potential upsides stacks up in one place, start with these 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Kratos Defense & Security Solutions?
Consider expanding your research beyond Kratos Defense & Security Solutions by benchmarking other opportunities using focused stock lists built from clear, transparent rules.
- Target stability first by reviewing companies that show resilient balance sheets and solid fundamentals with our list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced quality by scanning a curated set of attractively valued businesses in the 29 high quality undervalued stocks.
- Spot early-stage potential by checking a filtered group of smaller, under-the-radar prospects using the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com