


How Cosalá Ramp Up Could Impact Americas Gold and Silver Stock (TSX:USA)
- Americas Gold and Silver is progressing plans to bring the higher grade EC120 silver copper zone at its Cosalá mine into commercial production by late 2025, while assessing whether antimony recovery can become a viable additional product stream for the operation.
- The focus on antimony, a critical mineral for US supply chains, could reshape how investors think about Americas Gold and Silver’s future revenue mix and project optionality.
- This article examines how Americas Gold and Silver’s investment narrative is influenced by the Cosalá EC120 ramp up and the emerging antimony potential.
Scan other precious and critical metal producers that could be setting up for similar multi-commodity breakouts with our hand picked 36 elite gold producer stocks in this space.
Americas Gold and Silver Investment Narrative Recap
Owning Americas Gold and Silver means believing that higher grade output at Cosalá and ongoing upgrades at Galena can gradually improve a tough cost profile. The EC120 silver copper zone is the key near term swing factor because commercial production targeted around late 2025 could help shift more volume into higher margin tonnes if execution stays on track.
The flip side is clear. The business is still loss making, carries a $100 million senior secured debt facility and has all in sustaining costs that remain elevated. Any stumble in EC120 ramp up, metal prices or cost control could lead to tighter funding options, further dilution or delayed improvement in cash generation.
The most relevant development for this story is EC120 progress at Cosalá. Management is working toward commercial production by the end of 2025, which places that ramp as the central operational catalyst. Investors are watching for concrete updates around stope development, processing performance and recoveries as EC120 tonnage increases.
Antimony recovery testing at Cosalá adds an extra layer of optionality. If the metallurgy proves reliable at scale, antimony could diversify revenue that is currently heavily tied to silver and copper. That potential sits beside existing risks around high AISC, a concentrated mine base and reliance on external borrowing, so execution quality on both fronts will matter.
Americas Gold and Silver's current analyst narrative points to $557.4 million in revenue and $205.5 million in earnings by 2029. That profile is built on revenue growing 45.3% per year and an earnings swing of about $253.2 million, from a loss of $47.7 million today to the $205.5 million level in the forecast period.
Uncover why Americas Gold and Silver's fair value indicates a 103% potential upside to its current price that could narrow quickly.
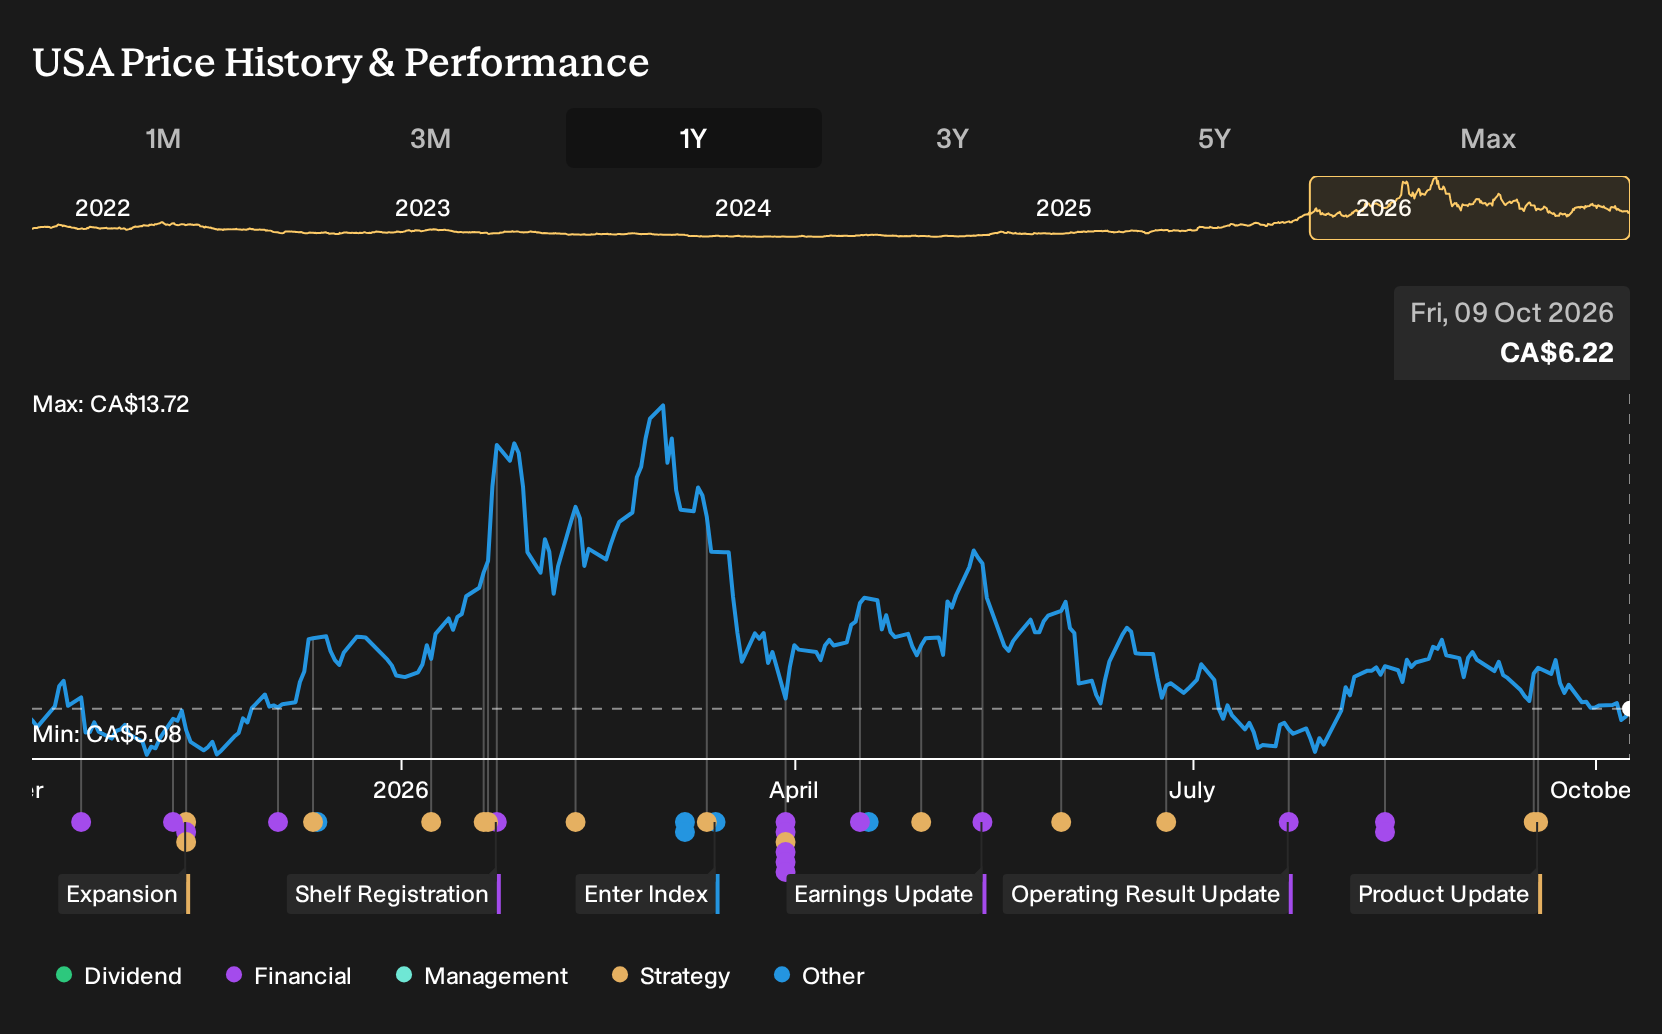
Exploring Other Perspectives
One alternate view leans hard into antimony at Americas Gold and Silver. Bullish analysts were already pencilling in revenue of $625.8 million and earnings of $233.0 million by 2029, compared with the consensus $557.4 million and $205.5 million. Those projections came before this news, so you may want to compare several viewpoints and decide which feels realistic.
Explore 3 other Americas Gold and Silver fair value estimates, including one that suggests up to 141% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own independent analysis.
- A great starting point for your Americas Gold and Silver research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Americas Gold and Silver. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Americas Gold and Silver's overall financial health at a glance.
Looking For More Investment Ideas Beyond Americas Gold and Silver?
Once you have formed a view on Americas Gold and Silver, it can help to stress test that thinking by comparing it with other opportunities that fit different risk and income profiles. The Simply Wall St Screener gives you curated sets of stocks so you can quickly move from a single story to a watchlist of ideas to explore further.
- If capital preservation matters most to you, start with a group of lower risk profiles using our 7 resilient stocks with low risk scores to see which businesses line up with that preference.
- If balance sheet strength is a priority, sort through companies on the list of solid balance sheet and fundamentals (7 results) and focus on those backing their operations with sturdier finances.
- If you want to uncover lesser known opportunities, scan the 9 high quality undiscovered gems to find candidates that may not yet be widely followed but still show solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com