


Erie Indemnity (ERIE) Slides Into A Valuation Debate, Is It A Bargain?
Erie Indemnity (ERIE) has drawn fresh attention after its recent share performance, with the price closing at US$222.04. Investors are reassessing what the current valuation implies for future returns.
Over the past few months, momentum around Erie Indemnity has cooled, with the 30 day share price return down 9.38% and the year to date share price return down 20.07%, while the 1 year total shareholder return has declined 29.92% despite a positive 25.37% total shareholder return over five years.
Scan beyond Erie Indemnity and compare its recent pullback with a curated 30 high quality undervalued stocks that share strong fundamentals and may be priced below what their earnings power suggests.
Erie Indemnity now trades at an estimated 15% discount to its assessed fair value, even after a sharp reset in the share price. Is that caution overdone, or exactly what the fundamentals warrant?
Price-to-Earnings of 20.1x: Is it justified?
Erie Indemnity now trades on a P/E of 20.1x, which is rich relative to many insurance peers and sits against a last close of $222.04 that already reflects a stronger earnings valuation multiple.
P/E compares what investors are paying for each dollar of current earnings. For an insurance services group like Erie Indemnity, this ratio helps you see how the market values its profit stream relative to other insurers that share similar business risks and capital needs.
The stock carries a P/E of 20.1x, while the broader US Insurance industry sits at 10.8x and the peer group average is 12.1x. That is a clear premium, which indicates that the market is pricing Erie Indemnity more expensively than both its sector and closer comparables, even though recent earnings growth has moved in the opposite direction over the last year.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 20.1x (OVERVALUED)
Still, the picture can change quickly if Erie Indemnity faces weaker fee income from the Erie Insurance Exchange or a reset in investor appetite for higher P/E insurance stocks.
Find out about the key risks to this Erie Indemnity narrative.
Another View: Erie Indemnity Through A Cash Flow Lens
The market is treating Erie Indemnity as expensive on a 20.1x P/E, yet our DCF model points in a different direction. On that cash flow based view, the shares trade around $222.04 compared with an estimated value of $262.74, which implies they are undervalued.
This gap between an earnings multiple that looks full and a cash flow estimate that suggests upside raises a practical question for you as an investor: which lens feels more reliable for a fee based insurance services group that relies heavily on long term contracts and recurring revenue streams?
Look into how the SWS DCF model arrives at its fair value.
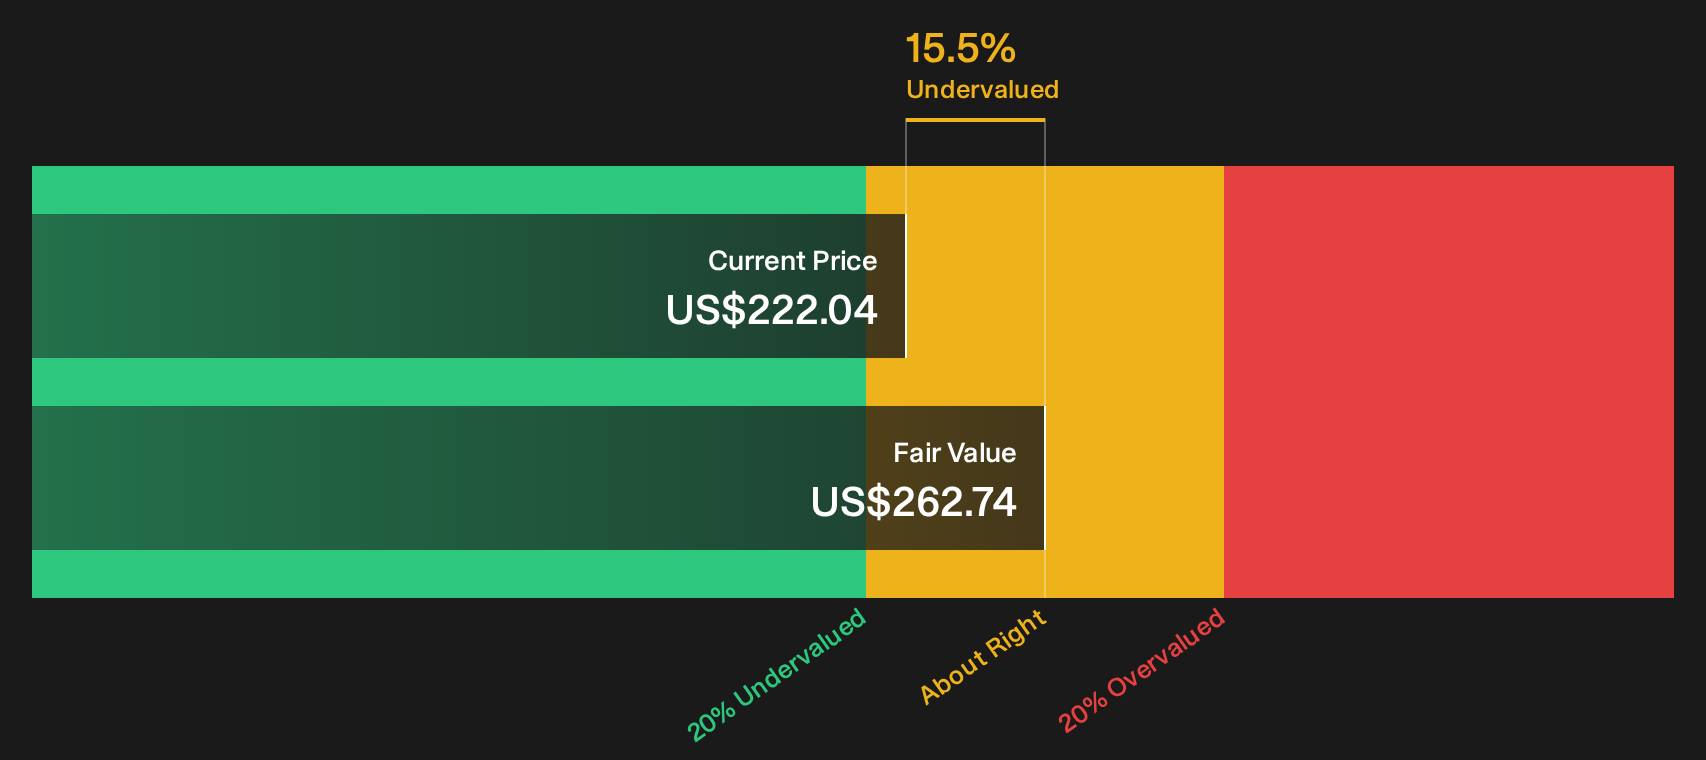
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Erie Indemnity for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals around Erie Indemnity leave you torn, use that tension as a prompt to check the underlying data yourself and move with intent. To see why at least one factor still has investors optimistic, review the 2 key rewards
Looking for more investment ideas beyond Erie Indemnity?
Do not stop at Erie Indemnity. Broaden your watchlist with fresh opportunities that fit different portfolio goals so you are not relying on a single story.
- Target potential mispricing by scanning a curated 30 high quality undervalued stocks that aligns strong business quality with prices that may sit below underlying fundamentals.
- Strengthen portfolio resilience by reviewing a 31 resilient stocks with low risk scores that focuses on companies with more measured risk profiles and steadier characteristics.
- Spot early opportunities by filtering a 20 high quality undiscovered gems that highlights underfollowed stocks with robust fundamentals before wider attention arrives.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com